















4 Chargeback Response Templates for Winning Friendly Fraud Disputes

Chargebacks?
Dat is niet langer jouw probleem.
Haal 4x meer chargebacks terug en voorkom tot 90% van de inkomende betalingen, dankzij AI en een wereldwijd netwerk van 20.000 handelaren.


 Meer dan 600 beoordelingen


TL;DR:
- Every winning chargeback rebuttal letter uses the same five-part structure regardless of reason code: transaction identification, direct rebuttal of the claim, a supporting evidence list, a policy or terms reference, and a closing ask.
- Four ready-to-copy chargeback response templates are included below for physical goods not received, digital goods not received, not as described, and unauthorized transaction disputes, the reason code most friendly fraud claims fall under.
- A reason-code-to-evidence mapping table shows exactly what to emphasize for fraud, authorization, consumer dispute, and processing error codes.
- Chargebacks911's 2026 Field Report puts merchant chargeback response win rates around 44% on the first cycle, though net recovery falls to just 10.7% once second-cycle reversals are counted; Chargeflow's own automated representment data shows win rates as high as 75% on the same dispute types.
- Response deadlines are strict: network rulebooks allow roughly 30 calendar days for Visa, 45 for Mastercard, and 20 for Discover and Amex, but processors like Stripe give merchants only 7 to 21 days in practice, so submit before your processor's deadline regardless of how strong your evidence is.
A chargeback response template is a structured rebuttal letter format that you customize with transaction-specific evidence to contest a disputed charge with the card network or issuing bank. It is also called a chargeback rebuttal letter, a chargeback dispute template, or a representment letter, and the same core structure applies no matter which reason code you are fighting, whether that is fraud, an authorization issue, a consumer complaint, or a processing error.
I'm yet to meet any eCommerce entrepreneur who loves the uphill journey of fighting fraudulent chargebacks. It's a time-consuming process, and in 2026, it's only gotten harder.
According to Chargeflow's chargeback statistics report, global chargeback value is projected to climb from $33.79 billion in 2025 to $41.69 billion by 2028 (Mastercard data). And per the 2026 LexisNexis True Cost of Fraud study, US retail and ecommerce merchants now pay $5.13 in total costs for every $1 lost to fraud, the first time that multiplier has crossed $5, once you factor in fees, operational time, and lost merchandise.
Many of these disputes are driven by friendly fraud, where legitimate customers challenge valid transactions. Chargeflow's own merchant data puts friendly fraud at roughly 75% of eCommerce disputes today, and 72% of merchants reported a further increase in friendly fraud last year.
Toch zijn er geheimen van insiders die, mits correct toegepast, de kans op succes in jouw voordeel kunnen doen kantelen.
By and large, your success or failure in countering fraudulent chargebacks depends on two things:
- Strikte naleving van de procedures voor herziening
- Het verzamelen van substantieel en relevant bewijsmateriaal om een overtuigend betoog te kunnen voeren
Those two factors make or break your prospects. In this article, I'm sharing four ready-to-use chargeback response templates, complete with chargeback rebuttal letter examples, plus a deeper line-by-line writing walkthrough, that you can copy and paste for the toughest chargeback reason codes. Feel free to adapt each chargeback template letter as you see fit. Just make sure to submit before your response deadline. For the complete list of codes by network, see our guide to chargeback reason codes.
The Universal Chargeback Rebuttal Letter Framework
Before you jump to a specific template, it helps to know why these templates work. Every winning chargeback rebuttal letter, regardless of the reason code behind it, is built from the same five structural elements. Learn this framework once and you can adapt it to any dispute your business receives, not just the friendly fraud cases this article started with.
- Transaction identification. Open with the transaction ID, chargeback case number, dollar amount, transaction date, and the last four digits of the card used. This lets the reviewer match your letter to the correct case instantly.
- Direct rebuttal of the specific claim. State the cardholder's exact reason code claim in plain language, then state your counter-position in one sentence. Do not make the reviewer infer what you are disputing.
- Supporting evidence list. Reference each exhibit by letter (Exhibit A, B, C) and describe what it proves. This is the largest part of the letter and where reason-code-specific evidence belongs, see the mapping table below.
- Policy or terms reference. Quote the specific line from your refund policy, terms of service, or shipping policy that the cardholder agreed to at checkout, along with the date they agreed to it.
- Closing ask. End with a direct, unemotional request that the reviewer rule in your favor based on the attached evidence, plus your contact details for follow-up questions.
The four templates below apply this exact framework to the reason codes merchants dispute most often. Template #4 shows the framework applied to an unauthorized-transaction case, the reason code that most friendly fraud disputes fall under.
Chargeback Template Emphasis by Reason Code Category
Not every exhibit matters equally for every dispute. Use this table to decide what to lead with in your evidence list before you start drafting:
| Reason code category | Example codes | What to emphasize in your rebuttal |
|---|---|---|
| Fraud codes (card-absent, unauthorized use) | Visa 10.4, Mastercard 4863, Amex F29, Discover UA02 | 3DS2 authentication response codes, AVS and CVV match results, device fingerprinting and IP logs, and any prior order history tying the device or shipping address to the cardholder |
| Authorization codes | Visa 11.x, Mastercard 4808 | The original authorization approval code and timestamp, proof the transaction matched the authorized amount and currency, and confirmation the authorization had not expired at settlement |
| Consumer dispute codes (not as described, quality) | Visa 13.3, Mastercard 4853, Amex C31, Discover RM | Product listing screenshots from the time of purchase, your stated refund or return policy, and any customer service correspondence describing the alleged defect |
| Processing error codes | Visa 12.x, Mastercard 4834/4842 | Transaction logs showing a single authorization and settlement (to rebut duplicate processing claims), and the exact credit or refund date if one was already issued |
Redenen voor terugboekingen per netwerk (beknopte gids)
Elk van de onderstaande sjablonen komt overeen met een van deze veelvoorkomende soorten geschillen. Gebruik deze tabel om uw chargeback aan de juiste redencode te koppelen voordat u met uw weerlegging begint:
| Soort geschil | Amex | Ontdek | Mastercard | Visum |
|---|---|---|---|---|
| Niet-ontvangen goederen/diensten | C08 | RG | 4855 | 13.1 |
| Niet zoals beschreven / Defect | C31 | RM | 4853 | 13.3 |
| Ongeautoriseerd / Fraude (zonder kaart) | F29 | UA02 | 4863 | 10.4 |
Sjabloon voor reactie op terugvordering #1: Fysieke goederen niet ontvangen
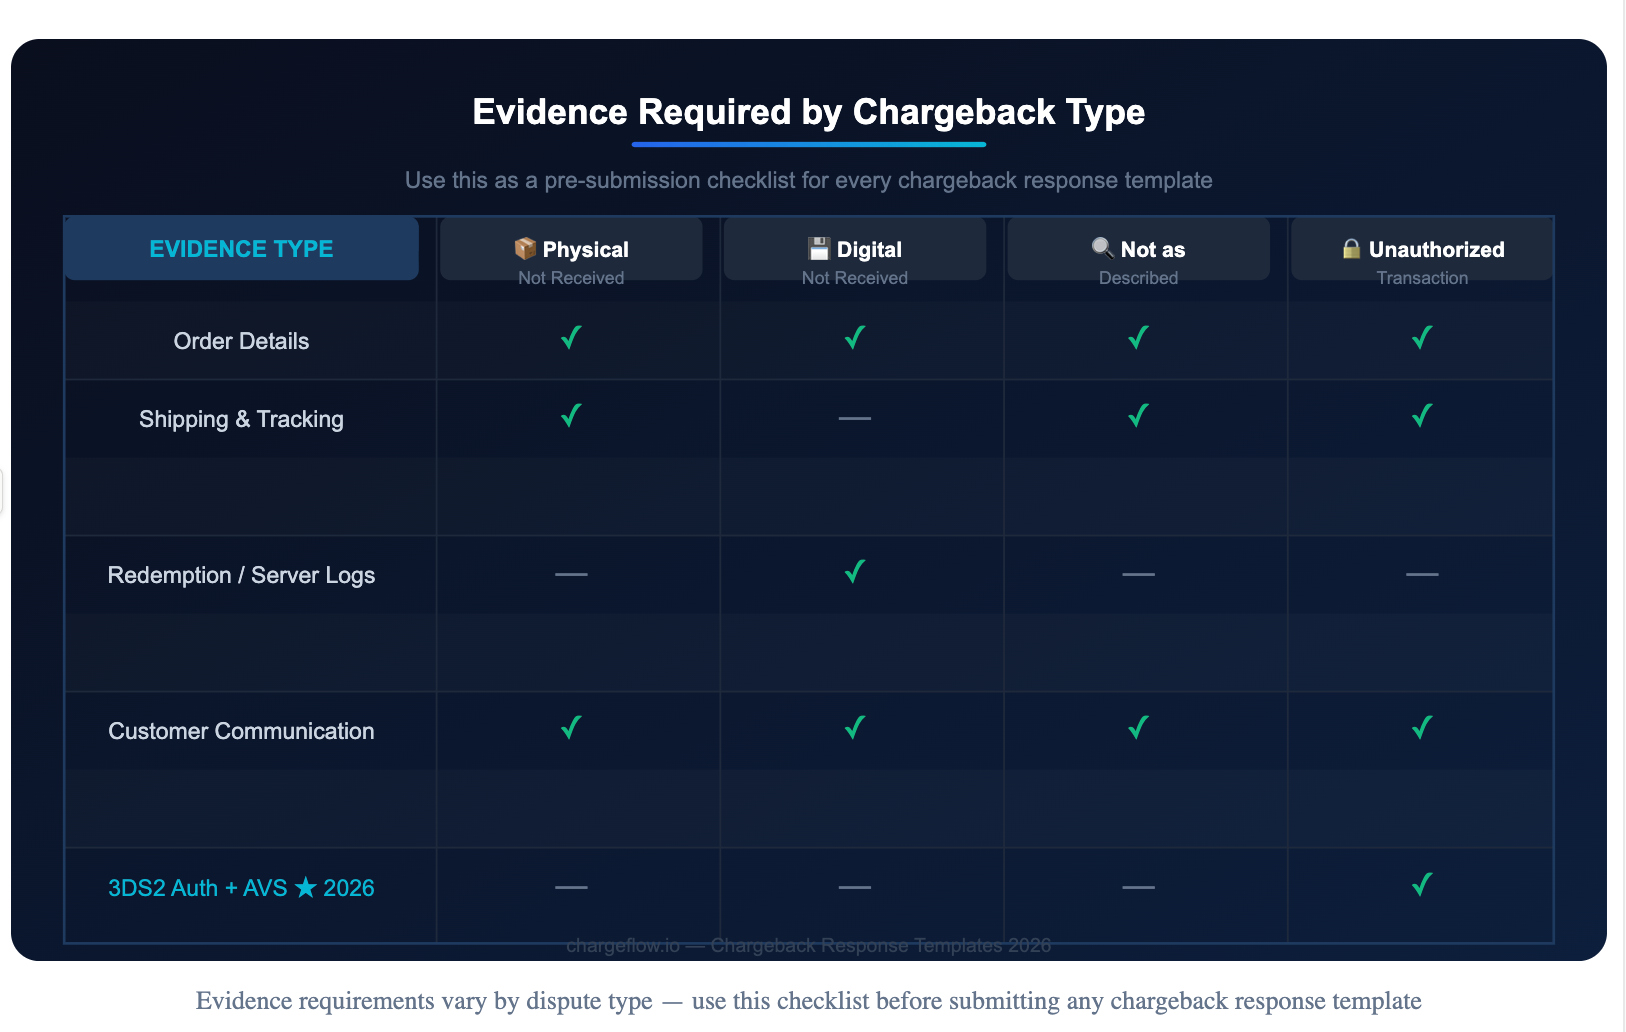
Meldingen van frauduleuze terugboekingen in verband met niet-ontvangen bestellingen worden weergegeven met de volgende redencodes:
- AMEX C08: Goederen/diensten die niet of slechts gedeeltelijk zijn ontvangen
- Ontdek RG: Niet-ontvangst van goederen, diensten of contant geld
- Mastercard 4855: Niet-geleverde goederen of diensten
- Visa 13.1: Niet-ontvangen goederen/diensten
Probeer, voordat u bezwaar aantekent, rechtstreeks contact op te nemen met de klant om uit de eerste hand inzicht te krijgen in de kwestie. U kunt de klant ook het trackingnummer van de bestelling per e-mail sturen, want die communicatie vormt een cruciaal bewijsstuk bij het aanvechten van de frauduleuze terugvordering.
Belangrijke documenten die u bij uw herzieningsverzoek moet voegen:
- Bestelgegevens (met uitzondering van persoonlijk identificeerbare informatie)
- Informatie over de verzending van bestellingen vanaf uw bedrijfsadres, inclusief bezorgbevestiging en trackingnummer
- Relevante communicatie met klanten en eventueel ander ondersteunend bewijsmateriaal
Hoe schrijf je een standaardbrief voor een terugvordering aan de bank:
Onderwerp: TRN #XYZ, CHG-BK-code: XXX X
Aan wie het aangaat,
We hebben TRN XYZ zorgvuldig bekeken en willen bezwaar maken tegen de terugvordering [voeg terugvorderingsnummer toe] ter waarde van $[voeg bedrag in dollars toe] met als reden: „Bestelling niet ontvangen.”
{Exhibit A}: [Include the customer's name] made the credit card transaction on [add date] with a credit card ending in [add the last four digits of the payment card].
{Exhibit B}: We delivered the cardholder's package to their stated address on [add order delivery date] through [add the shipping carrier] with the tracking number XXXXXX.
{Exhibit C}: We tried to resolve the cardholder's issue on [add date] by contacting them directly with the order tracking details, which confirmed the package's arrival. As the attached documentation shows, they did not respond to multiple contact attempts.
Wij verzoeken u vriendelijk de bijgevoegde documenten door te nemen, waaruit blijkt dat de bewering van de kaarthouder dat het product niet is ontvangen, onjuist is, en deze geschilzaak in ons voordeel te beslechten.
Mocht u vragen hebben of meer informatie nodig hebben, kunt u rechtstreeks op deze e-mail reageren.
Met vriendelijke groet,
[Voeg je gegevens toe]
Pro-tip (update 2026): Grote kaartnetwerken accepteren nu GPS-bevestigingsgegevens van vervoerders en foto’s van de levering ter staving van de locatie als overtuigend bewijs bij geschillen over fysieke goederen. Als uw vervoerder deze gegevens verstrekt, voeg ze dan toe als aanvullend bewijsstuk in uw sjabloon voor het beantwoorden van chargebacks.
Sjabloon voor reactie op terugvordering #2: Digitale goederen niet ontvangen
This category of fraudulent chargeback is represented by the following reason codes:
- AMEX C08: Goederen/diensten die niet of slechts gedeeltelijk zijn ontvangen
- Ontdek RG: Niet-ontvangst van goederen, diensten of contant geld
- Mastercard 4855: Niet-geleverde goederen of diensten
- Visa 13.1: Niet-ontvangen goederen/diensten
Winning a Digital Goods Not Received chargeback can be tricky because there is no physical trackability option. However, there are measures you can take to mitigate this challenge. Before fighting such a chargeback, contact the card issuer by email and share a screenshot showing that the digital good was claimed. That documentation is often the deciding factor when banks review your chargeback rebuttal letter.
As of 2026, digital goods and services have seen a dramatic spike in chargeback rates, driven largely by subscription services and downloadable products. According to Chargeflow's chargeback data, chargebacks cost eCommerce merchants over $33 billion in 2025 alone, making a well-crafted chargeback rebuttal letter template more important than ever for SaaS and digital merchants.
Documenten die u bij uw herzieningsverzoek moet voegen:
- Bestelgegevens (met uitzondering van persoonlijk identificeerbare informatie)
- Bevestigingsmail en inwisselcode
- Aflossingsdatum, computerlogboeken en tijdstempels
- Gegevens over apparaten en IP-adressen waaruit blijkt dat er toegang is verkregen tot het digitale product
- Relevante communicatie met klanten
Hoe schrijf je een weerwoordbrief tegen een terugvordering aan de bank met behulp van dit sjabloon voor het betwisten van een terugvordering:
Onderwerp: TRN #XYZ, CHG-BK-code: XXX X
Aan wie het aangaat,
We hebben de TRN XYZ zorgvuldig gecontroleerd en willen bezwaar maken tegen de terugvordering [nummer van de terugvordering invoegen] ter waarde van $[bedrag in dollars invoegen] met als reden: „Goederen niet ontvangen.”
{Exhibit A}: [Include the customer's name] made the transaction on [add date] with a credit card ending in [add the last four digits of the payment card].
{Exhibit B}: We delivered the order confirmation and redemption code to the email address the cardholder provided at the point of the original transaction on [add date].
{Exhibit C}: The cardholder redeemed the digital good they purchased on [add date] at [add time], as evidenced by the server logs and IP address records attached.
{Exhibit D}: We attempted to resolve the cardholder's issue on [add date] by contacting them directly with the redemption details showing that the digital goods had been claimed.
Wij verzoeken u vriendelijk de bijgevoegde documenten door te nemen, waaruit blijkt dat de bewering van de kaarthouder dat de digitale goederen niet zijn ontvangen, onjuist is, en deze geschilzaak in ons voordeel te beslechten.
Mocht u vragen hebben of meer informatie nodig hebben, kunt u rechtstreeks op deze e-mail reageren.
Met vriendelijke groet,
[Voeg je gegevens toe]
Pro-tip (update 2026): In de bijgewerkte geschillenregels van Visa voor 2026 worden apparaat-fingerprintgegevens en sessielogboeken nu expliciet erkend als geldig bewijsmateriaal bij geschillen over digitale goederen. Neem contact op met je platform- of hostingprovider om deze logboeken vóór de deadline voor herziening op te vragen en neem ze op in je standaardbrief voor chargebacks.
For a full worked example of what a winning Stripe evidence packet looks like for a digital-goods dispute, see what proof Stripe accepts for digital goods disputes.
Sjabloon voor reactie op terugvordering #3: Product of dienst wijkt af van de beschrijving
This category of fraudulent chargebacks is represented by the following reason codes:
- AMEX C31: Goederen/diensten die niet aan de beschrijving voldoen
- Ontdek RM: Kaarthouder betwist de kwaliteit van goederen of diensten
- Artikel 13.3: Goederen/diensten die niet aan de beschrijving voldoen of gebreken vertonen
Product not as described disputes remain one of the most common chargeback categories in 2026, fueled in part by the rise of social commerce, where product imagery can diverge from physical reality. Before fighting the chargeback, contact the cardholder by email and ask them to specify how the product or service they received differs from what you advertise. That communication forms a crucial part of your evidence package.
Documenten die u bij uw herzieningsverzoek moet voegen:
- Verzendgegevens van de bestelling, waaronder een bezorgbevestiging, een afleverbewijs en een trackingnummer
- Uw terugbetalings- of annuleringsbeleid zoals vermeld op uw website op het moment van aankoop
- Relevante communicatie met klanten
- Gedetailleerde productinformatie, afbeeldingen vanuit verschillende hoeken, productbeschrijving en product-URL
- Screenshots van de productpagina van uw website op het moment van de transactie (gebruik indien nodig archieftools)
Hoe schrijf je een standaardantwoordbrief voor een terugvordering aan de bank voor dit type geschil:
Onderwerp: TRN #XYZ, CHG-BK-code: XXX X
Aan wie het aangaat,
We hebben TRN XYZ zorgvuldig bekeken en willen bezwaar maken tegen de terugvordering [nummer van de terugvordering invoegen] ter waarde van $[bedrag in dollars invoegen] met als reden: „Niet zoals beschreven.”
{Exhibit A}: We delivered the package to the address issued by the cardholder at the point of the transaction on [add date] via [add the shipping carrier] with the tracking number XXXXXX.
{Exhibit B}: Per our refund policy, "[add your binding refund policy]." The cardholder agreed to that policy at the point of checkout on [add date].
{Exhibit C}: We attempted to resolve the cardholder's issue on [add date] by ascertaining the specific variation between the product they received and what they ordered. As the email thread (Exhibit D) demonstrates, the cardholder's description of the item, "xxxxxxxxx," is indistinguishable from the photos and product description on our website.
{Exhibit D}: Screenshots of our product listing page at the time of purchase, confirming the item description and imagery the cardholder viewed before completing checkout.
Wij verzoeken u vriendelijk de bijgevoegde documenten door te nemen, waaruit blijkt dat de vordering van de kaarthouder ongegrond is, en deze geschilzaak in ons voordeel te beslechten.
Mocht u vragen hebben of meer informatie nodig hebben, kunt u rechtstreeks op deze e-mail reageren.
Met vriendelijke groet,
[Voeg je gegevens toe]
Pro-tip (update 2026): Volgens de bijgewerkte richtlijnen van Mastercard voor geschillen mogen verkopers nu videobewijs van productdemonstraties of unboxing-beelden indienen als aanvullende documentatie in gevallen waarin het product „niet overeenkomt met de beschrijving”. Als je over productdemonstratiemateriaal beschikt, voeg dan een link of een bijlage toe aan je voorbeeldbrief voor het weerleggen van een chargeback.
Sjabloon voor reactie op terugvordering #4: Ongeautoriseerde transactie
This category of fraudulent chargeback claims is represented by the following reason codes:
- AMEX F29: Kaart niet aanwezig
- Discover UA02: Fraud - Card Not Present Transaction
- Mastercard 4863: Cardholder Does Not Recognize - Potential Fraud
- Visa 10.4: Fraud - Card-Absent Environment
Unauthorized transaction chargebacks represent one of the largest shares of chargeback volume industry-wide, and it is the reason code most friendly fraud disputes land under, since the cardholder made and received the purchase but claims otherwise. The win rate for this particular reason code remains slim because disputes generally reference fraud claims. Mastercard and Visa will rule in favor of the cardholder automatically if they truly fell victim to fraud.
With that in mind, contact the cardholder before initiating representment. Send them an email sharing the tracking details of the item you shipped. That communication serves as one of the most valuable pieces of evidence to help you win. Many merchants lean on chargeback alerts to intercept disputes early.
In 2026 zijn de authenticatiegegevens van 3DS2 (3D Secure versie 2) een vrijwel doorslaggevende factor geworden. Als de transactie via 3DS2 is geauthenticeerd, neem dan de authenticatieresponscode op in uw sjabloon voor een weerwoordbrief bij een chargeback; hierdoor wordt de aansprakelijkheid in de meeste gevallen weer bij de kaartuitgever gelegd.
Documenten die u bij uw bezwaarschrift tegen de terugboeking moet voegen:
- Bestelgegevens (met uitzondering van persoonlijk identificeerbare informatie)
- Bevestigingsmail van de bestelling
- Verzendgegevens van de bestelling, inclusief bezorgbevestiging en trackingnummer
- 3DS2-authenticatie-antwoordcode (indien van toepassing)
- Apparaat-fingerprints en IP-adreslogs op het moment van de transactie
- Resultaten van de AVS (Address Verification System) en CVV-controle
- Relevante communicatie met klanten
Hoe schrijf je een brief ter weerlegging van een terugvordering aan de bank met behulp van dit sjabloon voor het betwisten van een terugvordering:
Onderwerp: TRN #XYZ, CHG-BK-code: XXX X
Aan wie het aangaat,
We hebben TRN XYZ zorgvuldig bekeken en willen bezwaar maken tegen de terugvordering [nummer van de terugvordering invoegen] ter waarde van $[bedrag in dollars invoegen] met als redencode: „Ongeautoriseerde transactie.”
{Exhibit A}: [Include the customer's name] made the transaction on [add date] with a credit card ending in [add the last four digits of the payment card]. The transaction was successfully authenticated via 3DS2, with authentication response code [add code], shifting dispute liability under current network rules.
{Exhibit B}: A few minutes following the order request, at [add time] on [add date], our office sent an order confirmation to the email address the cardholder provided at the point of legitimate purchase.
{Exhibit C}: We delivered the cardholder's package to their stated address on [add order delivery date] through [add the shipping carrier] with the tracking number XXXXXX.
{Exhibit D}: We attempted to resolve the cardholder's issue on [add date] by contacting them directly with the order tracking details, which confirmed the package's arrival. As the documentation shows, the cardholder confirmed that the order's shipping address is their address.
Gezien dit overtuigende bewijs verzoeken wij u vriendelijk de bijgevoegde documenten te bekijken, waaruit blijkt dat de vordering van de kaarthouder ongegrond is, en deze geschilzaak in ons voordeel te beslechten.
Mocht u vragen hebben of meer informatie nodig hebben, kunt u rechtstreeks op deze e-mail reageren.
Met vriendelijke groet,
[Voeg je gegevens toe]
Hoe je elk sjabloon voor een reactie op een chargeback kunt verbeteren
Ongeacht welk sjabloon voor terugboekingen u gebruikt, hebben de sterkste weerleggingspakketten een aantal gemeenschappelijke kenmerken:
- Begin met een duidelijke, beknopte begeleidende brief. Uw standaardbrief voor een terugvordering moet beginnen met een samenvatting van uw zaak in één alinea, voordat u de bewijsstukken presenteert. Arbiters behandelen honderden geschillen; zorg ervoor dat uw betoog in één oogopslag te overzien is.
- Label and reference every exhibit. Each piece of evidence in your chargeback response templates should be clearly labeled (Exhibit A, B, C) and cross-referenced in the body of your letter.
- Keep it factual, not emotional. Banks are not mediators; they're evaluating evidence against reason codes and network rules. Your chargeback dispute template should read like a legal brief, not a complaint.
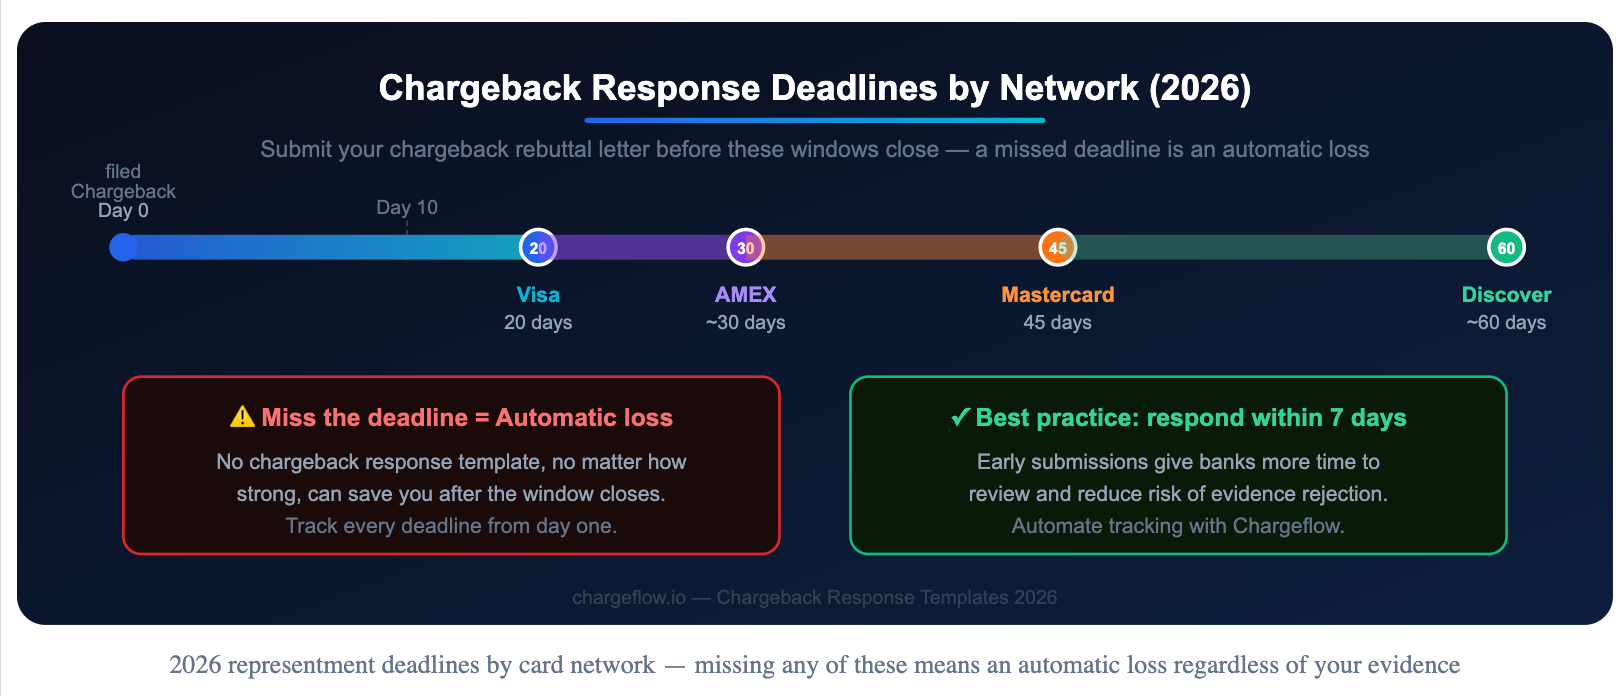
- Meet deadlines without exception. Network rulebooks set merchant response windows at roughly 30 calendar days for Visa, 45 days for Mastercard, and 20 days for Discover and Amex, but your processor's actual deadline is usually shorter: Stripe tells merchants to expect 7 to 21 days depending on the network. See our full chargeback time limit breakdown for the network-by-network detail. Missing your processor's deadline means an automatic loss, regardless of how strong your evidence is.
- Pas de brief aan voor elk netwerk. Hoewel de structuur van een sjabloon voor een weerwoord bij een terugvordering altijd hetzelfde blijft, verschillen de specifieke redencodes, bewijsvereisten en deadlines per kaartnetwerk. Controleer altijd of de brief voldoet aan de regels van het betreffende netwerk voordat u deze indient.
- Pull data from your payment stack. Your payment service provider can usually supply the AVS, CVV, and 3DS2 authentication data referenced in the reason-code table above; request it as soon as a dispute notification arrives, not after your deadline is already close.
A stronger, more complete factual record like this can support a well-reasoned response, but it does not guarantee the issuing bank's decision. Issuers weigh evidence against their own network rules, and outcomes vary case by case.
A New Wrinkle: Chargebacks From AI Shopping Agents
A growing share of disputes now start with a purchase an AI agent made on a customer's behalf rather than the customer directly, and evidence like "the cardholder personally clicked checkout" no longer holds up the way it used to. If you sell in categories where agentic checkout tools are gaining traction, it is worth understanding AI agent chargeback liability and reading our Agentic commerce chargebacks evidence playbook before this shows up in your own dispute queue. The same five-element framework above still applies, but exhibit types like agent authentication logs and delegated-payment consent records are becoming part of a well-built chargeback rebuttal letter.
Wanneer kun je in plaats daarvan gebruikmaken van geautomatiseerd chargebackbeheer?
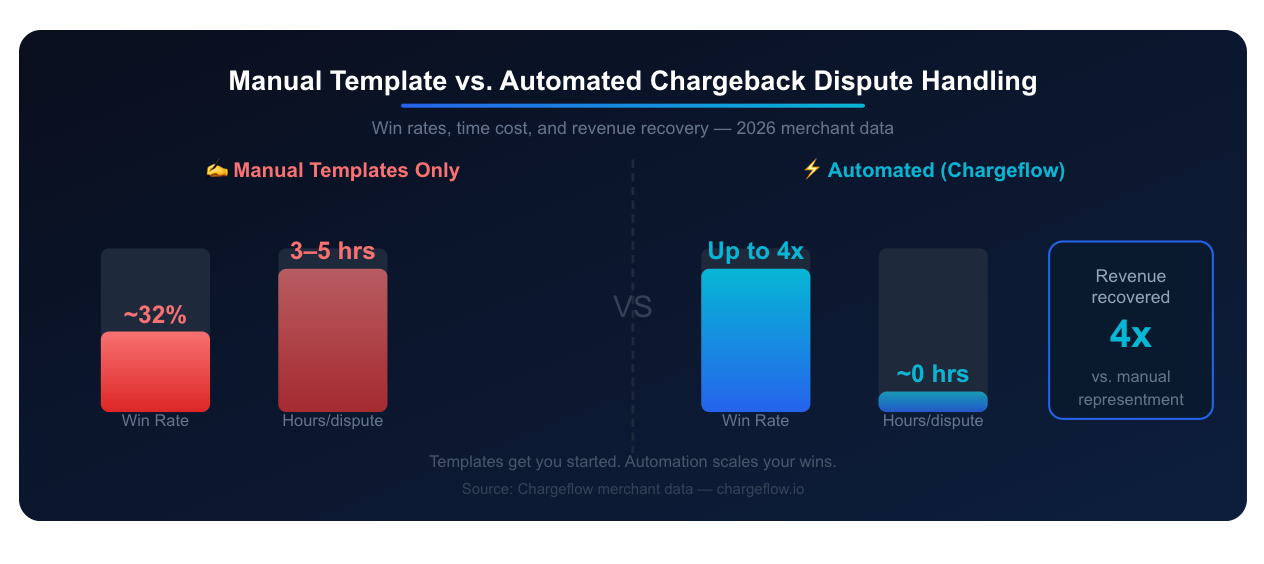
Using a chargeback response template manually is a solid starting point, but it has real limits at scale. If you're processing more than 50 chargebacks per month, manual representment becomes unsustainable. Each dispute requires research, customization, and precise timing, and a single missed deadline costs you the case outright.
Automated chargeback management tools, like Chargeflow, give you flexibility and control over the entire representment process. Instead of doing painful labor manually or juggling multiple programs, chargeback automation provides a single platform that uses AI-powered fraud detection, network-specific evidence mapping, and automatic deadline tracking to fight disputes on your behalf. Pairing automated chargeback protection with template-based representment, alongside a broader ecommerce fraud prevention strategy, gives you prevention and recovery in one workflow.
Industry-wide, merchants who represent disputes win an average of 44% of first-cycle cases, according to Chargebacks911's 2026 Field Report, though net recovery falls to just 10.7% once cases escalated to a second cycle are factored in. Chargeflow's own data shows AI-driven, automated representment achieving win rates as high as 75% on comparable dispute types, while also saving an average of $315 per dispute in labor and fees, and helping merchants recover significantly more revenue from friendly fraud.
Veelgestelde vragen over sjablonen voor reacties op terugboekingen
Wat moet er in een sjabloon voor een reactie op een terugvordering staan?
Een goed sjabloon voor een reactie op een terugvordering moet een onderwerpregel bevatten met het transactienummer en de terugvorderingscode, een korte inleidende alinea waarin u aangeeft dat u de terugvordering betwist, duidelijk gelabelde bewijsstukken (bestelgegevens, verzendbevestiging, communicatie met de klant) en een afsluitend verzoek om een uitspraak in uw voordeel. Elk sjabloon voor een reactie op een terugvordering moet worden afgestemd op de specifieke redencode van het geschil.
What is a chargeback rebuttal letter?
A chargeback rebuttal letter, sometimes called a representment letter, is the formal written argument you submit to the card network or issuing bank contesting a chargeback. It presents your evidence and explains why the transaction was legitimate. For a broader look at how chargebacks work end to end, see what is a chargeback. A well-written chargeback rebuttal letter example will clearly reference each exhibit and directly address the cardholder's stated reason for disputing.
Kan ik voor alle redencodes hetzelfde sjabloon voor terugvorderinggeschillen gebruiken?
De algemene opbouw van een sjabloon voor een chargeback-geschil blijft voor alle redencodes hetzelfde, maar het bewijsmateriaal dat u toevoegt, moet specifiek zijn voor het soort geschil. Zo zijn voor een sjabloon voor een chargeback met de reden „niet zoals beschreven” productafbeeldingen en uw retourbeleid vereist, terwijl voor een sjabloon voor een „ongeautoriseerde transactie” authenticatielogboeken en AVS-resultaten nodig zijn. Zorg er altijd voor dat uw bewijsmateriaal voldoet aan de geldende netwerkregels.
Hoeveel sjablonen voor reacties op terugboekingen moet een handelaar hebben?
Handelaren moeten in ieder geval standaardreactiesjablonen bijhouden voor de vier meest voorkomende categorieën van geschillen: niet-ontvangen fysieke goederen, niet-ontvangen digitale goederen, goederen die niet aan de beschrijving voldoen, en ongeautoriseerde transacties. Handelaren met een groot transactievolume kunnen ook gespecialiseerde sjablonen voor chargebacks gebruiken voor geschillen over opzeggingen van abonnementen en claims inzake niet-verwerkte crediteringen.
What is the deadline for submitting a chargeback response?
Network rulebooks generally allow 30 calendar days for Visa, 45 days for Mastercard, and 20 days for Discover and American Express. But those are network limits, not necessarily what your processor gives you: Stripe, for example, tells merchants to expect a real response window of 7 to 21 days depending on the card network. Always track the deadline shown in your own dispute dashboard, since regardless of how strong your chargeback rebuttal letter template is, missing it results in an automatic loss.
Is het gebruik van een sjabloon voor een reactie op een chargeback een garantie voor succes?
Geen enkel sjabloon voor een reactie op een chargeback garandeert succes, maar het gebruik van een goed gestructureerd sjabloon vergroot uw kansen aanzienlijk. De kaartnetwerken beoordelen geschillen op basis van de kwaliteit en relevantie van uw bewijsmateriaal in het licht van hun specifieke chargeback-redencodes en -regels. Een sterk voorbeeld van een weerwoordbrief bij een chargeback, met volledige, goed geordende documentatie, scoort steevast beter dan geïmproviseerde of onvolledige inzendingen.
What evidence is most persuasive in a chargeback rebuttal letter?
The most persuasive evidence in any chargeback rebuttal letter is documentation that directly contradicts the cardholder's claim. For delivery disputes, this means carrier confirmation with GPS or photo proof. For digital goods, it means server logs and redemption timestamps. For unauthorized transactions in 2026, 3DS2 authentication codes are often decisive. Always organize your evidence chronologically and reference it clearly in your chargeback dispute template.
Hoe stel ik een standaardbrief voor een terugvordering op?
Een goed sjabloon voor een chargeback-brief moet een duidelijke onderwerpregel bevatten waarin de transactie en de redencode worden vermeld, een professionele aanhef („Aan wie het aangaat”), een gestructureerde hoofdtekst met opeenvolgend genummerde bijlagen, en een beleefde maar vastberaden afsluiting waarin u om een uitspraak in uw voordeel vraagt. De opmaak van uw sjablonen voor chargeback-reacties moet overzichtelijk en professioneel zijn en geen emotionele taal bevatten; u legt bewijsmateriaal voor, u voert geen discussie.
What's the difference between a chargeback rebuttal letter and a chargeback response template?
They describe the same document from two angles: a chargeback response template is the reusable structure you fill in each time, while a chargeback rebuttal letter is the finished, transaction-specific letter you actually submit. Every rebuttal letter on this page follows the five-part framework above, so once you have used one template, adapting it to your next case takes minutes rather than a rewrite.
Chargebacks?
Dat is niet langer jouw probleem.
Haal 4x meer chargebacks terug en voorkom tot 90% van de inkomende betalingen, dankzij AI en een wereldwijd netwerk van 20.000 handelaren.




