















Klarna vs. Affirm: Plans, Merchant Costs and Disputes


Chargebacks?
Dat is niet langer jouw probleem.
Haal 4x meer chargebacks terug en voorkom tot 90% van de inkomende betalingen, dankzij AI en een wereldwijd netwerk van 20.000 handelaren.


 Meer dan 600 beoordelingen


TL;DR:
- Both offer Pay in 4 at 0% APR for eligible US purchases, plus longer financing in supported programs.
- Shopper APR and merchant fees are different costs. Merchant pricing comes from your agreement or your payment platform.
- Settlement, refunds and dispute workflows differ by provider and integration. Affirm typically gives merchants 15 days to respond to a dispute.
- Fit depends on your checkout, customers and integration, not on company size.
Klarna and Affirm are buy now, pay later providers that let eligible shoppers spread the cost of a purchase while merchants receive settlement under their payment agreement. Both offer short-term installment options and longer financing in supported programs. Compare the plans available to your customers, the merchant economics and the post-purchase workflow.
This guide separates shopper terms from merchant responsibilities. Examples labeled US are US consumer terms, and company metrics are labeled with their own period and geography. For Afterpay and Sezzle alongside these providers, use the BNPL provider comparison, and see BNPL market statistics for market data.
Short answer: Both providers offer Pay in 4 at 0% APR for eligible US purchases, and both offer longer financing in supported programs. They differ in markets, program mix, merchant agreements and dispute workflows, so fit depends on your checkout, customers and integration rather than on company size.
How Klarna and Affirm Payment Plans Work for Shoppers
Shopper plans decide what your customers see at checkout. These are consumer terms (US examples), not merchant processing rates.
- Pay in 4: Both advertise four payments at 0% APR for eligible US purchases. Klarna describes later payments as collected every 14 days (Klarna US Pay in 4). Affirm states Pay in 4 is offered at 0% APR (Affirm US business disclosures).
- Longer financing: Affirm discloses longer financing at 0 to 36% APR depending on credit and the offer, with terms up to 5 years per the Federal Reserve FEDS Notes, June 2026. Klarna describes other payment and financing options by market and eligibility.
- Eligibility: Offers depend on the shopper, purchase and program. Check what appears for your own baskets.
Klarna versus Affirm: een vergelijking naast elkaar (2026)
Klarna: functies en overzicht in één oogopslag
Klarna combines payment options with a shopper experience that can support discovery, checkout and post-purchase order management. For merchants, the relevant question is which programs are enabled for the country, channel and integration they plan to launch. A direct connection and a PSP-routed connection should each be evaluated on their own terms.
Hoe werkt Klarna? Belangrijkste kenmerken
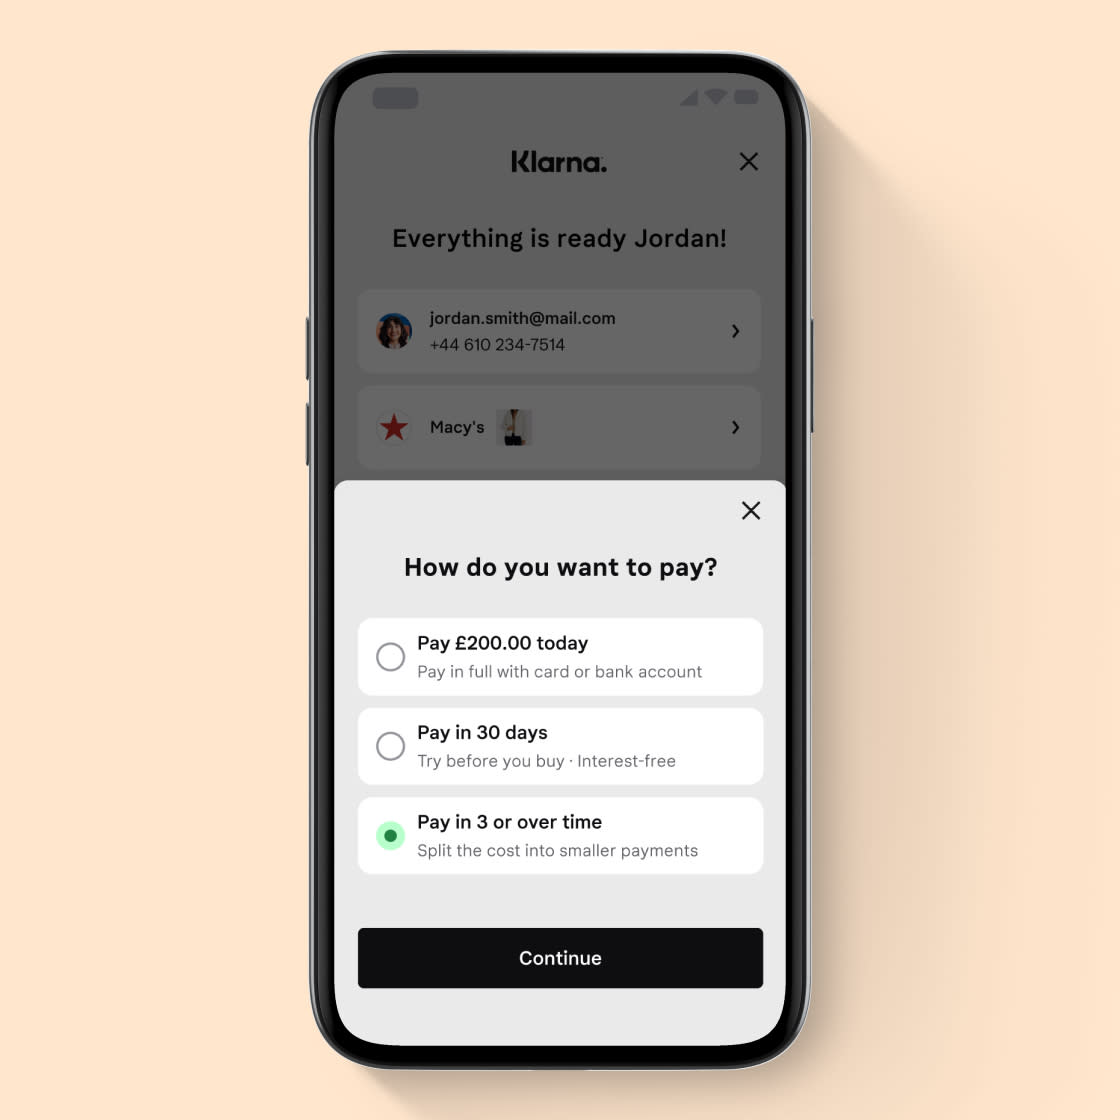
With US Klarna Pay in 4, eligible shoppers split their purchase into four interest-free payments. Klarna describes subsequent payments as collected every 14 days. Its US payment information also describes other options, including monthly financing for eligible purchases. Review the current Klarna plan details for the offered payment schedule and disclosures.
Keep shopper messaging synchronized with the program actually offered at checkout. Record the order lines, chosen payment method, capture status, shipping events and refunds. These records give customer support and payment operations a shared view of the purchase. The Klarna integration connects supported accounts to Chargeflow.
Affirm Overzicht en functies in één oogopslag
Affirm gives merchants an installment-payment option that can be matched to purchase amount, customer eligibility and the available financing program. Its business offering includes online and omnichannel use cases. Evaluate the actual checkout presentation and financing terms that will apply to your products.
Affirm Belangrijkste kenmerken

Affirm's US disclosures state that Pay in 4 is offered at 0% APR, while other available financing can range from 0 to 36% APR based on credit and eligibility. Payment options vary by merchant and purchase, and a down payment may apply. These are consumer financing terms, not the merchant's processing rate. Source: Affirm US business disclosures. The Affirm integration connects supported accounts to Chargeflow.
For higher-value purchases or a catalog with varied order sizes, test the payment options shown for representative baskets. Include the full payment journey through capture, refund, customer support and reconciliation so your team can assess the operating fit as well as the checkout experience.
Klarna-kosten versus kosten van de ‘ Affirm ’: het volledige overzicht
Merchant fees for Klarna and Affirm depend on the commercial schedule for the product and integration you use. A shopper's interest rate, a promotional financing offer and a PSP's published processing rate describe different costs, so keep them in separate columns of your model.
Klarna's network-distribution pricing documentation describes program-specific fixed and variable rates, with country, currency, merchant category and payment program among the pricing inputs. That partner documentation is not a universal direct-merchant rate card. Ask each provider or payment platform for the applicable merchant terms.
Calculate the Cost of a BNPL Offer
Use the formula: processing cost = captured sales x quoted percentage + captured transactions x quoted fixed fee. Then add the other contract charges and operating costs that apply. Keep currency, refund assumptions and the financing program identical across proposals.
For illustration only, 500 orders averaging $120 produce $60,000 in captured sales. A hypothetical quote of 4% + $0.30 would produce $2,550 in base transaction charges. This is not a Klarna or Affirm quote. Replacing those two inputs with your signed terms lets finance compare proposals without presenting estimated fees as published provider rates.
Klarna versus betalingen via Affirm : de belangrijkste verschillen
Both Klarna and Affirm support pay-over-time purchasing. Their merchant fit depends on the offered programs, eligible customers, integration route and operating arrangements. Compare the specific options shown for the same basket instead of assuming one is only short-term and the other only long-term.
- Payment options: evaluate the schedule and disclosures for representative order values.
- Availability: confirm the countries, currencies, products and channels you intend to support.
- Customer experience: review the checkout, payment reminders, cancellation and refund journey.
- Merchant operations: confirm capture, settlement, case handling and reporting access.
For a broader payment-stack decision, our payment gateway comparison explains how BNPL methods and processors fit together. For another installment option, see Klarna vs Afterpay and Affirm vs Afterpay.
Four Checkout Scenarios
Aansprakelijkheid bij terugboekingen bij BNPL: waarvoor zijn verkopers daadwerkelijk aansprakelijk?
Three different events get called disputes: an order or fulfillment dispute with the merchant, a borrower credit or repayment issue with the BNPL provider, and a card-network chargeback on the card that funds repayment. Provider financing does not mean every return, non-receipt claim or disputed purchase has the same outcome. Identify who is responsible for each event in your agreement and verify the workflow separately for each provider.
Klarna: The Klarna dispute documentation describes a dispute lifecycle with initiated, representment, pre-arbitration, arbitration and closed stages, handled through the Merchant Portal or by API file upload, with Klarna reviewing evidence and deciding. The process can depend on whether the transaction runs through a direct agreement or an acquiring partner. See the Klarna chargeback guide for operational context.
Affirm: Per Affirm dispute resolution, merchants typically have 15 days from notification, with reminders at 7 days and 1 day before the due date. If a dispute is resolved against the merchant, Affirm refunds the customer, the merchant reimburses Affirm, and a $15 dispute fee applies. Affirm notes that card-network processes can differ. See the Affirm disputes guide. In every case, follow the deadline in the actual notice and submit records that answer the stated reason. For response process, see chargeback management.
Klarna versus Affirm: welke BNPL-aanbieder past bij jouw afrekenproces?
Define the customer need first: payment flexibility for everyday purchases, financing for selected baskets or additional checkout choice. Ask both providers to demonstrate the same journey using your product categories and target market, and choose the arrangement that supports the customer experience and operating process you want to deliver. If you promote products through shoppable catalogs, keep the financing messaging consistent with what each checkout actually offers.
A merchant can evaluate offering both where the platform and agreements support it. Give each option a clear role and measure incremental completed orders, contribution margin, refunds, support contacts and disputes using comparable cohorts. Keep changes to promotions and traffic sources visible so the evaluation remains interpretable.
Hoe Chargeflow BNPL-verkopers Chargeflow

The Klarna integration and Affirm integration connect supported accounts to Chargeflow's dedicated dispute operations. Chargeflow Automation complements checkout and financing with automated recovery and evidence enrichment. Confirm the actual account connection and case coverage during implementation.
Keep orders, fulfillment, refunds and customer conversations linked to the payment reference. This supports a consistent response process across BNPL and other payment methods. Review Chargeflow's integration documentation and schedule a demo to map the workflow for your stack.
Veelgestelde vragen: Klarna versus Affirm
What is the difference between Klarna and Affirm?
They are separate providers with different markets, program mixes, eligibility decisions, merchant agreements and dispute workflows. Both offer Pay in 4 at 0% APR for eligible US purchases and longer financing in supported programs. Compare the actual offer for your market and basket instead of assuming the two are interchangeable.
Is Klarna or Affirm cheaper for merchants?
It depends on your agreement. Merchant fees come from your contract or your payment platform's pricing, and neither provider publishes a universal merchant rate card. Compare signed proposals on total economics: transaction charges, refunds, settlement and dispute costs.
Is Klarna or Affirm cheaper for shoppers?
Both advertise Pay in 4 at 0% APR for eligible US purchases when payments are made on time. Affirm's longer financing is disclosed at 0 to 36% APR depending on credit and the offer. Terms depend on the shopper and the purchase.
Do Klarna and Affirm both offer Pay in 4?
Yes, both advertise Pay in 4 for eligible US purchases. Check the specific checkout offer for eligibility, payment dates, disclosures and the total amount payable.
Does BNPL eliminate merchant disputes?
No. Financing does not remove order and fulfillment responsibilities. Merchants may still need to provide delivery, cancellation, refund or service records. For example, Affirm typically gives merchants 15 days to respond to a dispute, and Klarna disputes run through its Merchant Portal or API. Follow each provider's case instructions and your agreement.
Sources and Review Method
Reviewed October 5, 2026 against the primary sources linked beside the relevant claims, including the Federal Reserve's June 2026 BNPL note, Klarna's FY2025 results, Affirm's FY2026 Form 10-K and each provider's merchant dispute documentation. This comparison explains documented capabilities and business fit. The featured providers are Chargeflow partners. Examples are illustrative calculations, and workflow exercises are proposed evaluation methods, not claims of a controlled provider benchmark. Product availability and commercial terms depend on country, integration, plan and agreement.
Chargebacks?
Dat is niet langer jouw probleem.
Haal 4x meer chargebacks terug en voorkom tot 90% van de inkomende betalingen, dankzij AI en een wereldwijd netwerk van 20.000 handelaren.




