Contracargos?
Ya no es problema tuyo.
Recupera cuatro veces más Contracargos y prevención , hasta un 90 % de las entradas, gracias a IA y a una red global de 20 000 comercios.


 Más de 600 opiniones
En resumen:
- Confirm enrollment and eligibility before assuming alert coverage.
- Distinguish CDRN, RDR, and Ethoca resolution workflows.
- Reconcile existing refunds and report completed outcomes.
- Compare confirmed prevention results with total service and refund costs.


Chargeback alerts are notifications that support early resolution of eligible payment complaints before they become formal chargebacks. Alert handling combines transaction matching, a service-specific resolution action, and confirmation that the outcome was recorded.
Compare the Main Early Resolution Workflows
| Service | Cómo funciona | What You Must Confirm |
|---|---|---|
| Verifi CDRN | Merchant-initiated resolution of eligible Visa and non-Visa disputes; Verifi describes a 72-hour credit window | Enrollment, transaction match, timely credit, and outcome |
| Verifi RDR | Rule-based automatic resolution of eligible Visa disputes | Rule settings, eligible events, and reconciliation |
| Ethoca Alerts | Issuer fraud or dispute notifications followed by merchant action | Prompt action and outcome reporting; Ethoca states an objective within 24 hours |
These distinctions are documented by Verifi and Ethoca. Follow the specific event instructions. Parent-company ownership does not establish exclusive card-network coverage or universal issuer participation.
Separate Alerts From Other Dispute Signals
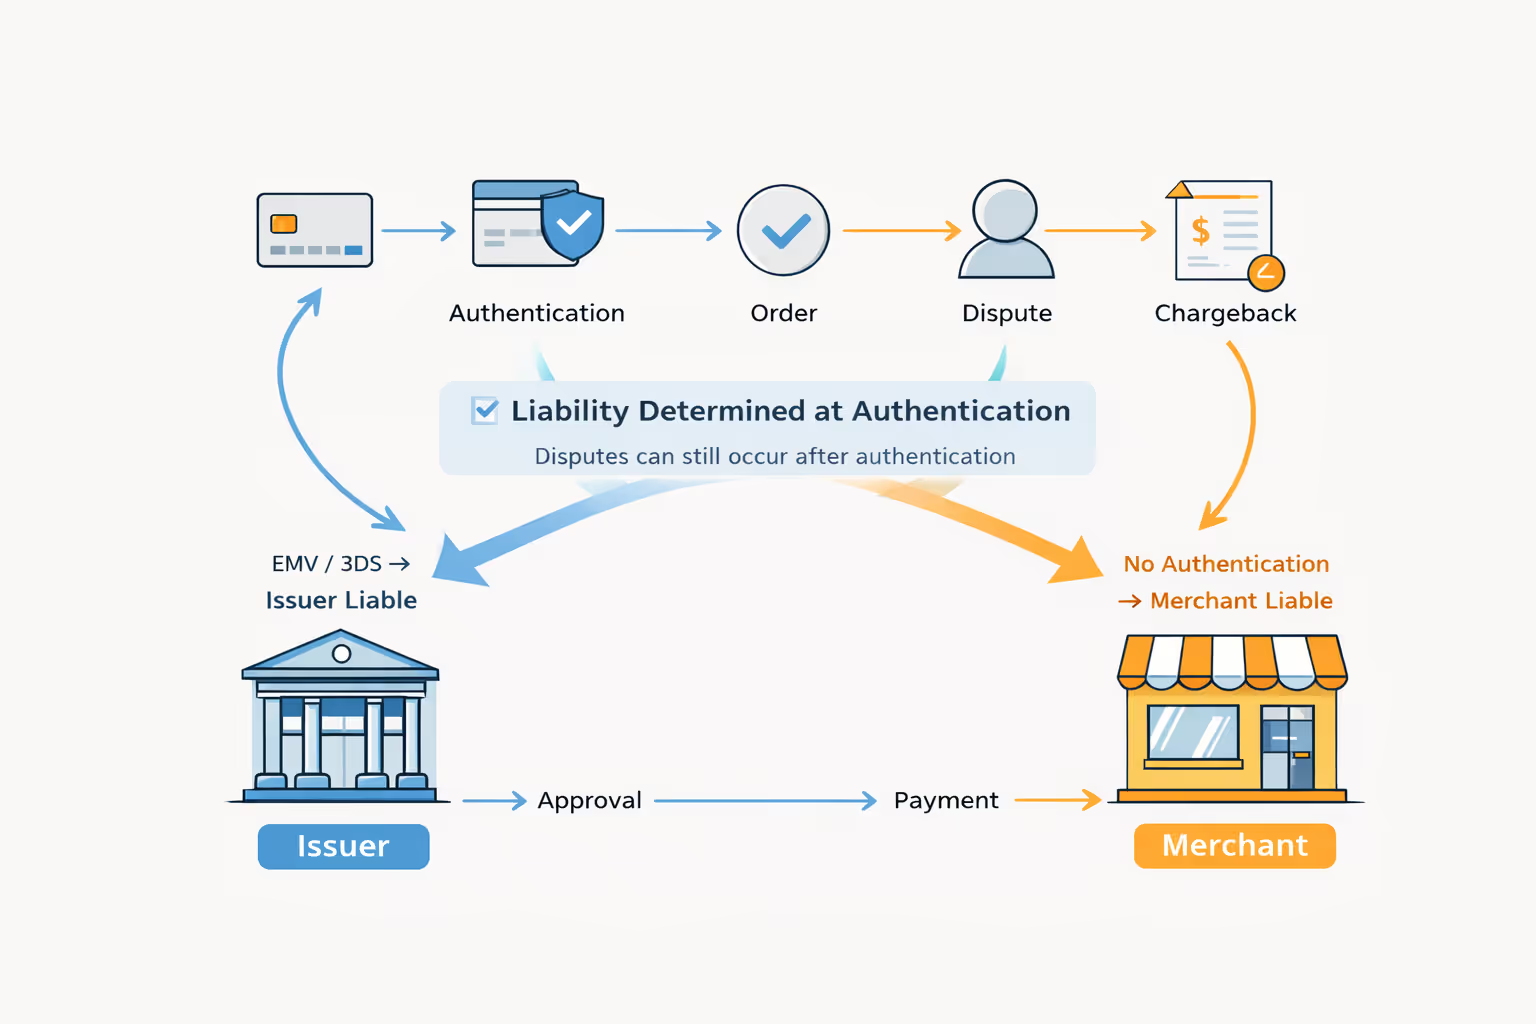
A fraud warning, an issuer inquiry, an alert, and a filed chargeback can require different actions. Transaction-detail services help customers recognize purchases. Alert-resolution services support eligible early resolutions. Filed chargebacks enter a response process with their own status and deadline.
Do not assume every inquiry proceeds through every alert service, or that a received alert means a chargeback was prevented. The alert response guide covers the operational steps, while the chargeback process guide explains the later dispute stage.
Set Up a Reliable Alert Workflow
- Confirm enrollment. Identify supported processors, merchant accounts, descriptors, and service coverage.
- Assign financial authority. Confirm which system may issue a refund or other supported resolution.
- Match the transaction. Reconcile payment reference, amount, currency, and descriptor.
- Check prior actions. Identify existing refunds, related notifications, or open disputes.
- Resolve and report. Complete the applicable action and send the required outcome.
- Monitor exceptions. Assign unmatched payments, failed refunds, and unconfirmed results to an owner.
For stores spanning multiple accounts, use the multi-processor operations guide. A connected account is only one checkpoint; you also need reliable action and outcome handling.
Prevent Duplicate Financial Actions
Keep alert, payment, refund, and dispute identifiers together. A retry should check whether the earlier action already succeeded before initiating another credit. Review partial refunds carefully because the remaining amount and the disputed amount may differ.
If a chargeback appears after a refund, investigate the timeline and follow the provider’s process. Do not automatically refund again. The refund and chargeback comparison explains why those financial events must be reconciled.
Compare Managed and Self-Managed Operations
| Operating Choice | Useful When | Control to Retain |
|---|---|---|
| Self-managed | Your team can reliably monitor and handle supported events | Ownership, timely action, and reconciliation |
| Managed or automated | Connected workflows can reduce repetitive handling | Exception visibility, permitted actions, and outcome reporting |
| Hybrid | Some transactions fit rules while others need review | Clear routing and one authoritative record of financial actions |
Choose based on actual workload and reliability rather than a universal alert-volume cutoff. Measure time spent, missed actions, duplicate credits, service costs, and confirmed outcomes. Avoid assuming that a particular workflow always saves a fixed number of minutes.
Evaluate Costs and Coverage Together
Pricing may depend on notifications, prevented chargebacks, or other contractual outcomes. Confirm service charges, refund costs, excluded transactions, and any enrollment requirements. A prevented chargeback is valuable, but its financial benefit depends on the order, the resolution, and the costs you actually avoid.
Connect alerts with broader prevention controls and dispute investigation. For cases that proceed, response automation supports evidence handling. You can explore Chargeflow Alerts for supported automated prevention workflows.
Preguntas frecuentes
Do chargeback alerts cover every transaction?
Chargeback alert coverage depends on enrollment, participating issuers, service support, and transaction eligibility. Confirm coverage for your merchant accounts and processors.
Is every alert a confirmed fraud case?
An alert can concern reported fraud or a customer dispute. The notification alone does not establish deliberate customer misuse.
Do all chargeback alerts have the same deadline?
Chargeback alerts do not all share one deadline. Follow the specific service and event instructions, and confirm the required action was completed.
Can a merchant automate chargeback alerts?
A merchant can automate supported alert workflows when transaction matching, action permissions, outcome reporting, and exception handling are configured. Automation still needs monitoring.
Contracargos?
Ya no es problema tuyo.
Recupera cuatro veces más Contracargos y prevención , hasta un 90 % de las entradas, gracias a IA y a una red global de 20 000 comercios.