Pre-Arbitration Chargeback: What It Is, How It Works, and How Merchants Can Fight and Win Them
rétrofacturation?
Ce n'est plus votre problème.
Récupérez 4 fois plus d'rétrofacturation s et PRÉVENTION jusqu'à 90 % des messages entrants, grâce à l'IA et à un réseau mondial de 20 000 commerçants.


 Plus de 600 avis
En bref :
- Pre-arbitration is a dispute-resolution stage before possible card-network arbitration.
- Its role differs across Visa Allocation, Visa Collaboration, and Mastercard workflows.
- Follow the deadline and response options in your processor’s case notice.
- Evaluate the evidence, permitted next steps, and current costs before continuing.


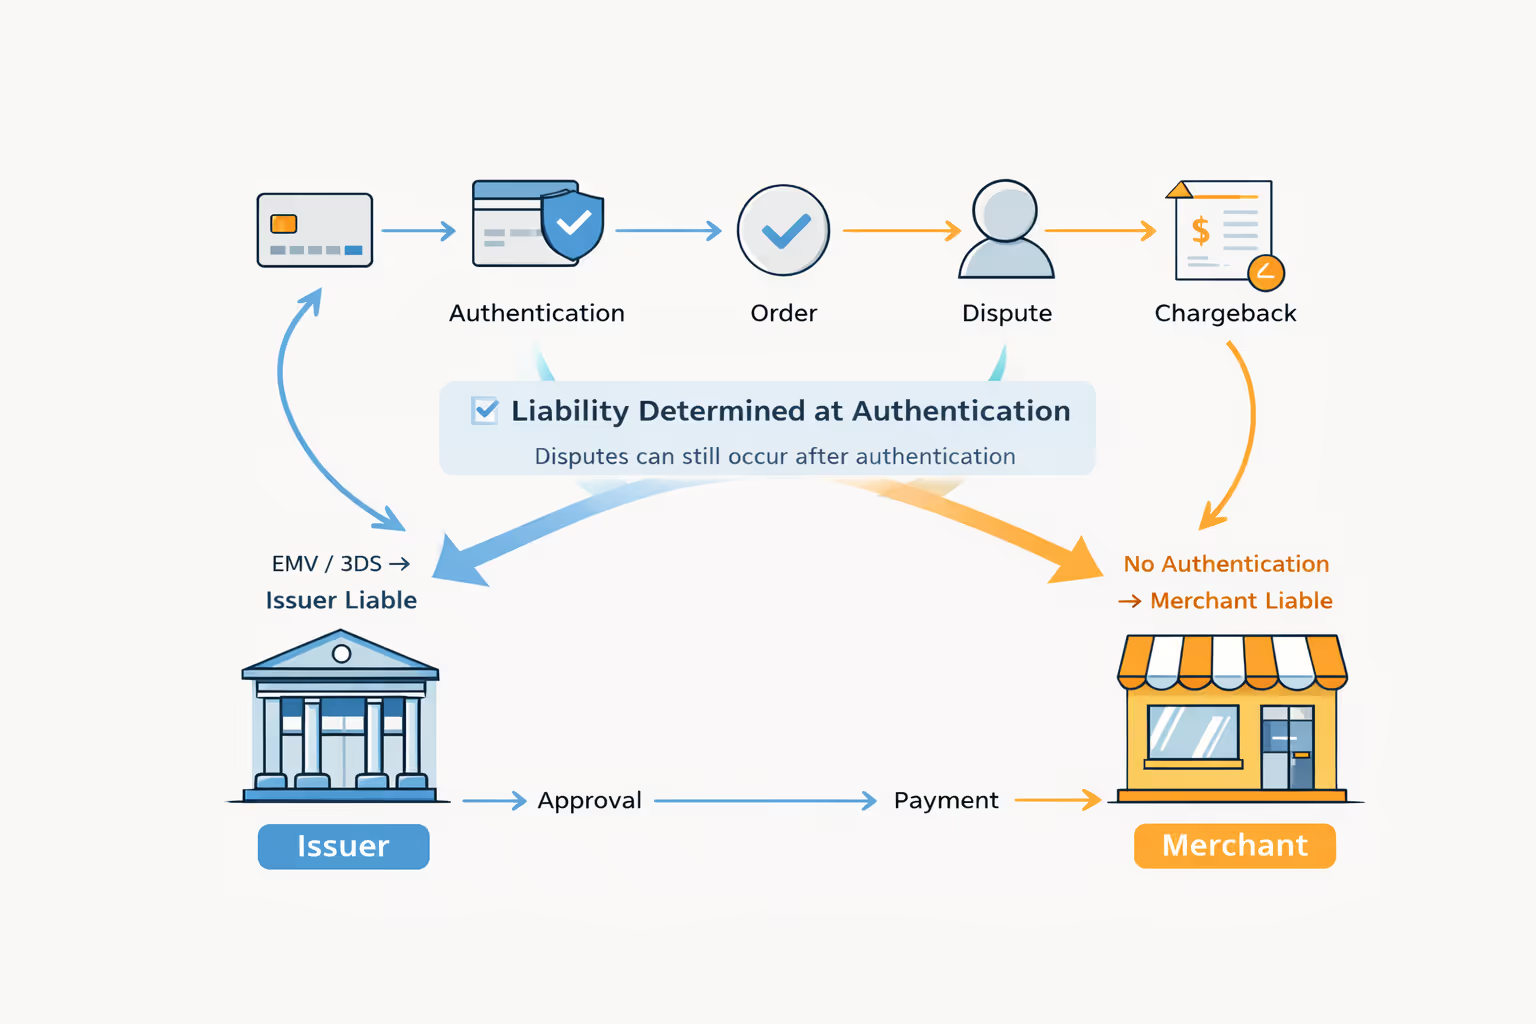
A pre-arbitration chargeback is a stage in which an issuer and acquirer seek to resolve a disputed payment before possible card-network arbitration. Its position in the process and the merchant’s response options depend on the network, dispute category, and payment provider.
Pre-arbitration does not always follow a merchant victory. Visa Allocation uses it as part of the merchant-side challenge to assigned liability, while other workflows can use it after an earlier response. Start with the chargeback process and representment guide for the surrounding stages.
{{cta}}
What Does Pre-Arbitration Mean?
Pre-arbitration (often shortened to “pre-arb”) is the last stage at which the cardholder’s bank and the merchant’s bank can settle a chargeback between themselves before asking the card network to rule. In most workflows it starts when the issuer rejects the merchant’s representment evidence and continues the dispute, although Visa Allocation cases use the pre-arbitration step as the merchant’s first formal challenge. If neither side accepts liability in pre-arbitration, the case can move to arbitration, where Visa or Mastercard makes a binding decision and charges the losing party a filing fee.
For the merchant, pre-arbitration means a second notice, a new deadline set by the processor, and a decision: accept the chargeback and stop, or respond with a rebuttal aimed at the issuer’s specific reason for continuing. The sections below cover how the stage differs by network, how to read the notice, and how to decide whether continuing is worth the cost.
Understand the Network Workflow
- Where Pre-Arbitration Fits
- The merchant-side defense is handled through a pre-arbitration challenge.
- What to Confirm
- Whether the transaction meets the permitted defense requirements.
- Where Pre-Arbitration Fits
- The issuer can continue the dispute after reviewing the merchant’s defense.
- What to Confirm
- The issuer’s reasoning and the provider’s options for accepting or declining.
- Where Pre-Arbitration Fits
- The issuer can escalate after the merchant’s defense; some categories bypass pre-arbitration.
- What to Confirm
- The reason code, available escalation route, and response requirements.
Adyen’s Visa workflow documentation distinguishes Allocation for fraud and authorization cases from Collaboration for consumer disputes and processing errors. Its Allocation process forwards the defense as pre-arbitration, while Collaboration allows an issuer challenge after the defense. This is why “pre-arbitration always reopens a case you already won” is not a reliable definition.
The Mastercard workflow documented by Adyen also distinguishes pre-arbitration from later escalation. It identifies reason codes 4808, 4870, and 4871 as going directly to scheme arbitration if escalated. These provider documents explain their supported processes; confirm the handling of your own account.
Read the Notice Before Choosing a Response
Create a short case brief before deciding whether to accept liability or continue. It should contain:
- Case identifiers and current stage
The transaction and dispute identifiers, amount, currency, and current stage.
- Reason and continuing objection
The reason code and the issuer’s stated basis for continuing.
- Evidence already supplied
The evidence already submitted and the point each document supports.
- Deadline, channel, and owner
The deadline, permitted response method, and responsible team member.
- Current funds and added exposure
The funds currently debited or credited and any additional cost exposure.
Do not infer the stage from a balance movement alone. Adyen’s Mastercard documentation notes that a chargeback reversal can occur while the issuer is still reviewing the defense. Reconcile the case status with the settlement record before treating recovered funds as final.
Use the Case Deadline, Not a Generic Window
A network filing window is not automatically your merchant response deadline. Your processor or acquirer may need time to review and transmit the response. Record the date shown in the case and confirm any separate escalation cutoff with the team handling it.
Ask what happens if no response is submitted. Some workflows accept a pre-arbitration case when the response period expires, as described in Adyen’s guidance. Do not rely on silence as a deliberate resolution instruction. See chargeback time limits for the distinction between filing, response, and review periods.
Address the Specific Reason for Escalation
Use the current case and provider requirements
Answer the continuing objection with relevant evidence
Explain the unresolved point
A useful rebuttal explains why the issuer’s continuing claim is unsupported under the applicable requirements. Refer to the existing evidence by document and page, and explain how it answers the disputed point. If a record was previously unavailable, ask whether the current stage permits its submission.
Connect the record to the allegation
For example, if the issue is a missing refund, identify the refund reference and amount. If the issue is non-delivery, connect the fulfillment record to the order and destination. Repeating an order receipt without explaining its relevance may leave the disputed fact unanswered.
Do not assume that later stages provide an unrestricted opportunity to add evidence. Our evidence-review guide distinguishes submission problems from an unfavorable decision. The follow-up evidence checklist helps organize additional requests.
Compare Pre-Arbitration With Arbitration
| Question | Phase préalable à l'arbitrage | Arbitrage |
|---|---|---|
| Who handles the disagreement? | The issuer and acquirer work through the applicable dispute process. | The card network reviews the escalated case. |
| Is escalation automatic? | No. Available actions depend on the case and provider. | Network escalation requires the applicable process and eligibility. |
| What costs apply? | Check existing and stage-specific fees with your provider. | Confirm filing, review, potential liability, and provider charges. |
| Can more evidence be added? | Only as permitted by the current stage and rules. | Do not assume the record can be expanded. |
There is no single all-in arbitration price for every network, provider, and case. Obtain a current cost breakdown before authorizing escalation. Our chargeback arbitration guide provides further context.
Decide Whether Continuing Is Justified
Evaluate the merits first: can your records answer the issuer’s argument, and does the applicable rule support the defense? Then assess the disputed amount, remaining work, additional fees, and possible loss. Avoid treating an earlier credit as proof that another challenge will succeed.
Document the decision and assign an owner to carry it out. When the complaint is substantiated or the remaining defense is insufficient, accepting liability may be appropriate. When a supported challenge is available, submit it through the provider’s approved process and confirm receipt.
You can explore Chargeflow’s chargeback recovery workflow to improve evidence preparation earlier in the dispute process.
Review the continuing objection before escalating
Use a short objection-to-record worksheet: copy the issuer’s continuing allegation, identify the earlier response exhibit it challenges, and record whether a permitted correction or additional record directly addresses that point. Do not assume another upload is available or that repeating the original packet answers a new objection.
| Review field | Decision it supports |
|---|---|
| Current network, stage, and due date | Whether this is a pre-arbitration response or another case type. |
| Continuing allegation and earlier exhibit | What remains unresolved. |
| Permitted material and provider route | Whether a relevant response can be submitted. |
| Current itemized exposure | Whether escalation is operationally and financially justified. |
Keep the earlier representment record and the arbitration cost decision separate.
Continue learning: Evidence and escalation
Use Chargeback Evidence and Escalation: Choose Your Next Step to choose the next merchant task in this topic.
- Chargeback Reason Codes: Network Examples and Evidence: Reason-code interpretation and routes to claim-specific evidence.
- What Is Chargeback Representment? Definition and Process: Merchant evidence submissions and the decision to counter a dispute.
Sources and scope
Source notes updated: October 11, 2026. Network escalation. Ask the acquirer whether this case can proceed, which rule edition applies, and what costs are incremental. Provider access differs: Stripe does not support arbitration through its platform. Training-example amounts in this guide are illustrative.
- Visa: current public rules and editions
- Mastercard: rules and chargeback documents
- Stripe: lifecycle and arbitration availability
For a live case, retain the governing document’s edition or effective date, the relevant provision, and the provider notice.
Foire aux questions
Does Pre-Arbitration Always Follow a Won Representment?
Pre-arbitration does not always follow a won representment. Visa Allocation uses pre-arbitration within the merchant-side liability challenge, while other workflows can use it after review of an earlier defense.
Can Every Merchant Proceed to Arbitration?
Arbitration access depends on the payment provider, case eligibility, and network rules. Confirm the supported options and costs with your processor or acquirer before planning an escalation.
Should I Resubmit the Original Evidence Package?
A pre-arbitration response should address the continuing allegation and reference the relevant records. Confirm whether additional evidence is permitted instead of assuming the original package can simply be replaced.
Does Accepting Pre-Arbitration Remove Earlier Fees?
Accepting a pre-arbitration case does not necessarily remove fees already incurred. Confirm the financial outcome and any remaining charges with your provider.

rétrofacturation?
Ce n'est plus votre problème.
Récupérez 4 fois plus d'rétrofacturation s et PRÉVENTION jusqu'à 90 % des messages entrants, grâce à l'IA et à un réseau mondial de 20 000 commerçants.