How Finance and Risk Teams Prioritize Friendly Fraud Differently

Contracargos?
Ya no es problema tuyo.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000+ merchants.


 Más de 600 opiniones


En resumen:
- Risk and fraud leaders rank friendly fraud the top cause of rising chargebacks, while finance leaders rank it last of five.
- 43% of 121 US and UK enterprises believe friendly fraud is over 25% of their chargebacks, and 11% think it is over half.
- Overall, stolen-card fraud (24%), rule confusion (23%) and friendly fraud (22%) were near-tied as the top cause.
- Different records, timing and labels can explain the gap, so build one shared case record before assigning blame.
- Billing failures and valid complaints are not friendly fraud and need a refund or fix, not a fight.
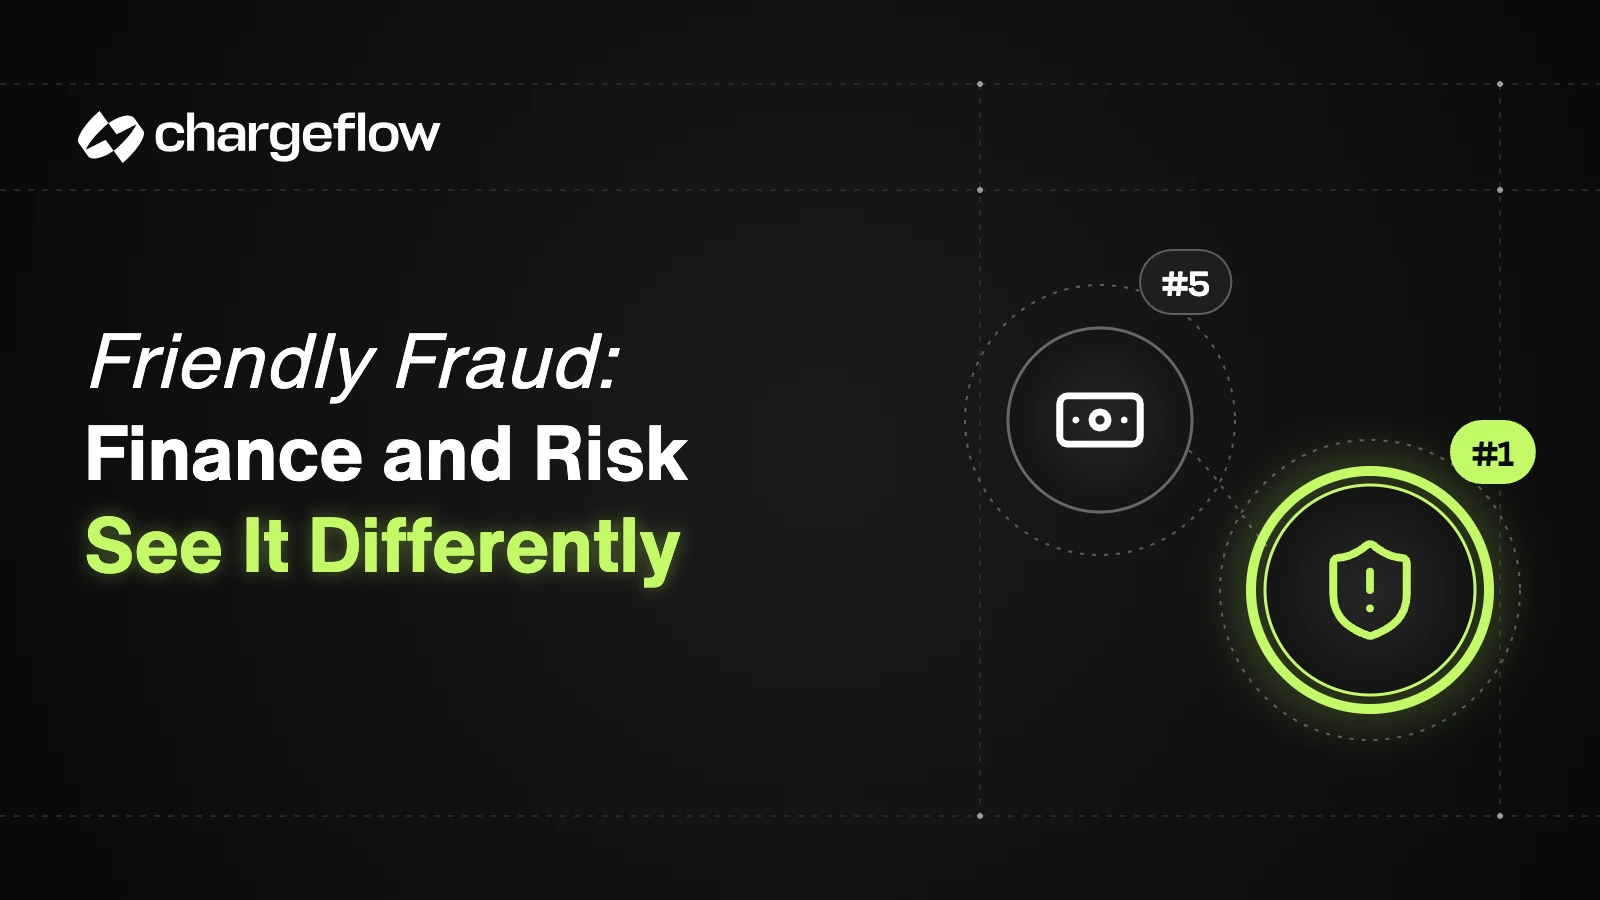
Finance and risk teams rank friendly fraud very differently. In a 2026 survey of US and UK enterprises, risk and fraud leaders ranked it the top driver of rising chargebacks. Finance leaders ranked it last of five. The gap is a sign to check how each team counts and labels cases.
#1 friendly fraud rank among risk/fraud leaders | #5 friendly fraud rank among finance leaders | 43% think friendly fraud is over 25% of their chargebacks |
Source: Juniper Research and Chargeflow, The State of Chargeback Management, September 2026. Rankings: n=79 respondents whose chargebacks rose. Share: n=121.
{{cta}}
How Do Finance and Risk Rank Friendly Fraud?
The survey asked leaders whose chargebacks had risen to rank five possible causes. Each department put them in a different order. Risk teams put friendly fraud first and fraud from stolen cards fourth. Finance and customer relations put stolen-card fraud first.
Table 5, Q12 by department (Q6). Rank 1 is most important. n=79 respondents who reported rising chargebacks.
Across all 79 respondents, the top picks were close: stolen-card fraud (24%), rule confusion (23%) and friendly fraud (22%). No single cause dominates the overall view. The split only shows up by department.
These are ranks of perceived causes. They do not measure how many disputes were friendly fraud. Read them as a signal about each team's view, not as proof of what drives the volume.
How Much of Their Chargebacks Do Enterprises Think Is Friendly Fraud?
A lot. 43% of respondents believe friendly fraud is more than a quarter of their chargebacks, and 11% think it is over half.
Figure 6, Q15, n=121. Respondent estimates, not measured case counts.
Separate Juniper Research data puts the value of transactions lost to friendly fraud at $8.1 billion in 2026, or 22% of chargebacks. It forecasts nearly $16 billion by 2031, a 96% rise. Estimates inside companies sit close to that market view, but vary widely between them.
Country matters too. More UK respondents than US respondents reported rising chargebacks, 78% against 59%. See US vs UK enterprise chargeback trends for the regional view.
Why Might Finance and Risk See Friendly Fraud Differently?
The survey shows the gap but does not test its cause. Four common reasons are worth checking inside your business:
Editorial checklist, not survey findings.
The sample itself leaned toward finance: 53% of respondents worked in finance, 26% in risk or fraud and 17% in customer relations. So the all-respondent view mostly reflects finance priorities.
Customer relations sees a third angle: unresolved delivery and cancellation complaints. The support and payments collaboration guide covers that handoff.
What Counts as Friendly Fraud and What Does Not?
Friendly fraud is a dispute on a real purchase that the cardholder made or approved. It is not the same as stolen-card fraud or a valid complaint about a merchant mistake. Mixing these up is the most common reason teams disagree.
For deeper definitions, see friendly fraud vs stolen-card fraud vs return abuse and first-party fraud.
How Can Finance and Risk Review Cases Together?
Use one shared case record. Each team adds its facts to the same file, and the label comes last.
- Pick one group of cases, such as all disputes received in one month on one processor.
- Keep the original claim: amount, reason code, card network and date.
- Join the evidence record (orders, delivery, logins, support) to the money record (credits, fees, refunds).
- Label each case only from the evidence, and keep suspected and confirmed abuse in separate fields.
- Assign one corrective action: fight, refund, fix a process or tighten screening.
The evidence source map shows where each fact should come from. The finance reporting and reconciliation guide covers the money side.
Which Card Network Rules Help With Friendly Fraud?
Two network programs let merchants use identity and device data against fraud claims on genuine purchases. Both reward the shared record above, because the data must match across sales.
Eligibility, regions and processor support differ. See Visa CE3.0 vs Mastercard First-Party Trust before you plan around either one.
Example: One Cancellation Dispute, Two Views
This case is made up to show the review process. It is not a Chargeflow customer outcome.
A subscriber disputes an $80 renewal. Risk flags the account because it has one earlier dispute. Finance logs the case as an unrecovered chargeback. Neither view says whether this renewal was correct.
The shared record shows a cancellation request before the renewal and a support reply confirming billing would stop. That points to a billing failure, not friendly fraud. The right move is a refund and a fix to the cancellation flow.
Now change one fact: the cancellation came after the renewal, and usage logs cover the billed period. That is a different evidence set, and fighting may make sense. See cancelled subscription chargeback rules and when to fight a chargeback.
What Should a Shared Friendly Fraud Dashboard Show?
Track whether alignment improves decisions, not just whether the teams agree:
- Evidence: share of cases with a complete record before the deadline.
- Labels: share of suspected friendly fraud later confirmed by evidence.
- Money: recovered funds and fees for each label.
- Actions: process fixes made after billing failures or merchant errors.
Friendly fraud estimates also shape tooling. In the same survey, 80% of enterprises use AI in chargeback management, but only 11% run mostly automated processes. See enterprise chargeback automation maturity for where automation helps classification.
Turn Shared Classification Into the Right Response
When both teams read the same record, each case goes to the right path: fight, refund, fix or screen. Chargeflow Insights shows dispute trends by reason, processor and outcome, so finance and risk can work from one view.
{{cta}}
Preguntas frecuentes
Do finance and risk teams see friendly fraud differently?
Yes. In a September 2026 survey of US and UK enterprises, risk and fraud leaders ranked friendly fraud first among five causes of rising chargebacks. Finance leaders ranked it fifth.
What share of chargebacks is friendly fraud?
Estimates vary. 43% of surveyed enterprises believe it is more than 25% of their chargebacks, and 11% think it is over half. Juniper Research puts it at 22% of chargebacks in 2026.
Does the survey prove finance underestimates friendly fraud?
No. It shows different rankings, not which team is right. Check each team's records, timing and labels before you decide.
Is every dispute on a real purchase friendly fraud?
No. Billing failures, late refunds and valid complaints also produce disputes on real purchases. Those need a refund or a process fix, not a fight.
What should teams share when reviewing a friendly fraud case?
The original claim, the order and delivery records, account and device history, support contacts, and the money record of credits, fees and refunds.
Sources and Survey Methodology
Findings come from The State of Chargeback Management: How AI Is Reshaping Performance, by Juniper Research with Chargeflow. Juniper Research surveyed 121 C-level executives and senior managers in September 2026: 80 in the US and 41 in the UK. All worked at businesses with at least $100 million in yearly gross merchandise value.
- Figure 4 and Table 5, Q12: drivers of rising chargebacks, overall and by department, n=79.
- Figure 6, Q15: believed share of friendly fraud, n=121.
- Survey methodology: department mix, n=121.
The friendly fraud market figures are separate Juniper Research estimates cited in the report. The reason checklist, case types, review steps and example are Chargeflow editorial guidance, not survey findings.
The State of Chargeback Management
Read the full Juniper Research survey of 121 enterprises: AI results, win rates, costs and what buyers expect.
Contracargos?
Ya no es problema tuyo.
Recupera cuatro veces más Contracargos y prevención , hasta un 90 % de las entradas, gracias a IA y a una red global de 20 000 comercios.