


































































Klarna vs. Affirm: Plans, Merchant Costs and Disputes

Chargebacks?
Não é mais problema seu.
Recupere 4 vezes mais chargebacks e PREVENÇÃO — até 90% dos e-mails recebidos —, com tecnologia de IA e uma rede global Rede de 20.000 Lojistas.


 Mais de 600 avaliações


Resumo:
- Klarna and Affirm are separate public companies: Klarna trades on the NYSE (KLAR) and Affirm on Nasdaq (AFRM).
- Each offers 0% APR Pay in 4 to eligible US shoppers, plus longer financing in supported programs.
- Federal Reserve data for 2025 shows 90% of Klarna's US loans at 0% APR versus 29% for Affirm, whose volume skews to longer terms.
- Merchant fees come from your own agreement or payment platform, so compare signed proposals rather than shopper rates.
- Affirm usually allows merchants 15 days to answer a dispute, while Klarna cases run through its Merchant Portal or API.
Klarna and Affirm are buy now, pay later (BNPL) providers that let eligible shoppers split the cost of a purchase. You get paid under your payment agreement. Both offer short-term installment plans and longer financing in supported programs. Compare the plans your customers see, your costs and what happens after the sale.
This guide keeps shopper terms apart from merchant duties. Examples labeled US are US consumer terms. Company metrics carry their own period and region. To see Afterpay and Sezzle next to these two, use the BNPL provider comparison. For market data, see BNPL market statistics.
Short answer: Both offer Pay in 4 at 0% APR for eligible US purchases. Both also offer longer financing in supported programs. They differ in markets, program mix, merchant agreements and dispute workflows. So the right fit depends on your checkout, customers and integration, not on company size. For what each provider asks for in a case, see our guide to BNPL dispute evidence.
Are they the same company? No. Klarna Group plc is based in Stockholm, Sweden, and trades on the NYSE. Affirm Holdings is based in San Francisco and trades on Nasdaq. Each runs its own lending, checkout and dispute process.
{{cta}}
How Klarna and Affirm Payment Plans Work for Shoppers
Shopper plans decide what your customers see at checkout. These are consumer terms (US examples), not merchant processing rates.
- Pay in 4: Both advertise four payments at 0% APR for eligible US purchases. Klarna says later payments are collected every 14 days (Klarna US Pay in 4). Affirm states Pay in 4 is offered at 0% APR (Affirm US business disclosures).
- Longer financing: Affirm discloses longer financing at 0 to 36% APR, based on credit and the offer. Terms run up to 5 years, per the Federal Reserve FEDS Notes, June 2026. Klarna lists other payment and financing options by market and eligibility.
- Eligibility: Offers depend on the shopper, purchase and program. Check what shows up for your own baskets.
Klarna x Affirm: Comparação lado a lado (2026)
Open a section to compare the details.
Company and Listing
- Klarna
- Klarna Group plc, headquartered in Stockholm, Sweden. Listed on the NYSE as KLAR. Klarna FY2025 results.
- Affirm
- Affirm Holdings, Inc., headquartered in San Francisco, California. Listed on Nasdaq as AFRM. Affirm FY2026 Form 10-K.
US BNPL Issuance, 2025 (Federal Reserve, US only)
- Klarna
- $23.9 billion, 15% of the $156.7 billion US total. Source: Federal Reserve FEDS Notes, June 2026.
- Affirm
- $41.3 billion, 26% of the US total. Same source and period.
Reported Scale (company-reported, global; periods differ)
- Klarna
- FY2025 (ended Dec 31, 2025): $127.9 billion GMV, $3.5 billion revenue, 118 million active consumers, 966,000 merchants. Klarna FY2025 results.
- Affirm
- FY2026 (ended Jun 30, 2026): $50.2 billion GMV and about 571,000 active merchants. Affirm FY2026 Form 10-K. Fiscal periods differ, so read these as scale, not a same-period comparison.
Shopper Product and Market (US examples)
- Klarna
- Pay in 4 at 0% APR for eligible US purchases; other payment or financing programs depend on market and eligibility. Klarna US Pay in 4.
- Affirm
- Pay in 4 at 0% APR; longer financing disclosed at 0 to 36% APR with terms up to 5 years. Affirm US business disclosures; Federal Reserve FEDS Notes, June 2026.
Shopper Approval Check
- Klarna
- Most plans use a soft credit check, which does not affect the shopper's credit score.
- Affirm
- Most plans use a soft credit check, which does not affect the shopper's credit score. Source for both: Federal Reserve FEDS Notes, June 2026.
Merchant Pricing Basis
- Klarna
- Your direct agreement or the pricing of the PSP through which you offer Klarna.
- Affirm
- Your Affirm proposal or the pricing of the platform through which you offer Affirm.
Merchant Settlement
- Klarna
- Confirm capture, payout timing, fees, refunds and adjustments for the actual integration.
- Affirm
- Confirm capture, payout timing, fees, refunds and adjustments for the actual integration.
Refund Workflow
- Klarna
- Process refunds through the integration you use and confirm how fees on refunded orders are treated.
- Affirm
- Process refunds through the integration you use and confirm how fees on refunded orders are treated.
Dispute and Evidence Process
- Klarna
- Merchant Portal or API with PDF uploads, through the direct or PSP arrangement. Klarna dispute documentation. Direct US agreements carry a $15 fee only when a case closes against the merchant (Klarna dispute fees).
- Affirm
- Affirm notifies the merchant and requests evidence, typically with 15 days to respond. A $15 US fee applies only when a case is resolved for the customer. Affirm dispute resolution.
Klarna vs Affirm by the Numbers: 2025 US Loan Mix
The Federal Reserve split each provider's 2025 US lending by loan type and by cost. One source and one period cover both. So this is a like-for-like view. The authors used public filings. Where a firm gave only global totals, they scaled them by its US share.
| 2025 US Loan Volume | Klarna | Affirm |
|---|---|---|
| Pague em 4 parcelas | $7.0 billion (29%) | $6.3 billion (15%) |
| Short-term loans | $7.5 billion (31%) | Not reported as a separate type |
| Longer-term loans | $9.4 billion (39%) | $35.0 billion (85%) |
| Issued at 0% APR | $21.5 billion (90%) | $12.2 billion (29%) |
| Total US issuance | $23.9 billion | $41.3 billion |
What the mix tells you: Klarna's US volume leans toward short, interest-free plans. Affirm's leans toward longer-term financing, with most of it carrying interest. Both still offer Pay in 4 and longer terms. So use the mix as a hint about typical checkout use, then test the offers your own baskets receive.
Visão geral e principais recursos do Klarna
Klarna pairs payment options with a shopper experience. It can support discovery, checkout and order management after the sale. For you, the key question is which programs are turned on for the country, channel and integration you plan to launch. Judge a direct connection and one routed through a payment service provider each on its own terms.
Como funciona o Klarna? Principais recursos
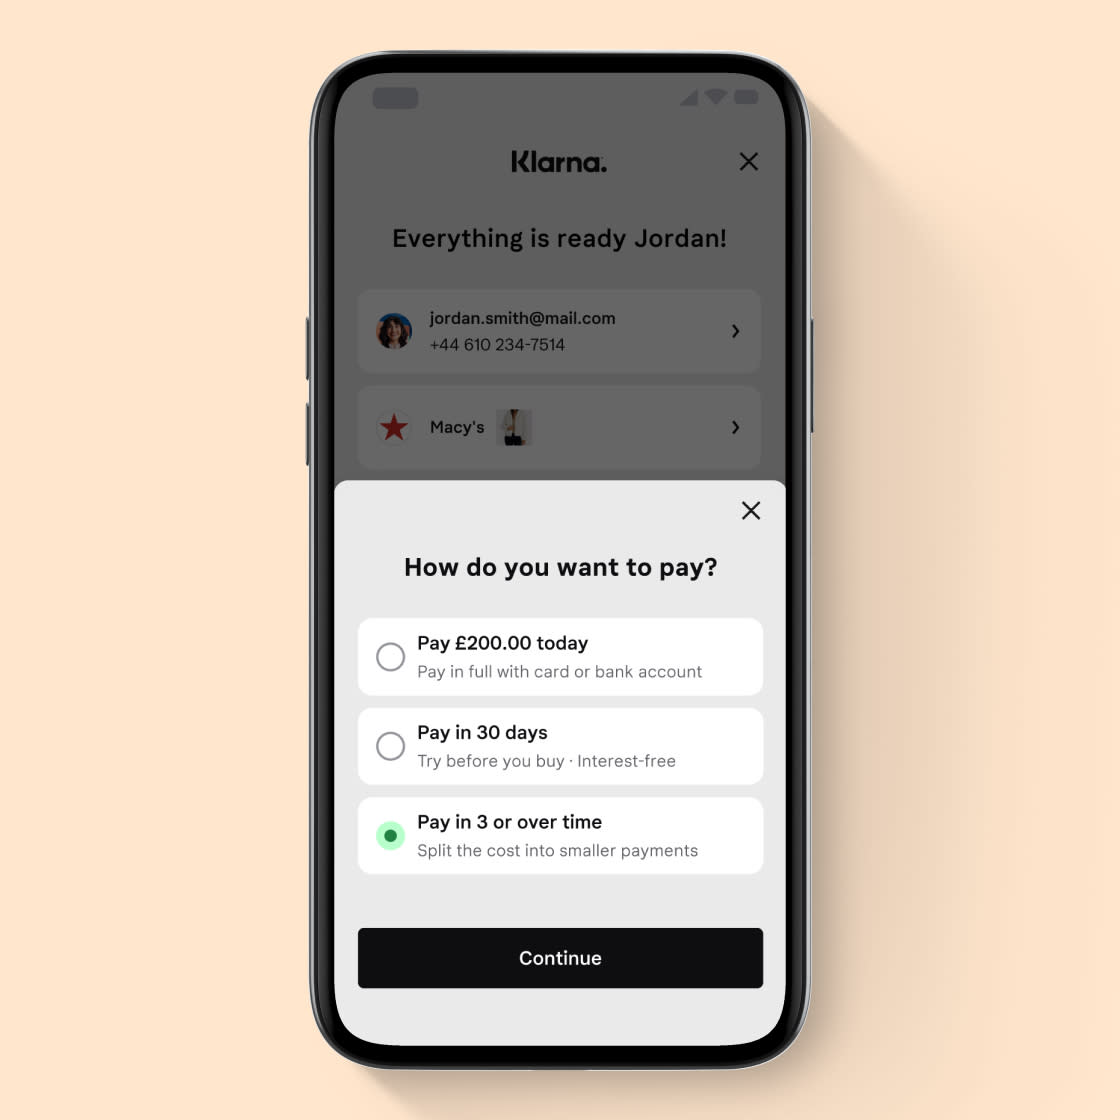
With US Klarna Pay in 4, eligible shoppers split a purchase into four interest-free payments. Klarna says it collects later payments every 14 days. Its US payment info also lists other options. One is monthly financing for eligible purchases. See the current Klarna plan details for the payment schedule and disclosures.
Keep shopper messages in sync with the program offered at checkout. Record the order lines, payment method, capture status, shipping events and refunds. These records give your support and payments teams a shared view of the purchase. If you refund part of an order while a case is open, see partial refunds during a BNPL dispute. The Klarna integration connects supported accounts to Chargeflow.
Affirm Visão geral e recursos em resumo
Affirm gives merchants an installment payment option. It can be matched to purchase amount, customer eligibility and the financing program on offer. Its business offering covers online and omnichannel use cases. Check the checkout display and financing terms that will apply to your products.
Affirm Principais recursos

Affirm's US disclosures state that Pay in 4 is offered at 0% APR. Other financing can range from 0 to 36% APR based on credit and eligibility. Payment options vary by merchant and purchase. A down payment may apply.
These are shopper financing terms, not your processing rate. Source: Affirm US business disclosures. The Affirm integration connects supported accounts to Chargeflow.
For high-value purchases or a catalog with mixed order sizes, test the payment options shown for typical baskets. Walk through the full payment journey: capture, refund, customer support and reconciliation. This shows your team how it fits day to day, not just at checkout.
Taxas da Klarna x Taxas da Affirm : a análise completa
Merchant fees for Klarna and Affirm depend on the pricing schedule for the product and integration you use. Three costs are easy to mix up. Keep them in separate columns of your model:
- A shopper's interest rate
- A promo financing offer
- A PSP's published processing rate
Klarna's network-distribution pricing documentation lists fixed and variable rates by program. Rates depend on country, currency, merchant category and payment program. That partner doc is not a universal rate card for direct merchants. Ask each provider or payment platform for the terms that apply to you. Then fill in the same worksheet for both proposals:
| Cost Input | What to Record for Both Providers | Por que isso é importante |
|---|---|---|
| Transaction Charges | Percentage fee, fixed fee, payment program, currency and channel. | Makes the processing calculation reproducible. |
| Financing Offers | Who funds any merchant-sponsored promotion and which orders qualify. | Connects the offer to its commercial scope. |
| Settlement | Capture rules, payout schedule, deductions and reconciliation references. | Explains when and how proceeds reach your business. |
| Refunds and Disputes | Refunded-fee treatment, case charges, evidence requirements and adjustments. | Connects checkout economics to post-purchase operations. |
| Implementation | Platform fees, engineering, reporting and customer-support ownership. | Produces a complete operating budget. |
Calculate the Cost of a BNPL Offer
Use this formula: processing cost = captured sales x quoted percentage + captured transactions x quoted fixed fee. Then add any other contract charges and operating costs. Keep currency, refund assumptions and the financing program the same across proposals.
For illustration only: 500 orders averaging $120 produce $60,000 in captured sales. A hypothetical quote of 4% + $0.30 would produce $2,550 in base transaction charges. This is not a Klarna or Affirm quote. Swap those two inputs for your signed terms. Finance can then compare proposals without treating estimated fees as published provider rates.
Klarna x Pagamentos do Affirm : as principais diferenças
Both Klarna and Affirm let shoppers pay over time. Which one fits depends on the programs offered, eligible customers, integration route and how you operate. Compare the options shown for the same basket. Do not assume one is only short-term and the other only long-term.
- Payment options: check the schedule and disclosures for typical order sizes.
- Availability: confirm the countries, currencies, products and channels you plan to support.
- Customer experience: review checkout, payment reminders, cancellation and refunds.
- Merchant operations: confirm capture, settlement, case handling and report access.
For a broader payment-stack choice, our payment gateway comparison shows how BNPL methods and processors fit together. For another installment option, see Klarna vs Afterpay and Affirm vs Afterpay.
Four Checkout Scenarios
Test each scenario with both providers. No preferred provider is assumed.
| Cenário | What the Shopper Needs | What to Compare |
|---|---|---|
| Everyday basket under a few hundred dollars | A short, low-cost way to split the payment | Pay in 4 eligibility, payment schedule, reminders and refund handling |
| High-ticket purchase | A longer repayment term with clear total cost | Available terms and APR ranges for your price points, plus merchant fees for those programs |
| Cross-border catalog | Familiar payment options in each market | Country and currency availability under your agreement, and PSP support |
| Subscription or split shipment | Clear charges that follow fulfillment | Capture rules, partial refunds, cancellations and how disputes reference each shipment |
{{cta}}
Responsabilidade do BNPL Chargeback : O que os Lojistas realmente têm que arcar
Three different events get called disputes:
- An order or fulfillment dispute with the merchant
- A borrower credit or repayment issue with the BNPL provider
- A card-network chargeback on the card that funds repayment
Only the last one follows card-network rules. If you need a refresher, start with what is a chargeback. To pick the right route for a case, see wallet and BNPL disputes.
Provider financing does not mean every return, non-receipt claim or disputed purchase has the same outcome. Check who is responsible for each event in your agreement. Then verify the workflow separately for each provider.
Some claims are friendly fraud, where a shopper disputes an order that arrived as described. For installment-specific risks, see our guide to buy now, pay later fraud.
Klarna: The Klarna dispute documentation describes these dispute stages: initiated, representment, pre-arbitration, arbitration and closed. Cases are handled through the Merchant Portal or by API file upload. Klarna reviews the evidence and decides. The process can depend on whether the transaction runs through a direct agreement or an acquiring partner. See the Klarna chargeback guide for operational context.
For direct US agreements, Klarna charges a $15 dispute fee only when a case closes against the merchant. If you use a PSP, it may pass that fee through. To trace that fee and any held amounts in your payouts, see Klarna dispute reconciliation.
Affirm: Per Affirm dispute resolution, merchants typically have 15 days from notice. Affirm sends reminders 7 days and 1 day before the due date. If a dispute is resolved against the merchant, Affirm refunds the customer. The merchant then pays Affirm back. A $15 dispute fee also applies. Affirm notes card-network processes can differ.
See the Affirm disputes guide. In every case, follow the deadline in the actual notice. Submit records that answer the stated reason. For the response process, see chargeback management.
| Customer Question | Useful Merchant Records | Operational Check |
|---|---|---|
| Where Is My Order? | Order confirmation, carrier tracking, delivery evidence and customer messages. | Connect the provider transaction to the fulfilled order. |
| Was My Order Canceled? | Cancellation request, policy acceptance, refund record and timestamps. | Reconcile the cancellation with capture and refund events. |
| Did I Receive the Agreed Product or Service? | Product description, order lines, service records and support correspondence. | Answer the actual dispute reason with relevant evidence. |
Klarna x Affirm: qual provedor de BNPL é o mais adequado para o seu processo de finalização de compra
Define the customer need first. Is it payment flexibility for everyday purchases? Financing for selected baskets? Or more checkout choice? Ask both providers to demo the same journey with your product types and target market. Then pick the setup that fits the customer experience and operating process you want.
Use this side-by-side as a starting point, not a verdict. Many merchants fit both columns.
Open a section to compare the details.
Most baskets suit a short, interest-free split. 90% of Klarna's 2025 US volume was issued at 0% APR.
- Choose Affirm When
- Many baskets are high-ticket and need longer terms. 85% of Affirm's 2025 US volume was longer-term loans.
You want shoppers to see several short options, such as Pay in 4 and other short-term loans.
- Choose Affirm When
- You want shoppers to see financing of up to 5 years, with APRs disclosed from 0 to 36%.
Your PSP or platform already supports Klarna, so setup runs through an existing integration.
- Choose Affirm When
- Your PSP or platform already supports Affirm, so setup runs through an existing integration.
If you promote products through shoppable catalogs, keep the financing messages in line with what each checkout actually offers.
You can test offering both if your platform and agreements allow it. Give each option a clear role. Then measure these with comparable cohorts:
- Incremental completed orders
- Contribution margin
- Reembolsos
- Support contacts
- disputas
Keep changes to promotions and traffic sources visible so the results stay clear. Before you launch either option, confirm current terms, fees and dispute rules with each provider.
Como o “ Chargeflow ” oferece suporte ao BNPL Lojistas

The Klarna integration and Affirm integration connect supported accounts to Chargeflow's dedicated dispute operations. Chargeflow Automation adds automated recovery to your checkout and financing setup. It also adds evidence enrichment. Confirm the account connection and case coverage when you set up.
Keep orders, fulfillment, refunds and customer messages linked to the payment reference. This keeps your response process the same across BNPL and other payment methods. Review Chargeflow's integration documentation and schedule a demo to map the workflow for your stack.
Perguntas frequentes: Klarna x Affirm
What is the difference between Klarna and Affirm?
They are separate providers. They differ in markets, program mix, eligibility decisions, merchant agreements and dispute workflows. Both offer Pay in 4 at 0% APR for eligible US purchases. Both also offer longer financing in supported programs. Compare the actual offer for your market and basket. Do not assume the two are interchangeable.
A Klarna e a Affirm são a mesma empresa?
No, Klarna and Affirm are separate, publicly listed companies. Klarna Group plc is headquartered in Stockholm, Sweden, and trades on the NYSE as KLAR. Affirm Holdings is headquartered in San Francisco and trades on Nasdaq as AFRM. Each sets its own shopper terms, merchant agreements and dispute rules.
Is Klarna or Affirm better?
Neither Klarna nor Affirm is better for every merchant. In 2025, 90% of Klarna's US loan volume carried 0% APR, so it often fits everyday baskets. 85% of Affirm's US volume was longer-term loans, so it often fits high-ticket orders. Test both with your own baskets, then pick the one that matches your customers.
Is Klarna or Affirm cheaper for merchants?
It depends on your agreement. How much Klarna or Affirm charges merchants comes from your contract or your payment platform's pricing. Rates vary by program, country and platform, so no single rate applies to every merchant. Compare signed proposals on total cost: transaction charges, refunds, settlement and dispute costs.
Is Klarna or Affirm cheaper for shoppers?
Both advertise Pay in 4 at 0% APR for eligible US purchases when payments are made on time. Affirm's longer financing is disclosed at 0 to 36% APR, based on credit and the offer. Terms depend on the shopper and the purchase.
Do Klarna and Affirm both offer Pay in 4?
Yes, both advertise Pay in 4 for eligible US purchases. Check the actual checkout offer. Look at eligibility, payment dates, disclosures and the total amount payable.
Is it hard to get approved for Klarna or Affirm?
Approval for Klarna or Affirm depends on the shopper, the purchase amount and the plan. Most BNPL plans use a soft credit check, which does not affect the shopper's credit score, according to the Federal Reserve. Neither provider guarantees approval, so a shopper can be approved for one basket and declined for another.
Does BNPL eliminate merchant disputes?
No. Financing does not remove order and fulfillment duties. Merchants may still need to provide delivery, cancellation, refund or service records. For example, Affirm typically gives merchants 15 days to respond to a dispute. Klarna disputes run through its Merchant Portal or API. Follow each provider's case instructions and your agreement.
Sources and Review Method
Reviewed October 19, 2026 against the primary sources linked beside the relevant claims. These include:
- The Federal Reserve's June 2026 BNPL note (loan volume, loan mix and 0% APR shares)
- Klarna's FY2025 results
- Affirm's FY2026 Form 10-K
- Each provider's dispute docs for merchants
This comparison explains documented features and business fit. The featured providers are Chargeflow partners. Examples are sample math for illustration. Workflow tests are suggested ways to evaluate, not claims of a controlled provider benchmark. Product availability and commercial terms depend on country, integration, plan and agreement. Confirm terms with each provider before you decide.
Take BNPL Disputes Off Your Plate
Chargeflow Automation builds and submits evidence for BNPL and card disputes, and answers pre-dispute inquiries on supported BNPL platforms.

Chargebacks?
Não é mais problema seu.
Recupere 4 vezes mais chargebacks e PREVENÇÃO — até 90% dos e-mails recebidos —, com tecnologia de IA e uma rede global Rede de 20.000 Lojistas.




