How AI Is Changing Payment Authorization, Fraud, and Chargeback Operations

Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.


 600+ reviews


TL;DR:
- Quick answer: AI speeds up five payment decisions (routing and authorization, fraud review, dispute alerting, evidence assembly, performance analysis) without changing who is liable.
- The issuer still makes the approve-or-decline call, so merchants influence AI authorization through data quality, network tokens, retries and authentication.
- Card-not-present payments are approved less often than card-present ones, and that gap is the room routing, tokens and retries compete for.
- Chargeback monitoring thresholds apply however an order was screened, so AI changes how fast you act inside the rules, not the rules themselves.
- Agent-initiated purchases add a buyer that is not a person, with separate liability, evidence and fraud questions covered in the agentic commerce pages.
AI in payments is not one feature, it is five separate operational decisions getting faster and more accurate at once: which route authorizes a transaction, which flagged order actually needs review, which merchant needs an alert before a dispute lands, what evidence gets assembled for a chargeback response, and which disputes are even worth fighting.
Baymard Institute's September 2025 review of 50 cart abandonment studies puts the average abandonment rate at 70.22%, and 10% of the shoppers who abandon cite a declined payment. MRC's 2026 Global eCommerce Payments and Fraud Report, a survey of 634 fraud professionals in 37 countries run in November and December 2025, found merchants rejected 5.0% of eCommerce orders on suspicion of fraud over the prior 12 months, and 65% estimated their false positive rate on eCommerce orders at between 2% and 10%. Authorization quality is a revenue problem before it is a fraud problem, and models work on both from the same transaction data.
Where AI Sits in the Payment Path
Different parties run the model at each step, which decides what a merchant can actually change.
| Step | Who runs the model | Decision it makes | What you control |
|---|---|---|---|
| Routing and orchestration | Your PSP, gateway or orchestration layer | Which acquirer or network path carries the payment, and whether to retry a decline | Which processors you connect, plus routing and retry rules |
| Fraud review | Your PSP, a fraud tool or an in-house model | Approve, review or block an order | Risk thresholds, the manual review queue, post-checkout screening rules |
| Authorization | Card network scoring and the issuer | Approve or decline the authorization request | The completeness and quality of the data you send, tokens and authentication |
| Alerting | Alert networks and your alert tooling | Whether to refund before a dispute is filed | Alert enrollment and refund automation rules |
| Evidence assembly | Dispute automation | Which evidence to build and submit, and which disputes to contest | Data access and your contest-or-accept policy |
Routing and Authorization Decisions
Every transaction still has to pick a path: which network it clears through, which acquiring bank processes it, and whether it gets approved, challenged, or declined. Rule-based systems made that call with a fixed checklist. If a transaction crossed a preset threshold, it got blocked, whether or not the customer was legitimate.
Machine learning models weigh purchase history, browsing behavior, device fingerprint, location, and transaction velocity together, then adjust as fraud tactics shift. A $2,000 purchase can be ordinary for one customer and a red flag for another, and the model tells the difference instead of applying one rule to both.
Smart routing extends the same logic to network and acquirer selection: which route has the highest approval rate for a given customer profile, and which payment service provider offers the best terms for that transaction type.
How AI Decides Whether a Payment Is Approved
On a card payment, the approve-or-decline answer comes from the issuer, not the merchant, and card networks score each authorization request with their own models. Visa describes Advanced Authorization as analyzing each transaction in near real time against hundreds of fraud detectors and risk attributes, and Mastercard said in 2024 that Decision Intelligence already scores 143 billion transactions a year, with its newer Pro version assessing relationships between transaction entities in under 50 milliseconds.
You cannot change the issuer's model, but AI payment optimization on the merchant side comes down to the inputs it receives:
- Data enrichment: Visa Acceptance Solutions lists data enrichment, dynamic retry, smart routing, filtering and payment insights as the five functions of AI-assisted service orchestration.
- Network tokens and account updates: Stripe's Authorization Boost bundles machine-learning retries and message formatting with network tokens and card account updater, and Stripe reports a 3.8% average increase in acceptance (methodology not published).
- Authentication: a successful 3D Secure 2.0 result raises issuer confidence and changes who carries fraud liability.
- Retry logic: soft declines can be retried, hard declines cannot, and the decline codes returned tell a model which is which.
For scale, VisaNet data for the US (April 2021 to March 2022) showed a 99% approval rate for card-present transactions and 92% for card-not-present, per Visa Acceptance Solutions. That 7-point gap is the room routing, tokens and retries compete for, and false declines are the cost of leaving it open. See how AI payment routing tools put this into practice.
Reducing Payment Friction Without Raising Fraud
Friction is any step that asks a good customer to do more than the risk justifies. AI risk scores let a merchant or PSP reserve extra steps, such as a 3D Secure challenge, for orders that score as risky and let the rest through. Baymard Institute's checkout research shows what shoppers who abandon actually name, and several of the reasons are payment-side:
| Reason for abandoning (Baymard, Sept 2025) | Share of abandoning shoppers | Payment-side lever |
|---|---|---|
| Concerns about credit card security | 19% | Tokenized saved cards and visible authentication |
| Checkout too long or complicated | 17% | Risk-based step-up instead of challenging every order |
| Payment declined | 10% | Smarter routing, retries and network tokens |
| Not enough payment options | 9% | Local and wallet methods through your PSP |
Shoppers could select more than one reason, so the shares do not sum to 100%.
Fraud Review Decisions
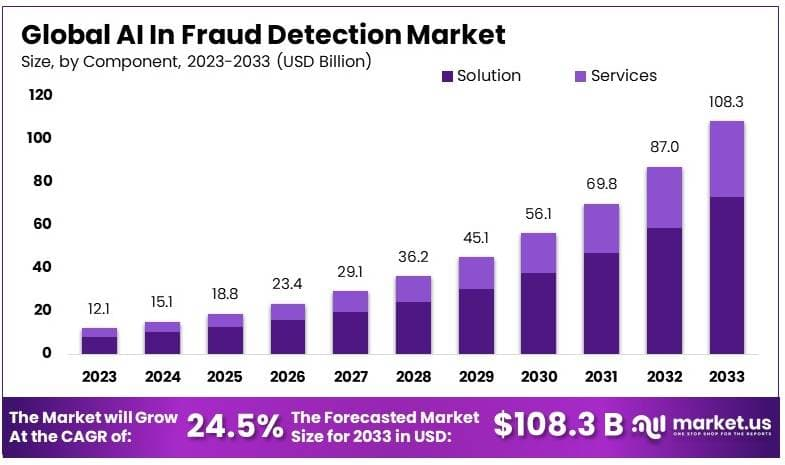
Fraudsters test stolen cards with small purchases, run bots to create fake accounts, and rotate tactics faster than a manual review team can keep pace with. Juniper Research (February 2025) projects fraudulent eCommerce transactions rising from $56 billion in 2025 to $131 billion in 2030 and names friendly fraud as the fastest-growing category, a pace a static rules engine cannot match on its own.
Neural networks trained on large transaction datasets catch fraud patterns a human reviewer would miss entirely: synthetic identities built from a mix of real and fabricated data, account takeovers that show up as subtle behavior changes, and card-testing bots making dozens of small purchase attempts in seconds. The review decision that matters most is not "block or allow," it's distinguishing unusual-but-legitimate from actually suspicious, since every wrongly declined order is a real customer lost. That review sits inside a broader ecommerce fraud prevention program, not as a replacement for it, and it matters most for card-not-present fraud, where the merchant carries the liability. See also AI fraud detection for ecommerce and how AI detects fake accounts.
Screening does not have to happen at checkout. Chargeflow Prevent scans orders after checkout and before fulfillment and recommends cancel, verify or approve based on your rules, using signals from a network of 20,000+ merchants and a false positive rate below 0.1%.
Alerting and Prevention Decisions
Every chargeback costs the sale plus chargeback fees and costs, and a rising ratio puts the merchant account at risk. The Visa Acquirer Monitoring Program treats a merchant ratio of 1.5% or more as Excessive from April 2026, and the Mastercard chargeback monitoring programs start at a 1.5% ratio with at least 100 chargebacks. Mastercard projects global chargeback cost rising from $36.9 billion in 2026 to $46.1 billion in 2029, based on research by Datos Insights. The decision AI improves here is timing: catching a risky pattern early enough to act before a dispute is filed, not after.

Network chargeback alerts from programs such as Verifi RDR and Ethoca tell the merchant a cardholder has questioned a transaction before a formal dispute lands, which leaves time to refund. Refund rules and models decide which alerts to act on at once, and Chargeflow Alerts reports deflecting up to 90% of chargebacks. Machine learning also separates criminal fraud from friendly fraud, customers who dispute a legitimate purchase, by weighing a customer's dispute history, whether they interacted with the product, and how their behavior compares to known patterns:
- Does this customer have a history of chargebacks?
- Did they interact with the product?
- How does their behavior compare to known friendly fraud cases?
Getting that call right decides whether the next step is prevention, deflection, or a documented dispute response, and it keeps your chargeback ratio under network thresholds before enforcement kicks in. Prevention and deflection work together, as these ways to prevent chargeback fraud show.
Evidence Assembly Decisions
Once a dispute is unavoidable, AI automates dispute management: gathering evidence, preparing a response, and submitting documentation without a human assembling it manually, so a person only makes the judgment calls. Evidence now has to match program rules such as Visa Compelling Evidence 3.0, and the format-matching is where automation saves the most time. For the wider picture, read about AI chargeback management.
Chargeflow Automation collects 1,000+ data points per dispute, builds the evidence, and submits it, charging 25% of each recovered chargeback with a 4X ROI guarantee. That is the operational answer to a common question: can AI improve chargeback dispute win rates? Evidence assembly speed and format-matching are the steps it changes most.
Performance Analysis Decisions
The last decision AI improves is the one merchants track least consistently: which customers become repeat buyers, which products carry higher lifetime value, and which payment methods your best customers actually prefer. Machine learning surfaces those patterns from data you already have, turning guesswork about retention and dispute trends into a measurable, ongoing signal instead of a quarterly guess.
The same analysis applies to the chargeback process itself: which reason codes recur, which product lines drive the most disputes, and whether your response deadlines are being met consistently enough to matter.
AI's Reach Beyond Fraud and Chargebacks
AI's operational footprint extends past the transaction itself. On the credit side, models evaluate alternative data (rent history, utility payments, employment stability) to approve creditworthy customers that a thin credit file would otherwise screen out, and the same logic is reshaping business lending: business credit cards with EIN only now use AI to evaluate company financials and EIN data instead of personal credit scores, giving new businesses access to capital without personal guarantees. In the EU, Annex III of the AI Act lists AI systems that evaluate the creditworthiness of natural persons as high-risk but excludes systems used to detect financial fraud, so credit decisioning and fraud screening carry different compliance obligations.
Cross-border payments get the same treatment: AI-driven KYC and AML checks run instantly rather than manually, and anomaly detection learns normal purchasing patterns per country so a legitimate cross-border order isn't treated the same as an obvious mismatch. Remote-work payments benefit too, since traditional payroll systems were never built for contractors spread across dozens of countries, and AI-driven platforms now handle currency conversion, tax withholding, and payout timing automatically instead of through manual, multi-platform transfers.
Agent-Initiated Payments: When the Buyer Is Software
AI shopping agents that complete a purchase for a customer add a buyer that is not a person typing card details at checkout, and routing, authorization and dispute rules all assume one. Each question has its own page:
| If you need to know | Read |
|---|---|
| Who pays when an agent-initiated transaction is disputed | AI agent chargeback liability |
| What counts as an authorized agent purchase, and which reason code it lands in | agentic commerce chargebacks and liability |
| Which evidence wins an agent-initiated dispute | evidence playbook for agentic commerce chargebacks |
| Which rules and network programs apply | agentic commerce regulation |
| How to detect and manage malicious or fake agents | preventing AI agent fraud |
| How to run legitimate agent transactions safely | fraud and chargebacks in agentic commerce |
| What the shift means at a high level | impact of agentic commerce on fraud and chargebacks |
| How AI shopping assistants change dispute drivers | AI shopping chargebacks |
How Merchant Type Changes the Priorities
The same models serve every merchant, but the decision that matters most differs by business model.
| Merchant type | Where AI usually helps most | Dispute pattern to watch |
|---|---|---|
| Ecommerce (physical goods) | Fraud review plus post-checkout screening before shipment | Item not received and friendly fraud |
| Marketplaces | Fake account and seller screening, buyer trust scoring | Not as described and seller non-delivery |
| Subscriptions and SaaS | Retry timing for failed renewals, card account updates | Unrecognized charges and renewal disputes |
| Travel | Risk review of high-ticket card-not-present bookings | Disputes after cancellations and service disruption |
| Digital goods | Card-testing and velocity detection, since delivery is instant | Friendly fraud after the content is consumed |
| Fintech and crypto | Account takeover and identity screening on funding and withdrawals | Unauthorized transaction claims |
AI Changes What You Automate, Not What You're Liable For
None of this changes the underlying liability rules. A card network still decides whether a fraud dispute shifts to the issuer or stays with the merchant, and a chargeback ratio threshold still triggers monitoring regardless of how the transaction was reviewed. What AI changes is how fast a merchant can act inside those rules. Merchants who treat AI as a replacement for understanding what a chargeback is will still lose disputes they should have won; merchants who use it to operate faster inside the existing rules are the ones who see the ratio improve. For a broader look at where these shifts are headed next, see Chargeflow's payment security trends and predictions.
Frequently Asked Questions
Can AI actually reduce chargebacks, or does it just detect fraud faster?
Both. Faster, more accurate fraud detection prevents some chargebacks from ever occurring, while AI-driven alerting and evidence automation reduce how many of the remaining disputes a merchant actually loses. The reduction in chargeback rate comes from combining prevention with better dispute response, not from either one alone.
Does using AI fraud detection change who is liable for a dispute?
No. Liability rules are set by card networks and issuers, not by the fraud detection technology a merchant uses. AI can reduce how often a merchant is exposed to a liability-shifting scenario, but it does not change the underlying rule itself.
How does AI improve chargeback evidence for disputes?
AI systems gather relevant data automatically (delivery confirmation, device and IP data, prior communication, authentication results) and match it to the evidence format a specific issuer or reason code expects, which is typically the slowest part of a manual dispute response.
Can AI predict which chargebacks are worth fighting?
Yes, by learning from historical outcomes: which evidence types won past disputes with a given issuer or reason code, and which cases were unlikely to succeed regardless of the evidence submitted. That lets a merchant prioritize effort instead of contesting every dispute equally.
Is AI-based fraud detection different from the rule-based systems merchants already use?
Yes. Rule-based systems apply fixed thresholds (a purchase over a certain amount from a new device gets blocked, for example) regardless of context. AI models weigh many signals together and adjust as fraud patterns change, which is why they catch fraud a static rule would miss while also approving legitimate orders a static rule would have blocked.
What is a good payment authorization rate?
It depends on how the card is presented. VisaNet data for the US (April 2021 to March 2022) showed 99% approval for card-present transactions and 92% for card-not-present, so an online merchant well below the low 90s has recoverable declines worth investigating by decline code, issuer and payment method.
How does AI reduce payment friction?
Risk scores let a PSP or merchant challenge only the orders that look risky, for example with a 3D Secure step-up, and approve the rest without extra steps. Retrying soft declines and using network tokens cut declines that the customer would otherwise have to fix by re-entering a card.
What does AI payment optimization include?
It covers smart routing across acquirers and networks, retry timing for soft declines, data enrichment on authorization requests, network tokens and card account updates, and analytics on approval rates by issuer and payment method.
Can AI make payments on its own?
AI shopping agents can initiate a purchase on a customer's behalf, but liability for a disputed agent purchase still follows card-network rules, and merchants need evidence of the customer's authorization to defend it.
Chargeflow handles the last of these decisions for you: automated dispute resolution builds and submits the evidence while your team makes the judgment calls.
Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.