Affirm Disputes: A Merchant's Complete Guide to Prevention, Evidence, and Winning Claims
Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.


 600+ reviews
TL;DR:
- Identify the Affirm payment product, integration, store, and disputed transaction.
- Use the notice’s webform or portal action channel rather than replying by email.
- Follow the displayed due date and provide purchase-specific evidence.
- Reconcile case decisions with settlements and existing refunds.


An Affirm dispute is a customer complaint about a purchase financed or paid for through an Affirm product. The merchant response depends on the integration and payment product, including whether the case is handled by Affirm or through a card-payment provider.
Start with the actual notice. An Affirm checkout purchase and a purchase made with an Affirm Card should not automatically be assigned the same evidence channel or fee rule.
How to Dispute an Affirm Purchase (Customer Side)
If you paid with Affirm and the merchant will not resolve a problem, you can open a dispute with Affirm. Contact the merchant first; Affirm expects customers to try that before filing. Then open the purchase in your Affirm account (app or affirm.com) and use the dispute option, or contact Affirm support to file.
- Time limit: Affirm does not set a post-purchase filing deadline. Its merchant policy states that customers can open a dispute even for purchases made more than 60 days ago.
- Payments during the dispute: you are not required to make payments while the dispute is open, and Affirm withholds the disputed amount until it is resolved.
- How long it takes: the merchant typically has 15 days to respond with evidence. Affirm then communicates its decision to both sides within 15 calendar days of collecting evidence, so most cases resolve within about a month.
- Who wins: Affirm resolves disputes in favor of the party that, in its reasonable view, best substantiates its claim. It does not automatically side with the customer or the merchant.
If you paid with an Affirm Card instead of Affirm checkout financing, the case may run through the card network as a Visa dispute rather than Affirm’s own process. These rules come from Affirm’s dispute-resolution policy, linked below.
Identify the Payment Product and Case Owner
Affirm describes its card product on the official Affirm Card page. For merchants, the operational question is which transaction your provider processed and which system issued the evidence request. Use that record to select the dispute route.
| Case detail | Why your team needs it |
|---|---|
| Order and charge or product reference | Connects the purchase to the disputed financing or payment. |
| Dispute reason and customer comments | Defines what the response must address. |
| Disputed amount | Separates full-order claims from partial issues. |
| Due date and action link | Identifies the required response time and channel. |
| Store or account | Prevents a case being missed in another account’s queue. |
Use the Notice’s Action Channel
Affirm’s Merchant Portal dispute guide describes webform and portal response options and says replies to the notification email are not supported. It gives a typical 15-day response window, while the notice and detail page specify the actual due date.
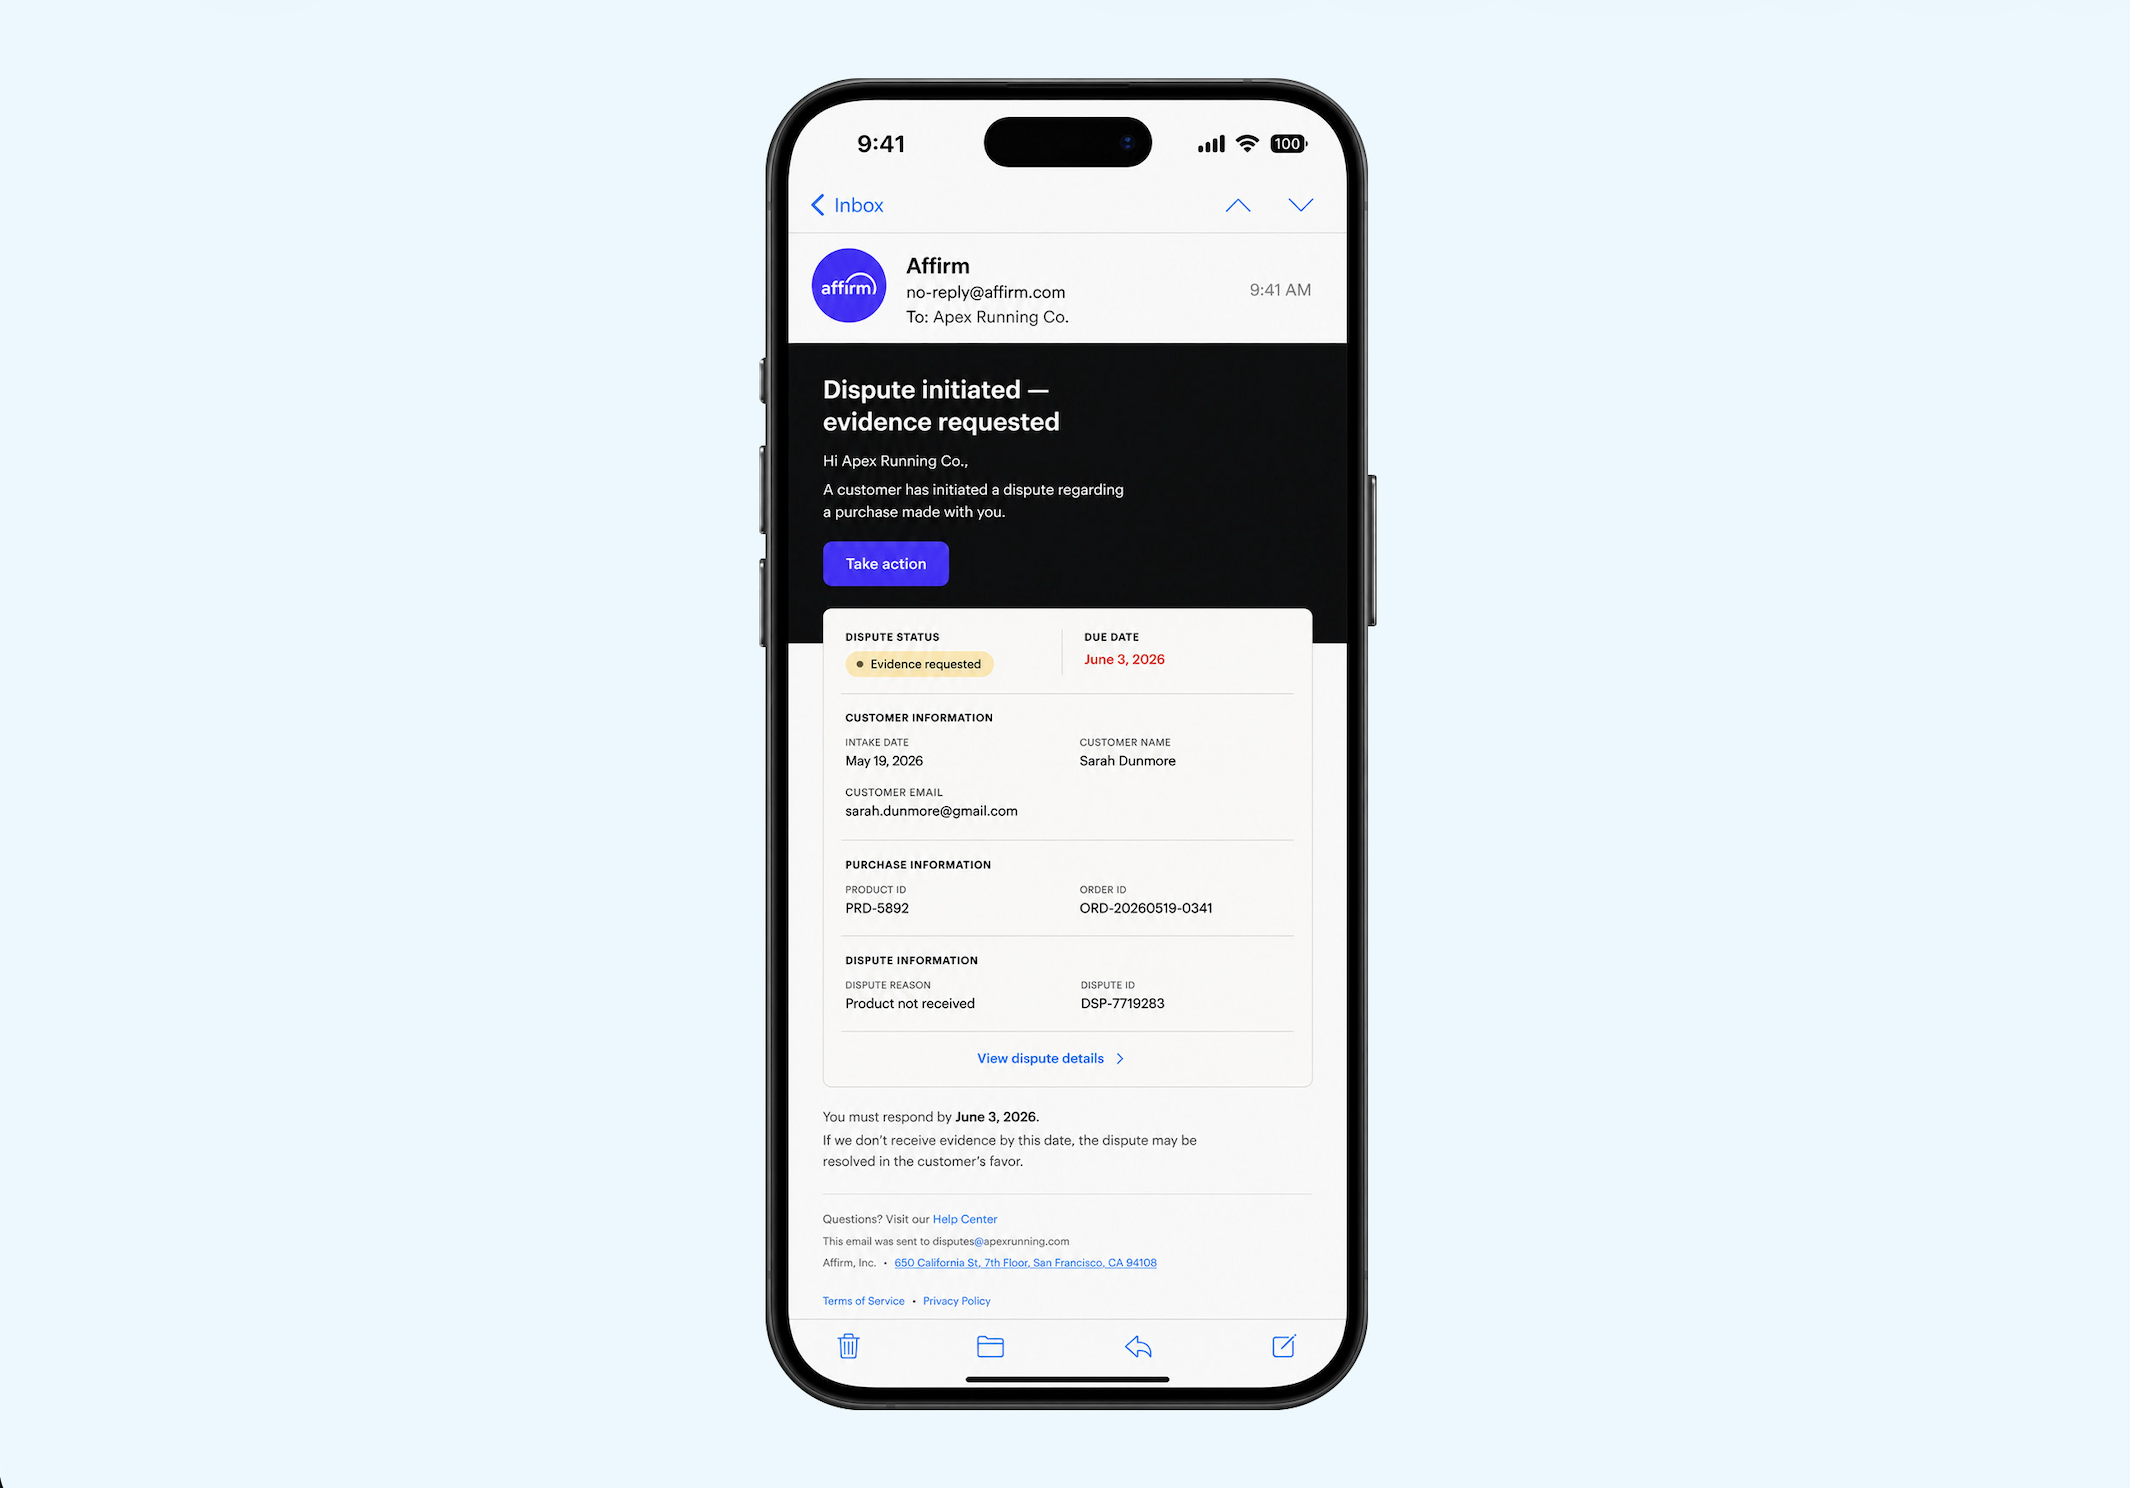
Treat the illustration as an example, not the deadline for your case. Assign one person to check the current notice, verify the transaction, and confirm successful submission. Save the confirmation with the response materials.
Build Evidence Around the Purchase Problem
- Nonreceipt: the delivery agreement and fulfillment outcome for the disputed purchase.
- Unacceptable product: the purchase-time description, customer complaint, and resolution offered.
- Cancellation or return: the request, acceptance or rejection, receipt of goods, and refund status.
- Incorrect or duplicate amount: the agreed price, payment references, and adjustments.
For nonreceipt and product-description cases, provide the facts specific to that allegation. For billing errors, reconcile amounts before responding. A generic policy attachment does not replace an explanation of what happened.
Use standard evidence categories and a concise chronology. If the complaint is valid, document the supported remedy rather than challenging by default.
Read Status and Settlement Records Together
Affirm’s portal guidance distinguishes cases needing action, cases under review, merchant wins, and customer refunds. A submitted response is not the final financial outcome. Match the decision to the payment and settlement adjustments.
The Affirm dispute-resolution policy and merchant agreement govern the applicable responsibilities. The policy specifies a $15 dispute fee for applicable U.S. resolutions in the customer’s favor and describes a decision within 15 calendar days of evidence collection. Confirm the terms for your integration and reconcile the actual settlement entries.
Before issuing another credit, check refund and dispute overlap. Confirm partial amounts carefully and link the processed refund reference to the original transaction.
Monitor Follow-Up Requests and Repeated Causes
Do not treat a previous response as proof that every later request is already satisfied. Review any new notice, connect it to earlier case references, and follow the current instructions. Keep store-level queues visible to the responsible owner.
For another BNPL workflow, see Klarna dispute handling. For a card-routed case, use the credit-card chargeback framework. You can organize supported evidence and response workflows with Chargeflow’s automated recovery.
Frequently Asked Questions
Can a merchant reply to an Affirm dispute notification email?
Affirm’s Merchant Portal guide says notification-email replies are not supported. Use the action link, webform, or Merchant Portal route specified in the notice.
How long does a merchant have to respond to an Affirm dispute?
Affirm describes a typical 15-day merchant response period, but the actual due date is shown in the notice and dispute detail page. Follow that case-specific date.
Does every Affirm payment use the same dispute process?
Affirm payment products and integrations can use different dispute routes. Identify the transaction and notice before applying a portal workflow, card-network deadline, or fee assumption.
Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.