















How to Prevent and Recover Adyen Chargebacks in 2026: A Strategic Guide

Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.


 600+ reviews


TL;DR:
Adyen chargeback management combines Adyen's built-in dispute tools, RevenueProtect fraud screening, 3D Secure 2, the Disputes API, and Visa RDR alerts, with a merchant's own evidence and response strategy to fight disputes before and after they become chargebacks.
- Defense windows are scheme-specific: Visa gives merchants 9 or 18 days, Mastercard 40 days, and TWINT just 10 days to respond after a Notice of Chargeback.
- Visa's Rapid Dispute Resolution (RDR), run by Verifi, can resolve a dispute in as little as one second by triggering an automatic refund before it becomes a formal chargeback.
- Mastercard projects global chargeback volume will climb from roughly 261 million cases in 2025 to 324 million by 2028.
- Every $1 lost to a chargeback costs merchants an average of $5.13 once fees, lost goods, and staff time are counted, per the 2026 LexisNexis True Cost of Fraud study.
- Pairing Adyen's fraud prevention stack with Chargeflow's automated evidence and response system lets merchants defend disputes without building an in-house chargeback team.
Chargeflow is integrated with Adyen. See the Chargeflow and Adyen integration.
Adyen chargeback management is the combination of tools, RevenueProtect fraud screening, 3D Secure 2 authentication, the Disputes API, and Visa RDR alerts, that Adyen gives merchants to prevent, respond to, and win payment disputes before they erode revenue. For merchants processing through Adyen, a global payment service provider (PSP), understanding how these dispute stages, deadlines, and defense tools fit together is what decides whether a dispute becomes a lost sale or a recovered one.
Online payment volume keeps climbing, and so does chargeback fraud tied to that growth. Chargebacks exist to protect cardholders, but every dispute filed against your business, legitimate or not, carries fees, lost goods, and administrative overhead. Before going further, it helps to be clear on what a chargeback is and why issuers use them.
This guide walks through how Adyen's payment platform handles disputes end to end: the stages a dispute moves through, the deadlines attached to each one, the tools Adyen gives you to fight back, and where an automated layer like Chargeflow closes the remaining gaps.
The Evolving Nature of Chargebacks
Chargeback behavior has shifted as online shopping has grown. Consumers are more aware of their dispute rights than they were a few years ago, and many now file a dispute with their bank before ever contacting the merchant about a late delivery, an unrecognized charge, or a product they simply changed their mind about. Much of that shift is driven by friendly fraud, where a legitimate cardholder disputes a transaction they actually authorized instead of requesting a refund directly.
The scale of the problem keeps growing. Mastercard projects global chargeback volume will climb from roughly 261 million cases in 2025 to 324 million by 2028, a jump of more than 20% in three years. Every one of those disputes carries a cost well beyond the transaction itself: the 2026 LexisNexis True Cost of Fraud study puts the average total cost at $5.13 for every $1 lost to a chargeback, once fees, lost merchandise, and staff time are counted.
Managing that volume takes more than reacting to disputes as they land. It means analyzing which transaction patterns lead to chargebacks, communicating clearly with customers about orders and refunds, and using fraud detection technology to stop bad transactions before they settle. Adyen's RevenueProtect fraud engine and dynamic 3D Secure authentication give merchants a first line of defense here, flagging suspicious activity and shifting liability away from the merchant when authentication is properly applied.
A newer wrinkle is agentic commerce: AI shopping agents that complete Adyen-processed purchases on a shopper's behalf. When an agent buys the wrong item, or a shopper later claims they never authorized the agent to spend, liability for the resulting dispute is not always clear. Merchants accepting these transactions should understand how AI agent chargeback liability is being defined and start building an evidence playbook for agentic commerce disputes before this becomes a larger share of chargeback volume.
Prevention only goes so far, though. When a dispute does land, Adyen's platform is built to help you defend it and, where possible, reverse it before it settles as a loss. Pairing that platform with a dedicated chargeback automation layer like Chargeflow closes the gap between "Adyen flags the risk" and "someone actually builds and submits the winning response."
Preventative Measures with Adyen
Preventing a chargeback is always cheaper than fighting one. Adyen bundles several tools that, used together with a broader ecommerce fraud prevention strategy, cut down how many disputes you see in the first place. Here are the ones worth setting up first:
- Set up Risk Management Tools: Adyen's risk management settings let you tailor rules to your exact business, blocking high-risk transactions outright or flagging them for manual review. Configure your risk settings here.
- Implement Authentication Methods: Adyen's support for 3D Secure 2 lets you require additional shopper verification before a transaction is approved, reducing fraudulent chargebacks and shifting liability away from the merchant.
- Optimize Transaction Security with Dynamic 3D Secure: Apply 3D Secure selectively based on each transaction's risk score, so low-risk purchases skip the extra friction while high-risk ones get an additional verification step. To learn more, see Adyen's 3D Secure guide.

- Apply Adyen's RevenueProtect: RevenueProtect combines machine learning with static rules to analyze payment data at scale, identifying and blocking fraudulent activity before it ever becomes a chargeback.
- Optimize Payment Descriptions: Unclear billing descriptors are a common trigger for disputes over transactions a customer simply doesn't recognize. Adyen lets you personalize each descriptor so it matches what the shopper actually sees at checkout.
- Provide Stellar Customer Service: Fast, responsive support prevents a shipping delay or a product question from turning into a dispute. Adyen's communication tools help you keep customers updated on transactions, disputes, and refunds without the delay that pushes them toward their bank instead.
Understanding Adyen's Dispute Stages, Reasons, and Timelines
A dispute on Adyen typically starts before it ever becomes a formal chargeback. Adyen may first send a Notification of Fraud (NOF) or a Request for Information (RFI) to alert you to potential fraud or ask for more transaction detail. If that doesn't resolve the issue, the issuer moves to a Notification of Chargeback (NoC), which you can defend.
The flow of a dispute:

Once a chargeback is filed, Adyen classifies it with a reason and code that maps to one of four groups defined in the Mastercard reason code framework. Knowing which group a dispute falls into tells you what kind of chargeback reason and evidence you're actually up against:
- Fraudulent Transactions: Unauthorized use or identity theft claims.
- Authorization Issues: Transactions processed without proper authorization.
- Processing Errors: Technical errors or clerical mistakes.
- Customer Disputes: Product dissatisfaction, non-receipt, or item misdescription.
Deadlines are the part merchants underestimate most. They aren't uniform: each card scheme sets its own window for responding to an RFI, defending a chargeback, and how long a cardholder can wait before filing in the first place. Here's how the major schemes compare on Adyen, based on Adyen's published dispute timeframes:
| Card Scheme | Merchant Defense Window (After NoC) | Cardholder Filing Window | Notes |
|---|---|---|---|
| Visa | 9 or 18 days | 120 days (up to 540 for pre-orders/travel) | 9-day window applies to US/Canada disputes processed locally, effective July 2025 |
| Mastercard | 40 days | 120 days | Longest standard defense window among the major schemes |
| American Express | 14 days | 120 days | RFI stage, when issued, also runs 14 days |
| Diners / Discover / JCB | 18-25 days | 120 days | RFI response window is 18 days across all three schemes |
| China UnionPay (CUP) | 30 days | 180 days | Longest cardholder filing window of any scheme Adyen supports |
| TWINT | 10 days | 100 days | Shortest defense window; build alerts so you never miss it |
| Klarna / Afterpay (BNPL) | 7-14 days | 120 days | Klarna RFI drops to 96 hours for high-risk orders |
Missing any one of these deadlines has the same result regardless of scheme: the dispute is decided against you by default, with no chance to submit evidence afterward. For businesses on Adyen, understanding these codes and clocks is central to minimizing chargebacks and steering dispute resolution in your favor. It's also exactly the kind of deadline-tracking work that's easy to automate rather than manage by hand.
Effective Dispute Management
Step 1: Understanding the Dispute Process
- The dispute process begins when a shopper raises a dispute.
- Two optional stages may precede a formal chargeback:
- Notification of Fraud (NOF): Adyen notifies you of fraud activity; no money is withdrawn yet. Review the NOF, issue a refund if appropriate, block the shopper, and stop shipment if possible.
- Request for Information (RFI): The issuer asks for more detail about the transaction. No money is withdrawn at this stage, but missing the response window can trigger a chargeback.
Step 2: Notification of Chargeback (NoC)
- The issuer initiates a chargeback that can be defended.
- Adyen automatically defends chargebacks that don't require your input, such as fraud chargebacks where liability has already shifted to the issuer.
- For everything else, you upload defense documents through the Customer Area or the Disputes API.
Step 3: Dispute Continuation
- From here, the dispute can move through several stages:
- 1st Chargeback: The disputed amount is withdrawn from your account. This is final if you accept the dispute or miss the defense deadline.
- Information Supplied: Adyen forwards your supporting documents to the scheme; they can't be changed after this point.
- Chargeback Reversed: The disputed amount returns to your account if the issuer accepts your defense or their response window expires.
- Pre-arbitration (Visa, Mastercard, Diners): If the issuer declines your defense, they can open pre-arbitration, which Adyen reviews on your behalf.
- 2nd Chargeback: If the issuer declines your defense or Adyen accepts the pre-arbitration case, a second chargeback occurs and no further documents can be uploaded.
Step 4: Defense Timeframes
- Every issuing bank works to its scheme's specific timeframe, as outlined in the table above.
- Cardholders generally have up to 120 calendar days from the transaction date to dispute a charge, extending to 540 days for pre-order or travel-related purchases.
- RFI response windows range from 96 hours for high-risk orders up to 30 days for China UnionPay, so check the scheme before assuming you have the standard window.
Step 5: Final Decision
- After you respond and provide defense documents, expect a final decision from the issuer or scheme.
- If the dispute is lost, or you fail to upload documents in time, your account is debited and the dispute is closed as a loss.
Step 6: Optional Status (American Express)
- For American Express chargebacks, a ChargebackReversed status is optional.
- If you defend a dispute successfully, it stays at the information-supplied stage.
- If American Express rejects your defense, the dispute is lost and that decision is final.
- In rare cases, American Express can reopen a dispute previously closed in your favor, escalating it to a second chargeback, which is the final status.
Standard Chargeback Defense vs. Visa RDR Pre-Dispute Alerts
Not every dispute has to become a chargeback. Adyen supports Visa's Rapid Dispute Resolution (RDR), a pre-dispute alert program built by Verifi, that lets you resolve a cardholder's claim with an automatic refund before the issuer ever files a formal chargeback. It's worth understanding how this compares to defending a dispute the standard way, since the two approaches suit different situations. These pre-dispute alerts work on the same principle as the chargeback alert services many merchants already use with other processors.
| Aspect | Standard Chargeback Defense (Disputes API) | Visa RDR (Verifi) Pre-Dispute Alert |
|---|---|---|
| Trigger point | Cardholder formally disputes with the issuing bank | Cardholder contacts the card network before a formal chargeback is filed |
| Resolution speed | Days to weeks, covering defense submission and issuer review | Can resolve in as little as one second per case |
| Merchant effort | Full evidence package required for each dispute | Merchant pre-sets refund rules once; matching cases are handled automatically |
| Impact on dispute ratio | Counts toward your chargeback ratio if the defense is lost | Resolved as a refund, so it does not count as a chargeback |
| Best fit | Higher-value disputes where you hold strong evidence | High-volume, lower-value disputes, especially friendly fraud |
In practice, most Adyen merchants need both: RDR-style alerts to absorb the high-volume, low-value noise, and a strong defense process, whether built in-house or automated through Chargeflow, for everything that still turns into a formal chargeback.
Leveraging Adyen's Advanced Capabilities for Preemptive Chargeback Mitigation
Adyen bundles several advanced features aimed at enhancing the customer experience, streamlining operations, and tightening security. Here's how each one contributes to lower chargeback exposure:
- Real-Time Analytics
Immediate insight into transactions, customer behavior, and performance metrics lets you spot unusual activity, like repeated failed attempts or abnormal purchasing patterns, and act on it before it turns into a chargeback.

- Fraud Detection Systems
Machine learning models assess every transaction in real time using device fingerprinting, behavioral analysis, and historical data to assign a risk score. High-risk transactions get flagged for manual review or rejected automatically.

- Risk Management Tools
RevenueProtect gives you granular controls to balance risk tolerance against customer experience: rules based on filters and attributes, velocity checks, and access to Adyen's global fraud-signal database. Fine-tuning these settings keeps unauthorized transactions out without adding friction for legitimate customers.
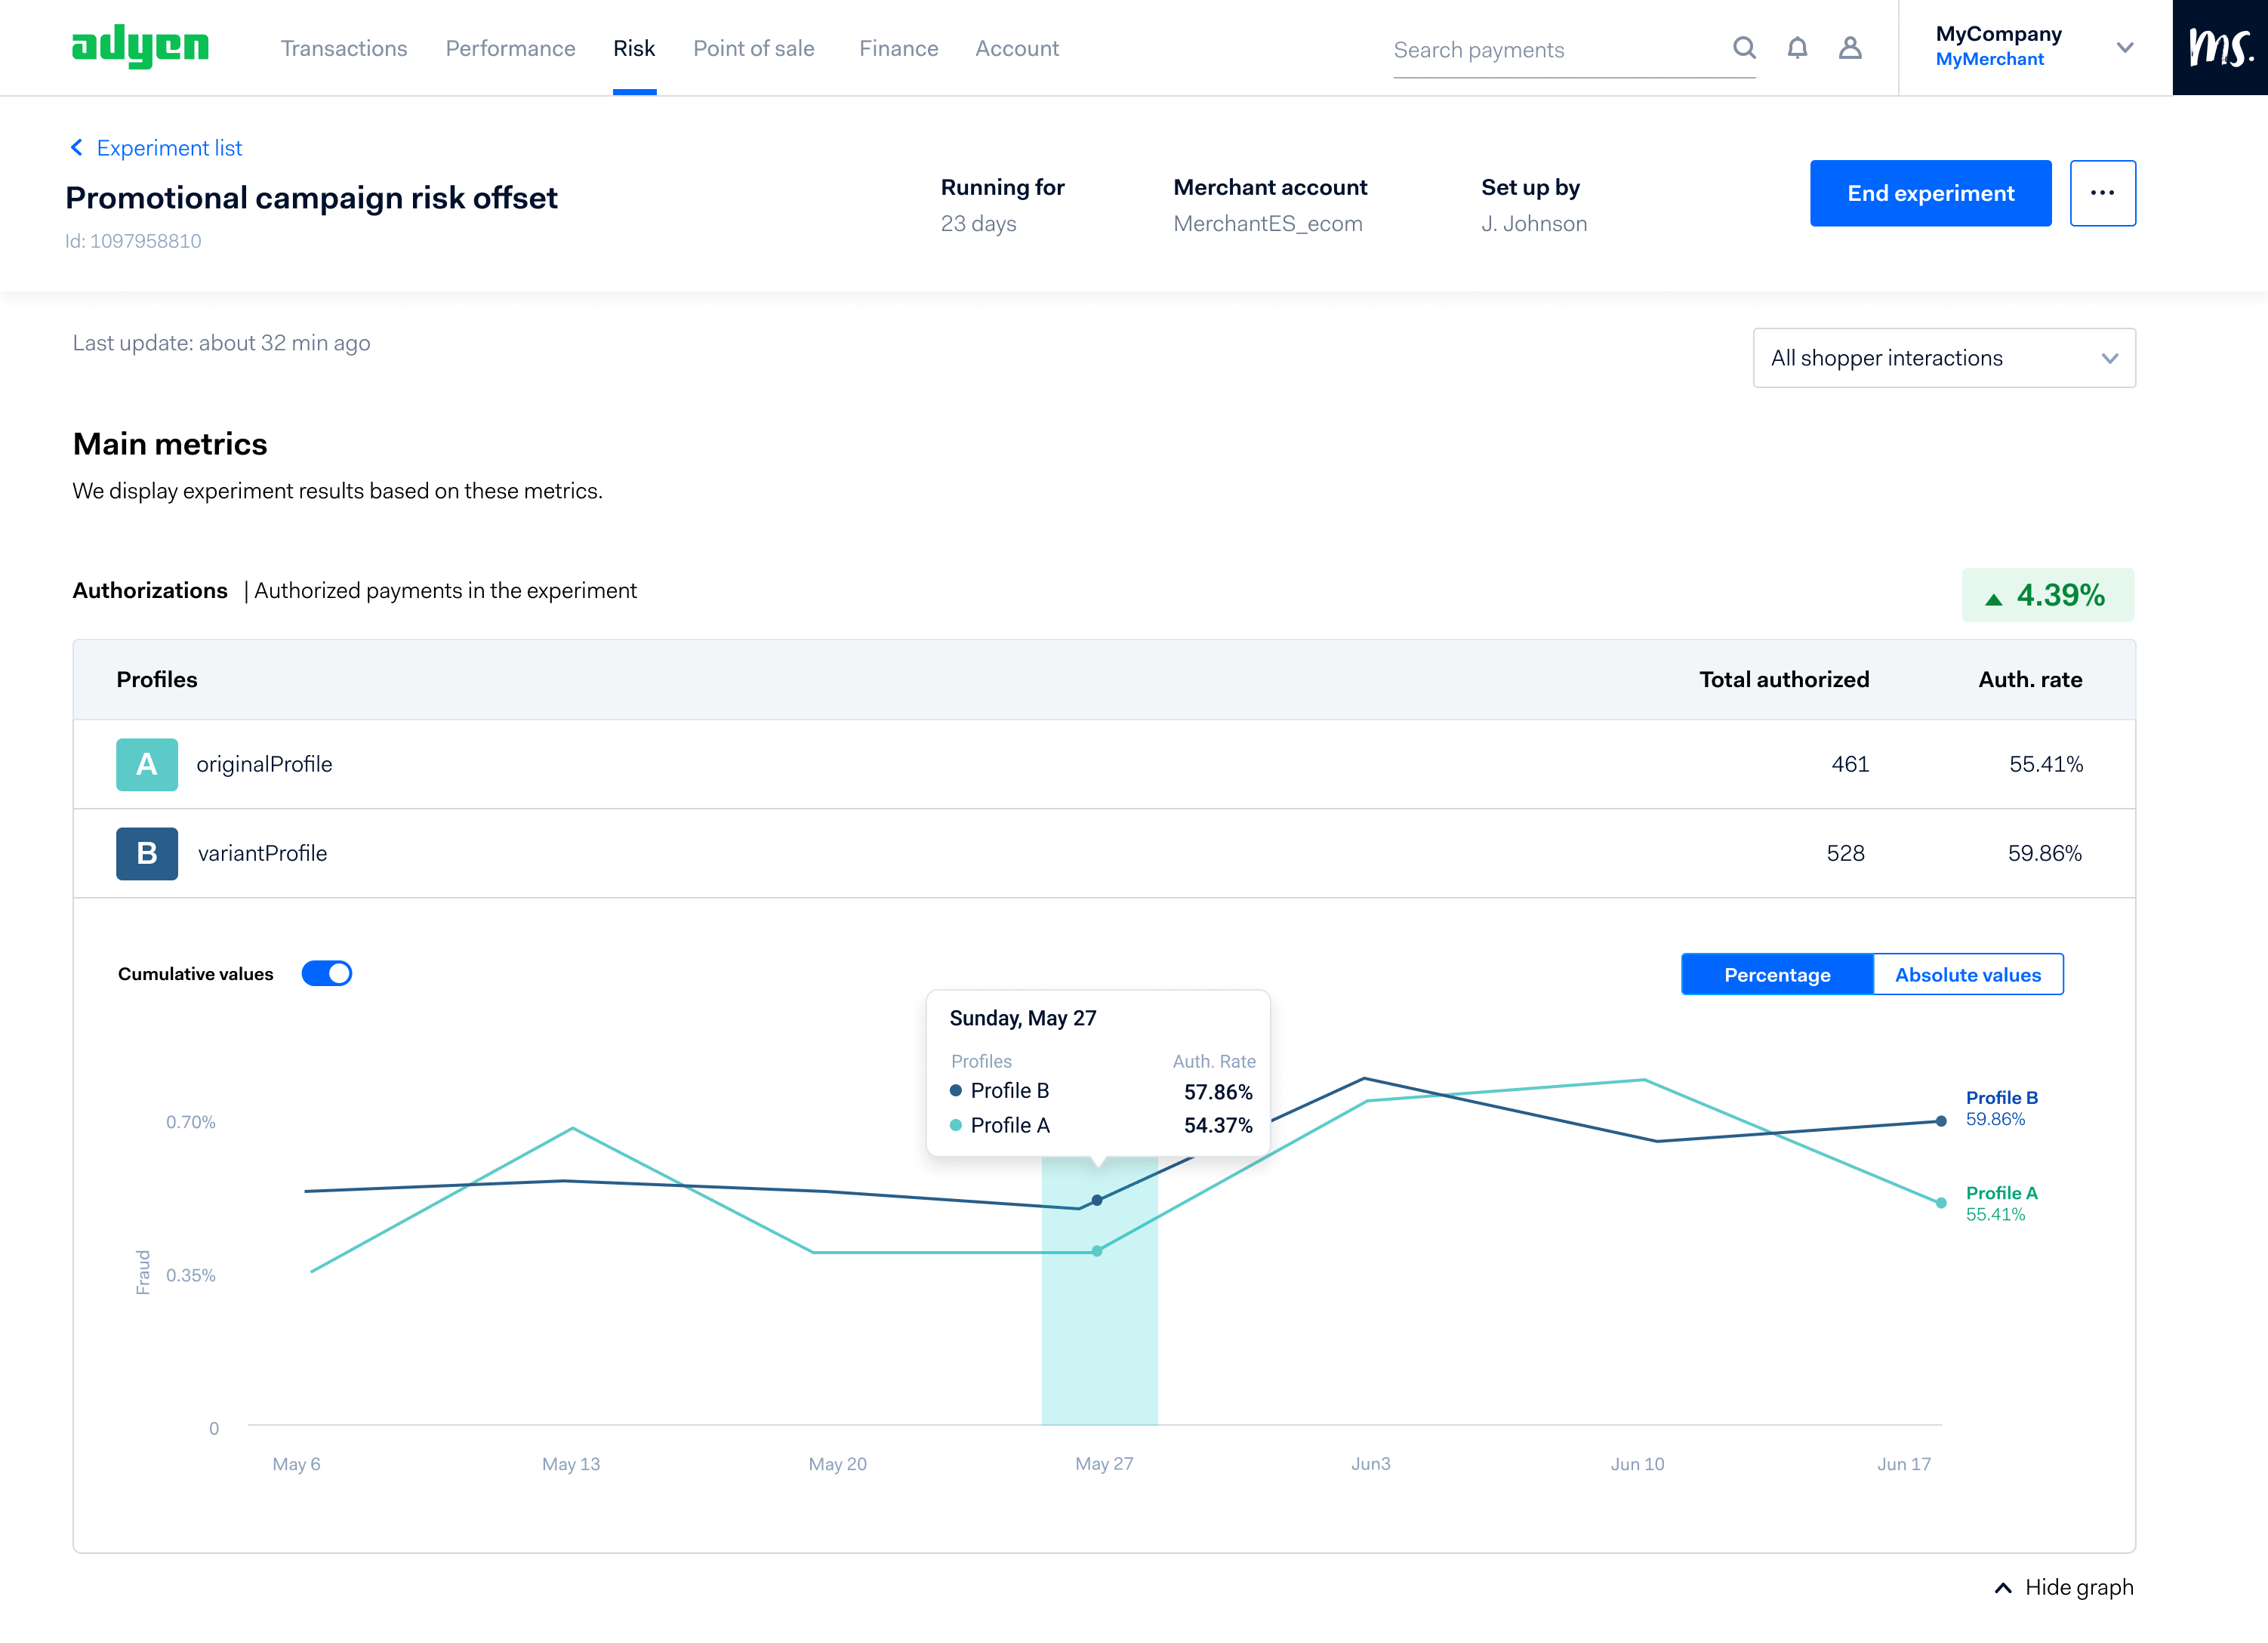
- Preemptively Addressing Chargeback Risk
Combined, real-time analytics, fraud detection, and customizable risk rules give merchants a framework to catch and stop fraudulent transactions before they settle, rather than fighting the resulting chargeback weeks later. Real-time insight also means you can act immediately: confirm a legitimate transaction with the customer, or tighten risk parameters the moment a new pattern emerges.
Adyen and Chargeflow: A Complete Chargeback Defense System
Adyen's real-time analytics, fraud detection, and risk management tools give merchants a strong foundation for catching fraudulent transactions before they become disputes. But chargebacks still happen, whether from processing errors, genuine customer dissatisfaction, or friendly fraud that no fraud filter can fully screen out. Even a payment platform running at maximum efficiency will generate some volume of disputes simply because of transaction volume.
That's the gap Chargeflow's integration with Adyen is built to close. Chargeflow uses AI-driven technology to provide merchants with real-time dispute management, analyzing dispute data, compiling evidence, and submitting responses automatically instead of leaving that work to a manual process. Merchants running Adyen and Chargeflow together can manage payment processing and chargeback defense through the same operational workflow, rather than treating dispute response as a separate, understaffed task competing for attention with everything else.
Put simply: Adyen's tools reduce how many disputes you see in the first place, and Chargeflow makes sure the ones that still land get a real, evidence-backed response instead of a default loss. Together, that's a materially stronger position than either layer offers on its own, without requiring merchants to build in-house chargeback expertise to get there.
Frequently Asked Questions
What does Adyen chargeback management actually involve?
It covers the full lifecycle of a payment dispute on Adyen's platform: preventing fraud with tools like RevenueProtect and 3D Secure, tracking scheme-specific deadlines once a dispute is filed, submitting evidence through the Disputes API or Customer Area, and using pre-dispute alert programs like Visa RDR to resolve some claims before they ever become formal chargebacks.
How long do merchants have to respond to an Adyen dispute?
It depends on the card scheme. Visa gives merchants 9 or 18 days after a Notice of Chargeback (the shorter window applies to certain US/Canada transactions since July 2025), Mastercard allows 40 days, American Express 14 days, and TWINT just 10 days. Missing the window means the dispute is decided against you by default.
Does Adyen automatically defend any chargebacks?
Yes. Adyen automatically defends chargebacks that don't require merchant input, most commonly fraud-related chargebacks where liability has already shifted to the card issuer through 3D Secure authentication. Every other dispute requires the merchant to submit defense documents manually or through the Disputes API.
What is Visa RDR and how is it different from a standard chargeback?
Rapid Dispute Resolution (RDR) is a Visa program, operated by Verifi, that lets enrolled merchants resolve a cardholder's claim with an automatic refund before it becomes a formal chargeback. Cases can resolve in as little as one second, and because the outcome is a refund rather than a lost dispute, it doesn't count against the merchant's chargeback ratio.
What happens if a merchant misses Adyen's defense deadline?
The dispute is automatically decided against the merchant. The disputed amount is withdrawn (or stays withdrawn) from the merchant's account, and no evidence can be submitted after the deadline passes, regardless of how strong that evidence might have been.
Can Chargeflow automate chargeback responses for Adyen transactions?
Yes. Chargeflow integrates directly with Adyen to monitor incoming disputes, compile supporting evidence, and submit defense responses automatically, so merchants don't have to track scheme-specific deadlines or build a case manually for every dispute that lands.
Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.




