















Mastercard Chargeback Survival Guide for Merchants (2026)

Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.


 600+ reviews


TL;DR:
- Timelines: You have 45 days to respond to a Mastercard chargeback (15 more than Visa gives you), while cardholders get up to 120 days to file in the first place; miss your window and the case decides against you automatically.
- Process: First Chargeback → Second Presentment → Pre-Arbitration (30 days to challenge or you lose automatically) → Arbitration → Appeal.
- Cost and compliance: The average chargeback costs $128 all-in (Mastercard, 2026). ECM starts at 100+ chargebacks and a 1.5% ratio, with fines escalating past $100,000 a month.
- Win more: Reason-code-specific evidence plus automated chargeback protection lifts win rates from the 8-20% manual average toward 80%.
A Mastercard chargeback is a forced payment reversal: the cardholder's issuing bank pulls the transaction amount back from your acquirer after the customer disputes a charge. Cardholders get up to 120 days to file (90 for some categories), you get 45 days to respond with reason-code-specific evidence, and every case follows the same cycle: First Chargeback, Second Presentment, Pre-Arbitration, Arbitration, and Appeal. Stay under Mastercard's Excessive Chargeback thresholds (100+ monthly disputes at a 1.5% ratio) to avoid fines, and automate evidence to push win rates from the 8-20% manual average toward 80%.
One click. That's all it takes for a customer to dispute a payment. And for your business to lose revenue, often more than the original transaction amount.
Mastercard and Datos Insights project 286 million chargebacks globally in 2026, climbing 37% to 359 million a year by 2029. Understanding Mastercard's dispute process is critical for business survival.
This playbook draws on lessons learned from assisting over 20,000 merchants in successfully disputing and winning chargebacks. It pierces the corporate veil of Mastercard's chargeback rules, reason codes, timelines, and recovery strategies. By the end, you will learn:
- Why chargebacks keep climbing
- Mastercard's four-step chargeback process in plain terms
- Industry-specific prevention strategies to cut disputes by 60-80%
- Evidence-based strategies to win Mastercard chargebacks
- How Mastercard's rules differ from Visa's, plus the network-only tools (Ethoca Alerts, First-Party Trust) that stop disputes before they post
- Real-world implementation roadmaps for businesses of all sizes
Mastercard Chargeback Timeline at a Glance
| Phase | Issuer / Cardholder Deadline | Merchant Response | Key Fee |
|---|---|---|---|
| First Chargeback | Cardholder: 120 days (90 for some categories) | 45 days to represent | Acquirer $15–25 |
| Pre-Arbitration (2nd chargeback) | Issuer: 45 days to file | 30 days to challenge | $15 filing |
| Arbitration | Issuer escalates to Mastercard DRM | 15 days to respond | $150 filing + $250 admin |
| Appeal | 45 days from ruling | Written appeal with new evidence | $500 |
Understanding the Mastercard Chargeback Landscape
Mastercard chargebacks occur when a customer disputes a completed transaction with their card issuer or bank, resulting in a reversal of funds. This process is similar across all card networks.
Mastercard promotes its chargeback system as a way to build trust and security for consumers. But that safety net often translates to a financial and operational strain for merchants like you.
Why Mastercard Chargebacks Are Rising: The Current Reality
The card network giant processes transactions for over 3.16 billion consumer and commercial cardholders. Within this ecosystem, Mastercard chargebacks represent a growing challenge driven by four key factors.
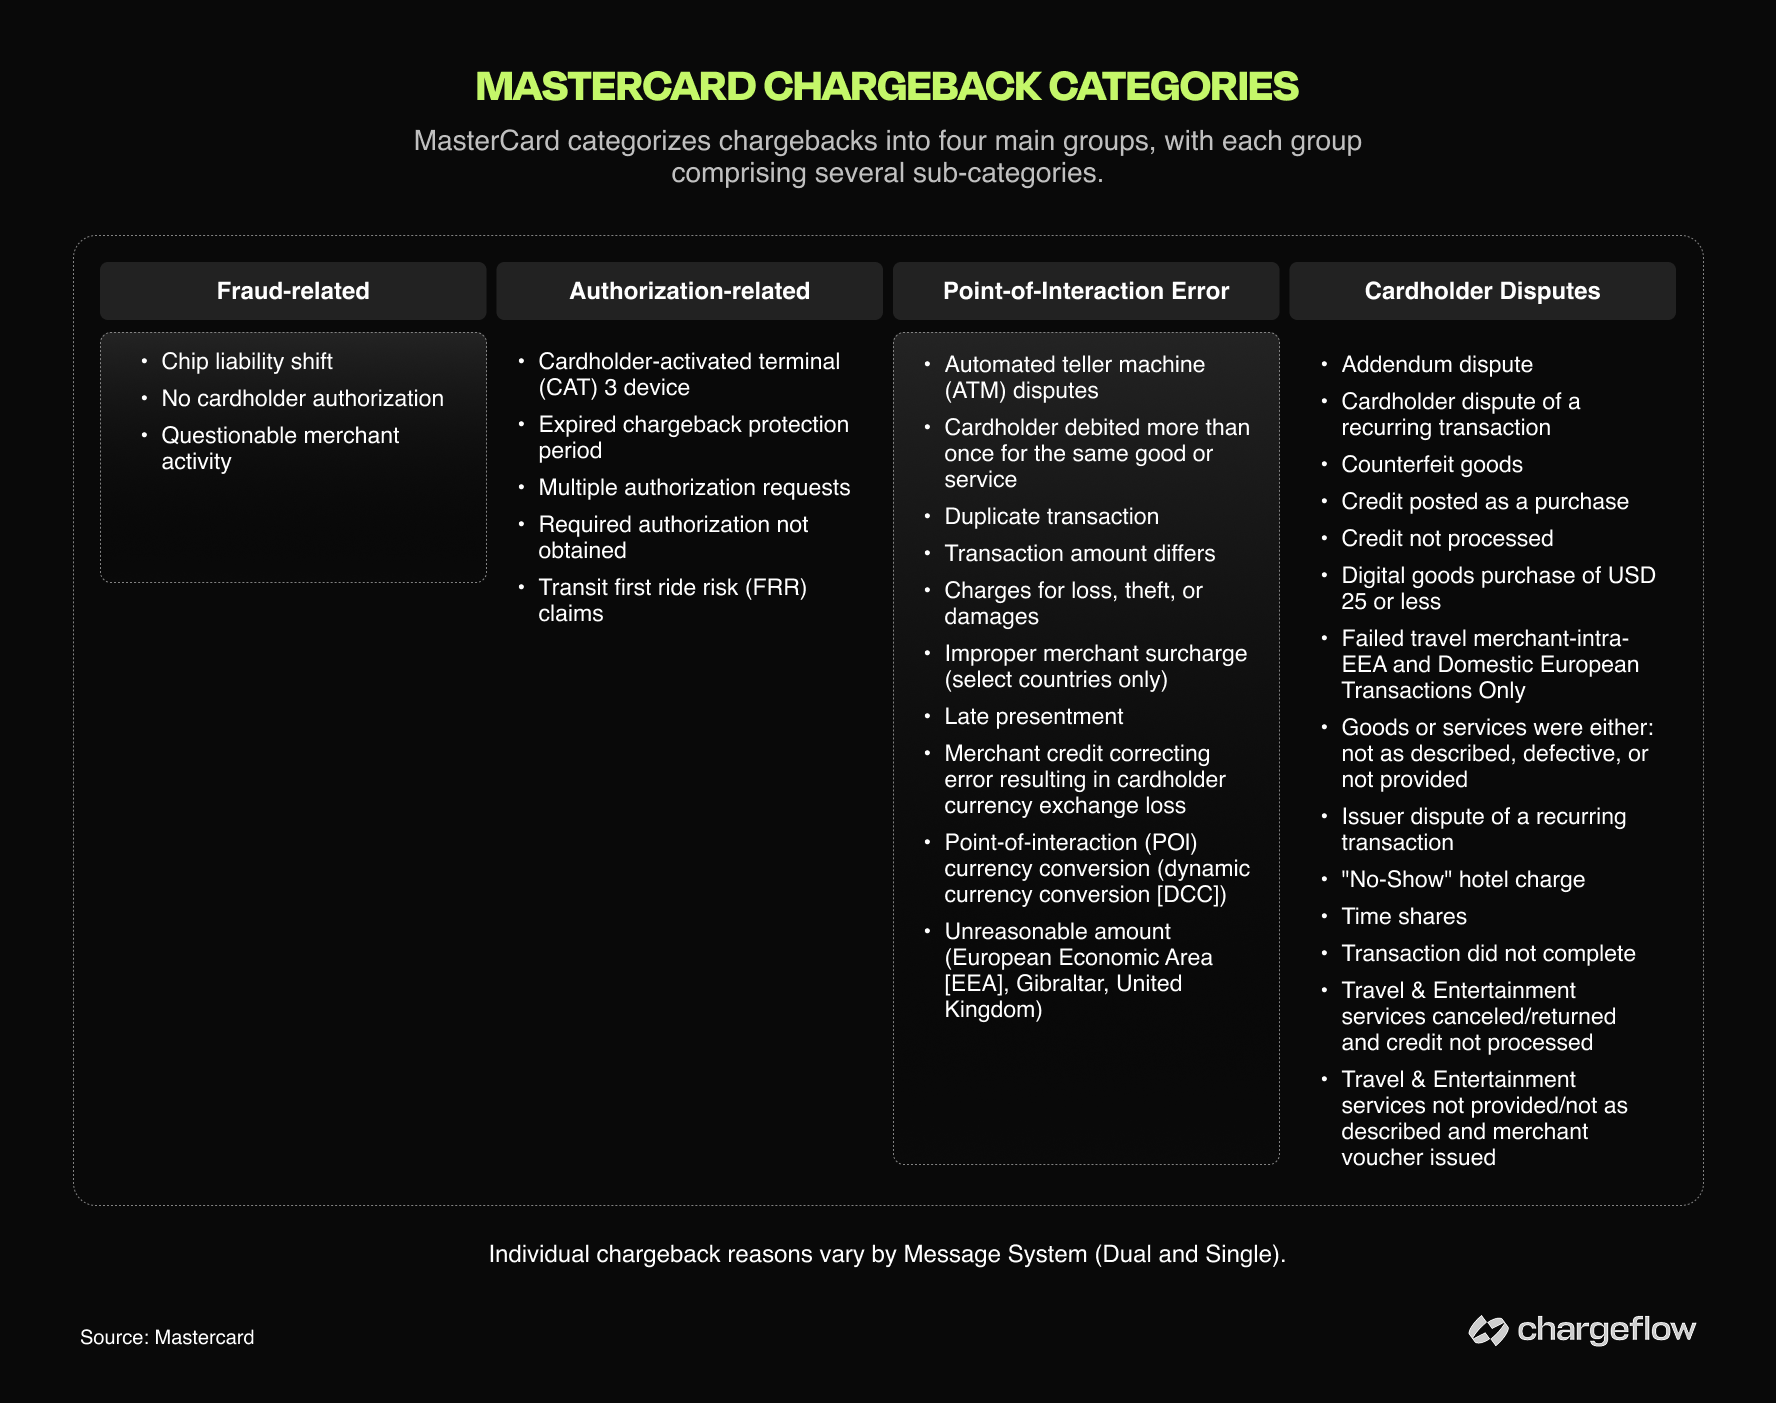
- Regulatory Environment: Mastercard's consumer-friendly dispute policies have lowered barriers to filing chargebacks. Mobile banking apps now allow disputes with just a few taps, contributing to friendly fraud, where cardholders dispute legitimate transactions.
- Surge in Card-Not-Present (CNP) Transactions: In 2024, 63% of global transactions occurred in CNP environments (37% online and 26% in mobile apps), according to Datos Insights. This shift has made CNP fraud the leading cause of chargebacks across all merchant categories.
- Evolving Fraud Tactics: Cybercriminals increasingly use AI-powered attacks, including account takeovers and synthetic identity fraud. Traditional rule-based fraud systems struggle to adapt, resulting in higher fraud rates and subsequent chargebacks.
- Management Gap: Many merchants, especially small and medium enterprises, still handle chargebacks reactively through manual processes or simply accept them as a cost of business.
What a Mastercard Chargeback Actually Costs You
Mastercard's own research quantifies the damage:
- The average chargeback costs merchants $128 all-in: $82 in internal handling plus $46 in third-party fees (Mastercard and Javelin, 2026).
- Global chargeback value is forecast to grow from $36.9 billion in 2026 to $46.1 billion by 2029 (Datos Insights).
- 48% of consumers admit they have disputed a legitimate charge at least once (Datos Insights, 2026).
- Average dispute amounts by sector: travel $120, high-risk verticals $99, retail $84, digital goods $77, subscriptions $69 (Mastercard, 2025).
Industry Impact by Sector
Our recent chargeback statistics find that different industries face distinct chargeback challenges:
- eCommerce & Retail: Primary challenges include friendly fraud (40-75% of chargebacks) and delivery disputes.
- Average chargeback rate: 0.65-1.2%
- Digital Services & SaaS: Subscription-related disputes dominate Mastercard chargebacks for SaaS verticals, often from forgotten recurring billing or unclear cancellation policies.
- Average chargeback rate: 0.3-1.8%
- Travel & Hospitality: Cancellation disputes and service quality issues drive most chargebacks for the travel and hospitality industry.
- Average chargeback rate: 0.8-1.5%
- Financial Services: Account takeover fraud and unauthorized transaction disputes are primary concerns for the financial industry.
- Average chargeback rate: 0.3–0.8%
With that context in mind, let's now explore Mastercard's chargeback process and learn how to respond effectively.
A Complete Breakdown of the Mastercard Chargeback Process
Mastercard chargebacks follow a multi-phase process with several structured steps. These cycles include First Chargeback (Issuer Initiated), Second Presentment (Merchant Response), Pre-Arbitration, Arbitration, and Ruling/Appeal stages. Each phase has specific timelines, requirements, and fee structures.
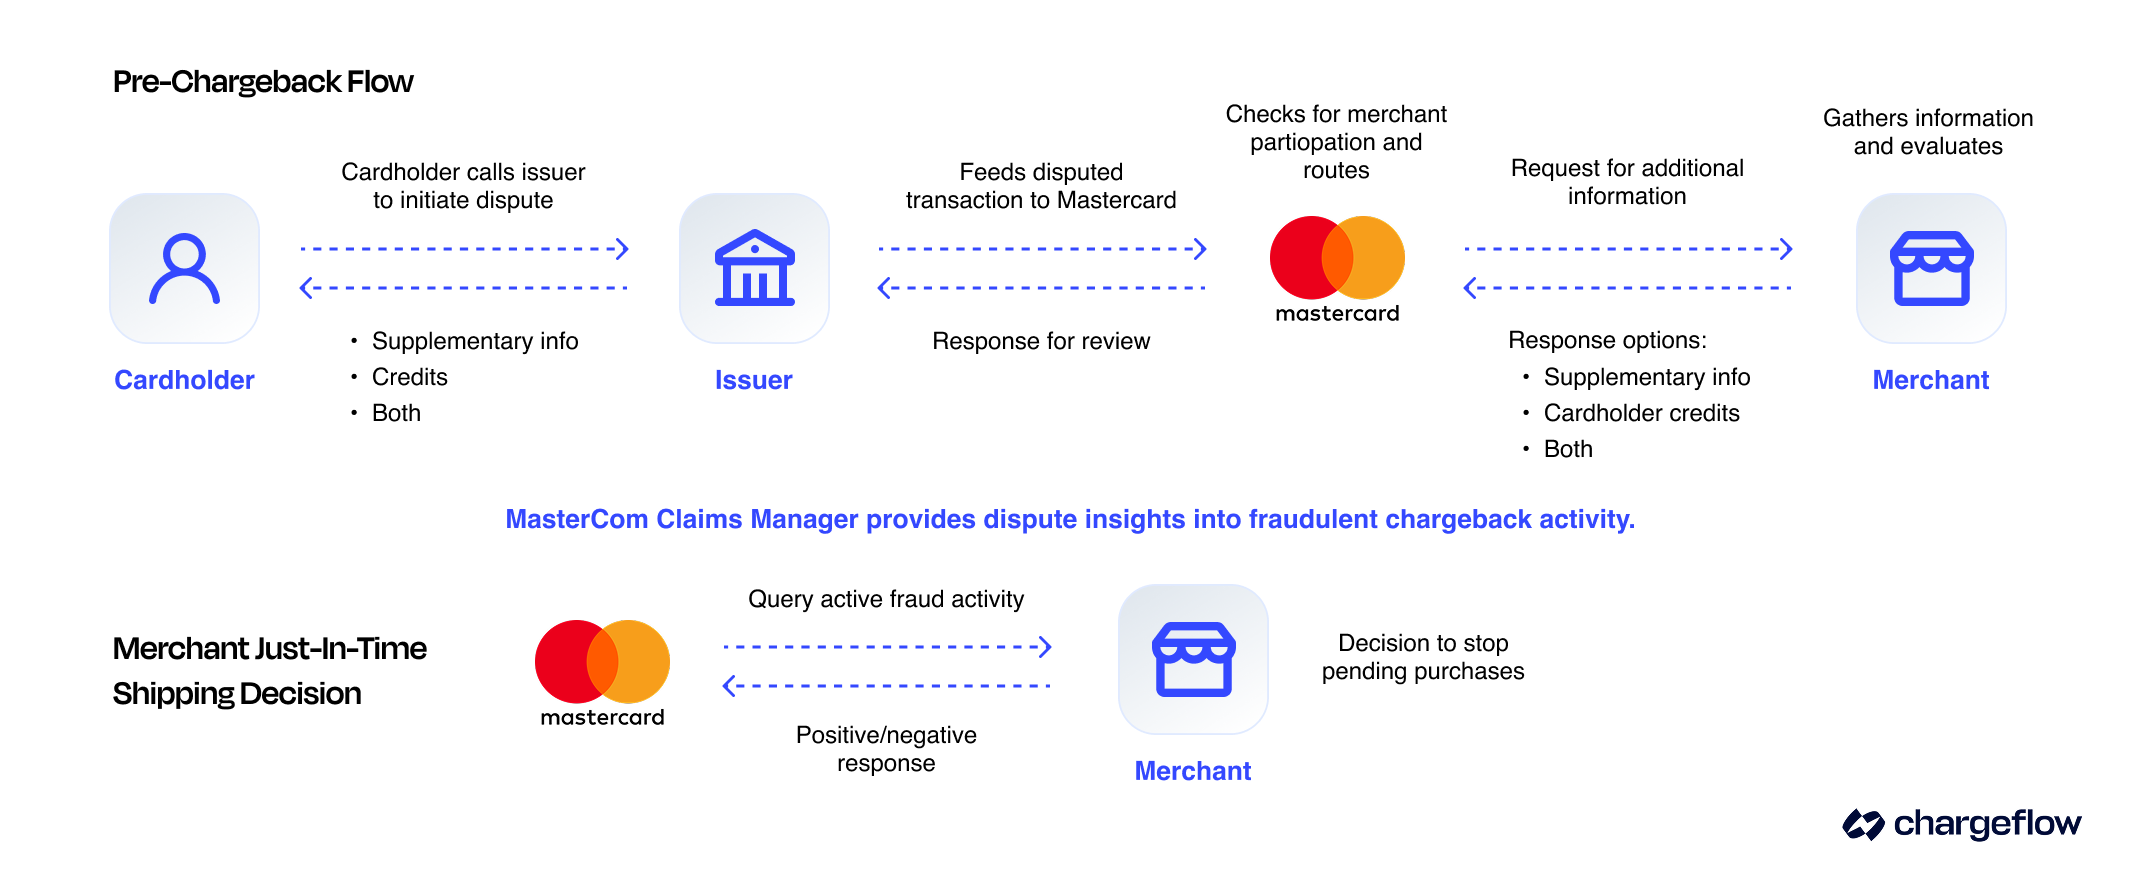
Phase 1: First Chargeback (Issuer Initiated)
Timelines:
- Cardholders: 120 days from the transaction date for most cases (90 days for certain authorization and point-of-interaction categories).
- Merchants: 45 days from dispute day one for representment.
Process:
Step 1: First Chargeback: When a cardholder disputes a transaction, the card issuing bank (issuer) evaluates the claim against Mastercard’s Chargeback Guide (e.g., valid reason code). If valid, the issuer initiates a chargeback and debits the transaction amount from the acquirer, crediting it provisionally to the cardholder.
- The issuer provides the acquirer with the dispute reason code and any supporting documentation.
- The acquirer notifies the merchant, who must decide whether to accept the chargeback or contest it.
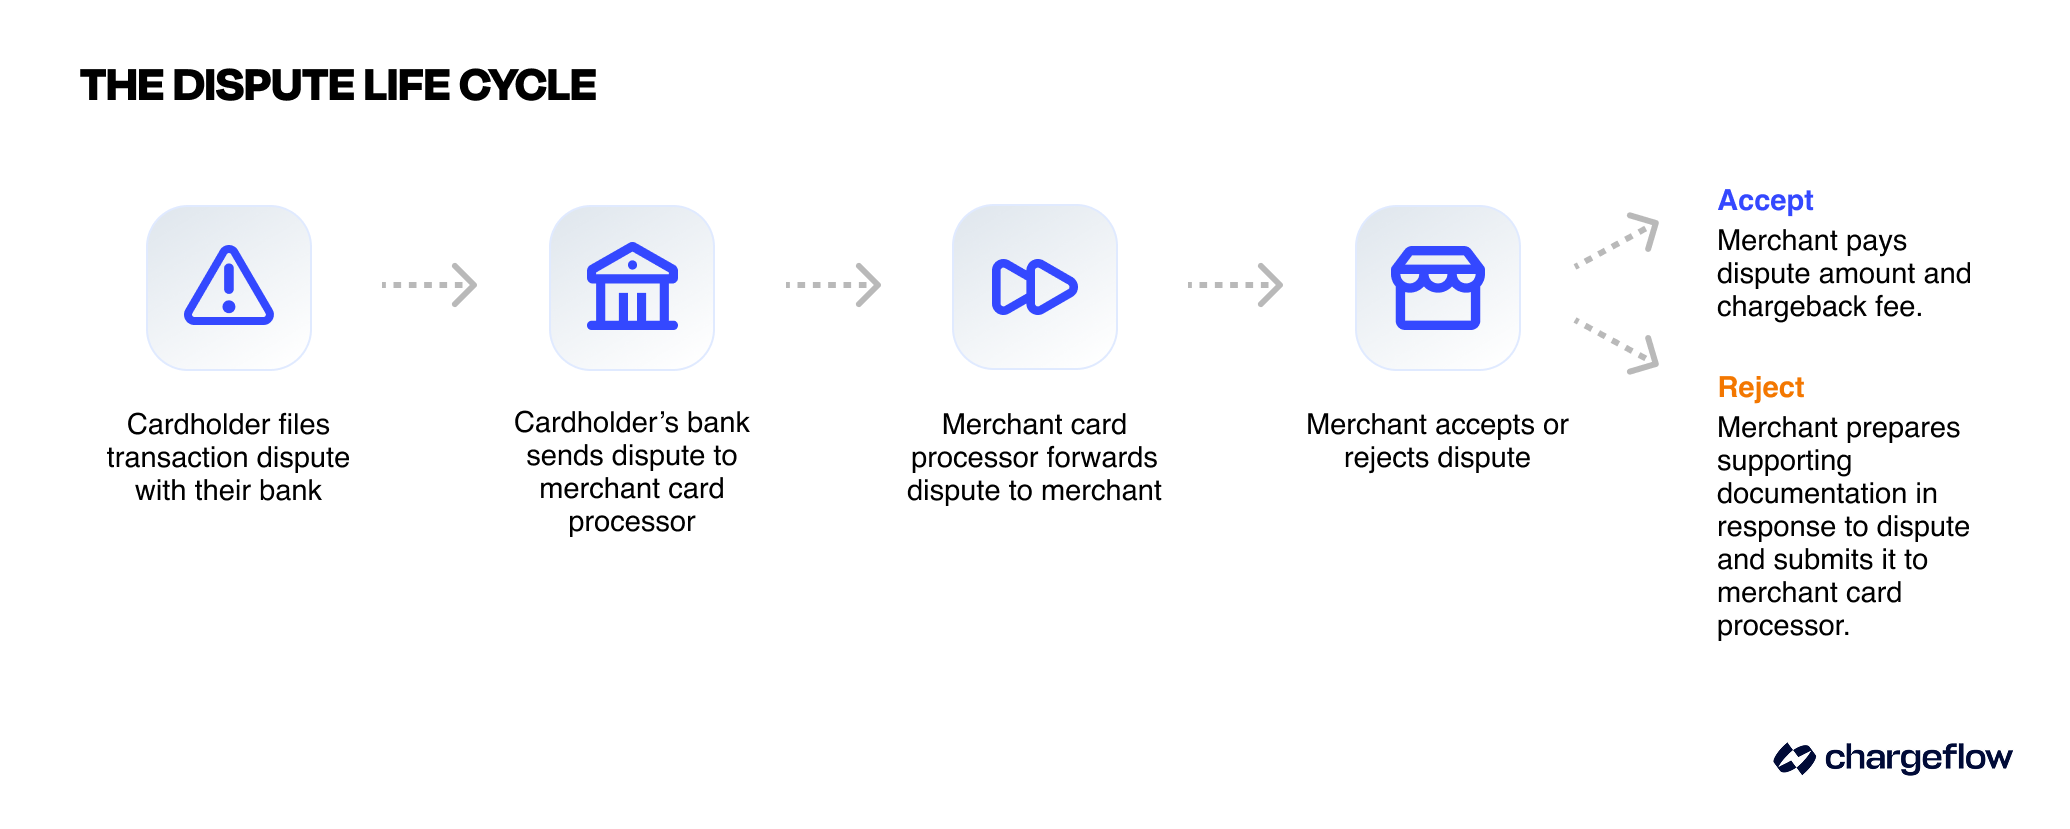
Step 2: Second Presentment (Merchant Rebuttal): If you, the merchant, choose to challenge the chargeback, you must submit a representment. The acquirer submits your evidence back to the issuer, who may:
- Accept the second presentment, taking financial responsibility; or
- Reject it, escalating the case to pre-arbitration if they believe the merchant's response is insufficient.
- Fee: No direct Mastercard fees, but acquirers typically charge $15-$25 per chargeback, sometimes more depending on your risk level or agreement.
Success Rates by Evidence Quality:
- High-quality, reason-code-specific evidence with manual approaches: 8.1-20% win rates.
- Automated evidence compilation (with platforms like Chargeflow): up to 80% win rate.
Common Mastercard Chargeback Evidence Requirements by Reason Code
Below are standard evidence requirements for winning chargeback representment on common Mastercard reason codes:
| Reason Code | Dispute Type | Winning Evidence |
|---|---|---|
| 4837: No Cardholder Authorization | Fraud | AVS/CVV match, IP address, device fingerprint, delivery confirmation |
| 4863: Cardholder Does Not Recognize | Fraud | Clear billing descriptor, proof of customer interaction |
| 4855: Goods/Services Not Provided | Item not received | Signed delivery receipt, tracking, proof of digital access/download |
| 4853: Defective / Not as Described | Cardholder dispute | Product description, QC records, customer comms, refund offers |
| 4841: Canceled Recurring Billing | Subscription | Service terms, cancellation policy, proof customer did not cancel in time |
| 4808: Authorization-Related Chargeback | Authorization | Authorization approval code, authorization logs, settlement records |
| 4834: Point-of-Interaction Error | Processing error | Receipts proving a single charge, correct amount, and correct currency |
Note on legacy codes: Mastercard has consolidated most cardholder dispute codes (4841, 4855, 4859, 4860) under 4853 Cardholder Dispute and most fraud scenarios under 4837, so older codes still appear on legacy cases and some processor dashboards. Filing windows also vary by code: 4837 and 4853 carry 120-day windows (4853 extends up to 540 days from processing when delivery or services were delayed), while authorization and point-of-interaction codes (4808, 4834) are capped at 90 days. See the full Mastercard chargeback reason codes list for every current and legacy code.
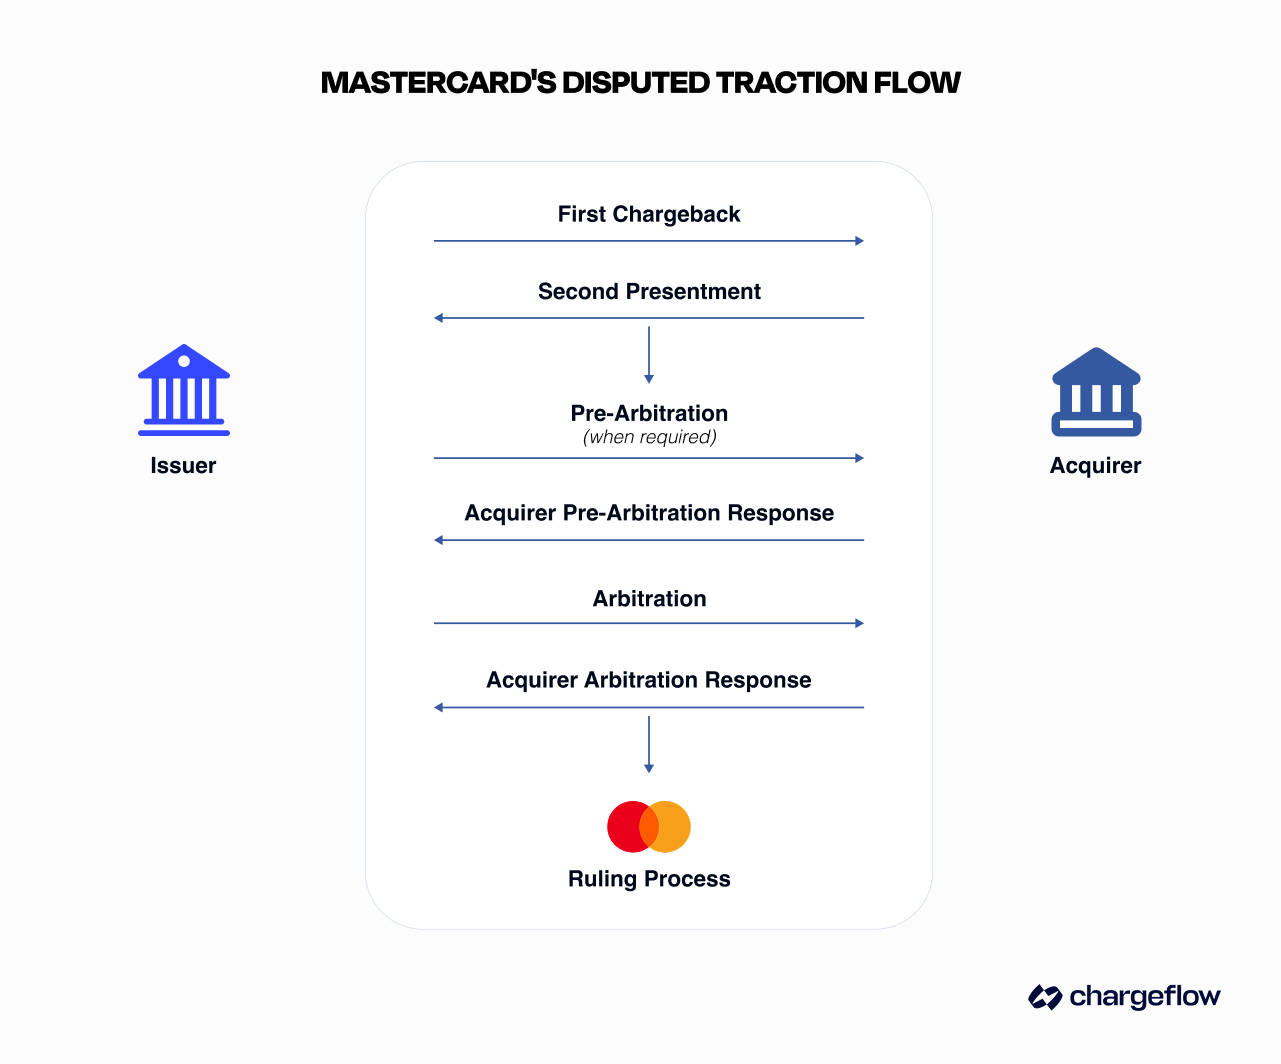
Phase 2: Pre-Arbitration (Second Chargeback)
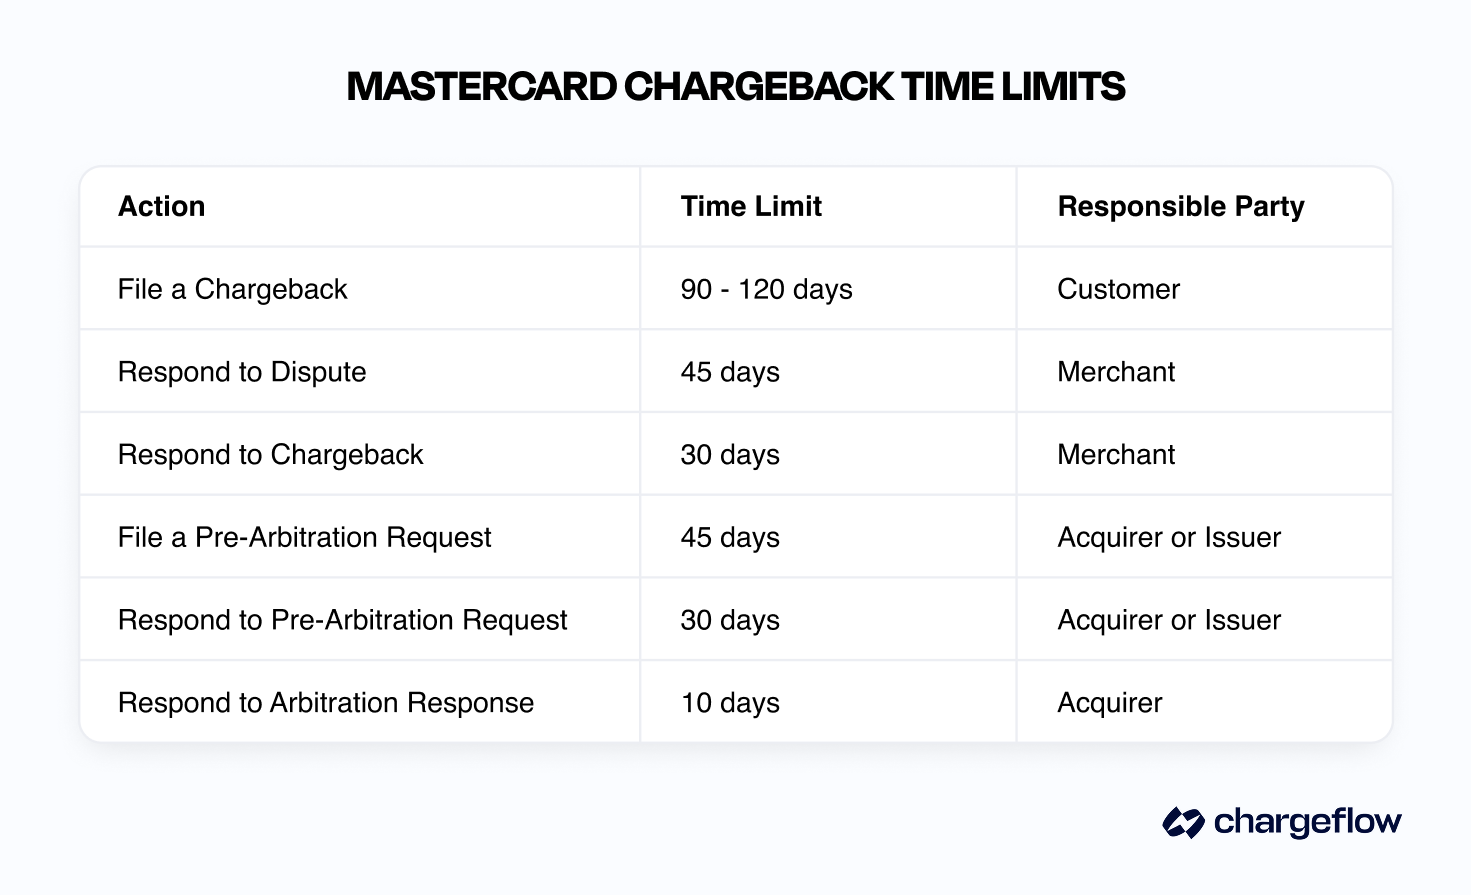
Timeline: The issuer has 45 days to file pre-arbitration; the merchant then has 30 days to challenge it (and loses automatically if no response is filed).
Process:
- Step 1: Issuer Pre-Arbitration Filing: The issuer may initiate a pre-arbitration (second chargeback) case if it disagrees with the second presentment outcome. This step must be justified with new or additional information explaining why the prior response was invalid.
- Step 2: Acquirer Response to Pre-Arbitration: The acquirer can:
- Accept the case, assuming financial responsibility (Mastercard adjusts funds accordingly),
- Reject the case with a rebuttal and evidence,
- Or take no action, in which case Mastercard automatically assigns financial liability to the acquirer 30 calendar days after submission.
Either party may voluntarily accept financial liability before Mastercard's ruling.
- Fees:
- Filing fee: $15 (Same as the chargeback fee)
💡Pro Tip: Pre-arbitration cases have lower merchant win rates due to increased scrutiny. Cost-benefit analysis becomes critical at this stage.
Phase 3: Arbitration
Timeline: 15 days for acquirer response after issuer filing.
If the acquirer rejects pre-arbitration, the issuer may escalate the case to chargeback arbitration. Arbitration is rare due, in part, to high costs. Arbitration chargeback follows the process below:
- Step 1: Issuer Arbitration Filing: The issuer submits a case to Mastercard's Dispute Resolution Management (DRM) team, including all supporting evidence and an explanation for why the chargeback should be upheld.
- Step 2: Acquirer Arbitration Response: The acquirer may:
- Accept financial liability (at any time before ruling),
- Reject the arbitration case with a rebuttal (within 15 days),
- Or take no action, in which case, 10 calendar days after submission, Mastercard automatically proceeds to review it for ruling.
- Step 3: Mastercard Ruling: The Mastercard DRM team evaluates procedural compliance, evidence merit, and applicable rules. DRM team ruling:
- Determines financial liability,
- Issues adjustments through the Mastercard Consolidated Billing System (MCBS),
- Assesses applicable fees. This process is completed within 10 days from the arbitration case filing submission date.
- Fees:
- Filing fee: $150
- Administrative fee: $250
- Technical violation fee: $100 (losing party)
- Withdrawal fee: $150 (if withdrawn before DRM review)
💡Pro Tip: Arbitration strongly favors issuers due to cumulative evidence requirements and procedural complexity.
Phase 4: Appeal Process
Timeline: 45 days from ruling to file an appeal.
The party held financially liable may submit a written appeal to Mastercard. Appeals must include a valid reason for reconsideration and new or overlooked evidence. Mastercard's decision on the appeal is typically final.
Fee: $500
💡Pro Tip: Appeal ruling reversals have less than 10% success rates for merchants.
Mastercard vs. Visa Chargeback Rules: Key Differences
If you built your dispute workflow around Visa and reuse it for Mastercard, you will miss deadlines and lose winnable cases. The networks run structurally different processes:
| Rule | Mastercard | Visa |
|---|---|---|
| Merchant response window | 45 days for second presentment | 30 days to respond to a dispute |
| Escalation path | One cycle: chargeback, second presentment, pre-arbitration, arbitration via Mastercom | Two workflows: Allocation (fraud/authorization, liability auto-assigned) and Collaboration |
| Fraud dispute gate | First-Party Trust data is weighed before a 4837 fraud dispute is filed | Compelling Evidence 3.0 shifts liability when two prior undisputed transactions match |
| Monitoring program | ECM: 100-299 chargebacks and 1.5% ratio; HECM: 300+ and 3% | VAMP: 1,500+ combined fraud and dispute transactions and 1.5% ratio (replaced VDMP/VFMP in 2025) |
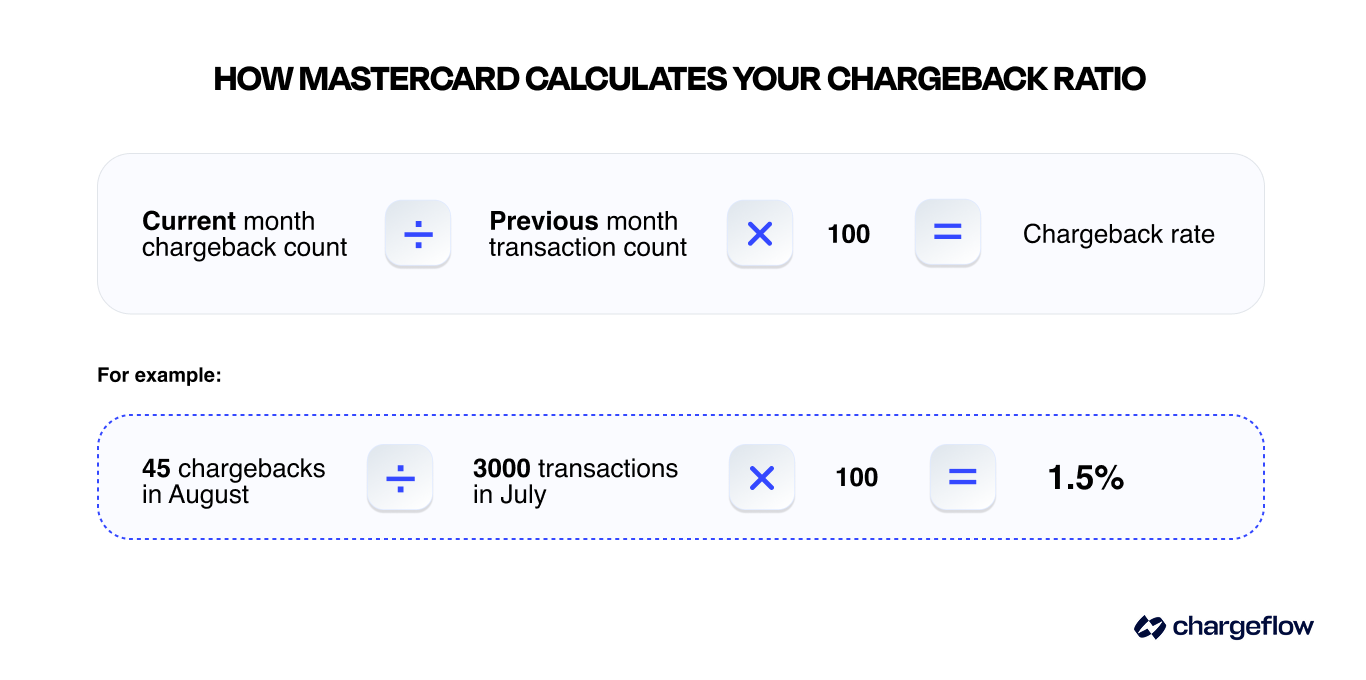
| Ratio math | This month's chargebacks divided by last month's sales count | This month's combined fraud and dispute count (VAMP) divided by this month's settled transaction count |
| Pre-dispute network tool | Ethoca Alerts (Mastercard-owned) | Verifi CDRN and RDR (Visa-owned) |
The practical takeaway: Mastercard gives you 15 extra days to respond, but its prior-month ratio math means a single bad sales month can spike your ratio even when chargeback counts stay flat.
Evidence-Based Mastercard Chargeback Prevention Strategies
Winning against Mastercard chargebacks starts before a dispute ever occurs. By using data instruments and applying proven fraud prevention tactics, you can stop avoidable losses and strengthen your defense when challenges arise.
Below are vital strategies worth implementing:
Tier 1: Fundamental Fraud Prevention
- 3D Secure 2.0 implementation
- Function: Adds an authentication layer for CNP transactions
- Impact: Reduces fraud-related Mastercard chargebacks by up to 60%.
- Liability Shift: Qualified transactions shift liability to the card issuer.
- Implementation Cost: Generally priced at $0.05-0.15 per transaction
- ROI Timeline: 3-6 months for most merchants
- AVS and CVV Verification
- Function: Validates billing address and card verification value
- Impact: An estimated 35-45% reduction in fraud-related reason codes when combined with tools like chargeback alerts
- Requirements: Essential for Visa Compelling Evidence 3.0 compliance
- Cost: Typically included in payment processing fees
- Address Verification Services (AVS) Response codes:
- Full match (Y): Process normally
- Partial match (A, Z, W): Enhanced review recommended
- No match (N): High-risk transaction, consider declining
Tier 2: Advanced Risk Management
- Machine Learning Fraud Detection: Modern fraud detection systems analyze hundreds of data points in real time to pinpoint anomalies through:
- Transaction velocity checks: Multiple transactions from the same source
- Device fingerprinting: Hardware and software characteristics
- Behavioral analysis: Deviation from normal purchasing patterns
- Geolocation verification: IP address vs. billing address analysis
- Tokenization for Stored Payment Data
- Function: Replaces sensitive card data with unique tokens
- Impact: Eliminates stored data breach risks
- Compliance: Required for PCI DSS Level 1 merchants
- Implementation: Work with your payment processor or third-party vendor.
Tier 3: Customer Experience Overhaul
If you're using tools like Insights, a free service from Chargeflow, you can easily get a bird's-eye view of chargeback sources. Frequent chargebacks could point to service issues, informing optimization procedures. Below are standard customer service optimization strategies:
- Clear Billing Descriptors: Confusing merchant names cause about 25% of "unrecognized transaction" chargebacks. Best practices include:
- Use a recognizable business name
- Include contact information
- Match marketing/website branding
- Avoid excessive abbreviations or codes
- Example Improvements:
- Poor: "SVC*MRK 4127749021"
- Better: "SKYE STORE 555-123-4567"
- Best: "SKYE OUTDOOR GEAR 555-123-4567"
- Proactive Customer Communication
- Order confirmations: Immediate email with transaction details
- Shipping notifications: Real-time tracking information to avoid uncertainties that cause "transaction not received" chargebacks
- Subscription reminders: Pre-billing notifications for recurring billing charges.
Mastercard-Only Prevention Levers: Ethoca Alerts and First-Party Trust
Two programs exist only on the Mastercard network, and most merchants use neither.
Ethoca Alerts. Mastercard has owned Ethoca since 2019, making it the network's own pre-dispute channel. Participating issuers push confirmed fraud and dispute signals to merchants, typically within hours of the cardholder complaint, so you can refund or halt fulfillment before the case becomes a chargeback that counts toward your ECM ratio. Chargeflow Alerts taps this network (alongside Visa's Verifi) with pay-per-alert pricing.
First-Party Trust. Launched in the United States in 2024 (Mastercard announced the program in October 2023, with the US rollout following in 2024), this program attacks disputes where the cardholder made the purchase but claims fraud anyway. You share device identity (IP address, device ID), proof of delivery, and identity signals at authorization or pre-dispute; Mastercard validates them against the cardholder's prior transactions and puts the findings in front of the issuer before a 4837 fraud dispute can be filed. Ethoca research found that 75% of fraud experienced by online businesses is first-party (Mastercard, 2025), which makes this the single highest-leverage program for eCommerce merchants.
Industry-Specific Chargeback Prevention Implementation Framework
There are no one-size-fits-all chargeback prevention strategies. Merchants often make the mistake of deploying a blanket framework when seeking chargeback prevention. That's counter-productive because each business is unique.
Below are some sector-specific implementation recommendations to consider.
eCommerce and Retail
- Priority Chargeback Prevention Areas:
- Package delivery disputes
- Product not as described
- Friendly fraud
- Recommended Implementation Sequence:
- Month 1-2: Foundation
- Implement 3D Secure 2.0 for transactions >$50
- Update billing descriptors
- Establish delivery confirmation protocols
- Integrate a chargeback alert system
- Install Chargeflow Insights for customer-specific issues
- Month 3-4: Enrichment
- Deploy machine learning fraud detection
- Implement real-time order tracking
- Create customer service escalation procedures
- Month 1-2: Foundation
- Expected Results: 60-80% reduction in preventable Mastercard chargebacks within six months. You can pair this strategy with chargeback automation for complete coverage.
Subscription and SaaS Businesses
- Priority Chargeback Prevention Areas:
- Recurring billing disputes
- Service cancellation issues
- Free trial conversion disputes
- Critical Implementation Elements
- Subscription Management:
- Clear cancellation processes (maximum 3 clicks)
- Immediate cancellation confirmations
- Pause/downgrade options before cancellation
- Pre-billing email notification (7 days, 1 day before charge)
- Trial Period Best Practices:
- Explicit consent for trial-to-paid conversion
- Multiple conversion notifications
- Simple trial extension options
- Clear and accessible trial terms at signup
- Subscription Management:
- Implementation Timeline: 2-3 months for full deployment
- Expected Impact: Up to 90% reduction in subscription-related Mastercard chargebacks, if complemented with a chargeback alert.
Travel and Hospitality
- Priority Chargeback Prevention Areas:
- Cancellation policy disputes
- Service quality complaints
- Booking modification issues
- Recommended Niche-Based Solutions:
- Dynamic pricing transparency
- Flexible rebooking policies
- Real-time availability updates
- Comprehensive booking confirmations
- Proactive service recovery protocols
- Expected Results: 50-60% reduction in service-related chargebacks, with an estimated 80% reduction if supported with chargeback alerts.
“Card-not-present fraud is driving sustained demand for chargeback and fraud prevention tools. Consumers increasingly prefer chargebacks over direct merchant refunds, with 84% finding chargebacks simpler to process.” (Ariel Chen, Chargeflow co-founder and CEO)
Advanced Compliance and Risk Management
One key compliance challenge for merchants is high chargeback ratios, which threaten their merchant accounts. Whether you operate a small or large enterprise, understanding this challenge and implementing the recommended solutions can save you so much trouble.
Mastercard monitors merchants' chargeback-to-transaction ratios under its Excessive Chargeback Merchant (ECM) program. Exceeding thresholds can trigger fines or even account termination. Many processors enforce stricter internal limits to reduce risk exposure and maintain network compliance. Separately, Mastercard's Mastercard GMAP program conducts direct merchant audits rather than tracking chargeback ratios.
Mastercard Monitoring Program Thresholds
Mastercard's Excessive Chargeback Program (ECP) has two tiers, and a merchant must exceed both the count and the ratio in a month to be flagged (per Mastercard program rules as published by acquirers, including PayPal Braintree and JPMorgan):
- How the ratio is calculated: this month's chargeback count divided by last month's transaction count (June chargebacks / May sales).
- Excessive chargeback merchant (ECM): 100 to 299 chargebacks per month AND a 1.5% to 2.99% chargeback ratio.
- High excessive chargeback merchant (HECM): 300+ chargebacks per month AND a 3%+ ratio, plus a $5 issuer recovery assessment per chargeback.
ECP Program Consequences for Merchants
Breaching any of the stated thresholds has specific consequences for merchants, such as the following:
- Tier 1: Monthly Monitoring and Reporting Burden
- Mastercard enrolls merchants exceeding ECM or HECM thresholds in the ECP program.
- Merchants in Tier 1 ECP must submit a remediation plan to reduce chargebacks and provide monthly progress reports.
- Tier 2: Monthly Fines
- After two months in the ECP, fines apply and escalate as follows:
- Months 2-3: $1,000 (ECM) or $1,000-$2,000 (HECM)
- Months 4-6: $5,000 (ECM) or $10,000 (HECM)
- Months 7-11: $25,000 (ECM) or $50,000 (HECM)
- Months 12+: $50,000-$100,000 (ECM) or $100,000-$200,000 (HECM)
- Additional chargeback fees may apply.
- After two months in the ECP, fines apply and escalate as follows:
- Tier 3: Account Termination
- After 12+ months without reducing Mastercard chargebacks below 100 or a 1.5% chargeback rate, the acquirer may terminate your merchant account.
- Your business may equally be added to a MATCH list, blocking a new Merchant ID.
How to Exit the Mastercard Excessive Chargeback Program
Merchants can only exit the ECP by maintaining chargeback levels below the ECM threshold (100 chargebacks) for three consecutive months. Below are some recommended best practices for achieving that objective.
- Track incoming chargebacks
- Use real-time analytics to monitor chargeback ratios.
- Address root causes such as product quality issues, shipping delays, or confusing billing descriptors.
- Refund and cancel problematic transactions
- A chargeback alert notifies you of impending disputes and allows proactive refunds when necessary to prevent escalation.
- You can also block and blacklist problematic customers when necessary.
💡Pro Tip: Merchants using real-time analytics and alerts see a significant reduction in chargeback rates. This Stripe Case Study showcases how Wordtune, an AI writing assistant service, achieved a 33.5% reduction in fraudulent disputes and a 29.7% reduction in dispute rate within five months.
Chargeback Fraud Management Vendor Evaluation Framework
Shopping occurs across multiple channels, including QR codes, mobile apps, Social Media live streams, online, and in person. Many transactions involve third-party intermediaries, like travel booking apps, rather than directly with the service provider.
This omni-channel environment complicates chargeback management evidence collection due to fragmented data and delayed access to critical transaction records.
Hence, selecting a chargeback fraud prevention vendor is a weighted decision. Choosing the wrong solution may result in submitting incorrect evidence or experiencing high false positives, which can cause legitimate customers to be treated as fraudsters. If you're weighing dedicated dispute platforms, it helps to compare options directly, for example, Chargeflow vs Disputifier and Chargeflow vs Chargeblast.
Here are some vendor selection metrics to consider:
Core Functionality Assessment:
- Dispute prevention capabilities: Fraud detection, alert system, customer tools
- Chargeback recovery services: Automated representment, evidence compilation
- Analytics and reporting: Real-time dashboards, trend analysis
- Integration ease: API quality, setup time, ongoing maintenance
Vendor Comparison Matrix:
- Fraud Detection and Prevention Specialists:
- Recommended: Sift, Kount, Riskified
- Strengths: Advanced Machine Learning, real-time fraud scoring
- Weaknesses: Limited chargeback recovery services, especially in cases involving friendly fraud
- Payment Processor Solutions:
- Recommended: Stripe Radar, PayPal Fraud Protection
- Strengths: Smooth integration, competitive pricing
- Weaknesses: Platform-specific fraud coverage, limited customization, and compelling evidence collection and submission.
- Full-Service Platforms:
- Recommended: Chargeflow, Mitigator, Chargeback Gurus
- Strengths: End-to-end coverage, specialized expertise, set it and forget it
- Weaknesses: Higher cost, false negatives, partial tools, and integration complexity depending on the platform you choose.
- Platform Selection Criteria Weighting:
- Effectiveness: 35% (win rates, prevention success)
- Cost-effectiveness: 25% (ROI, total cost of ownership)
- Integration ease: 20% (setup time, maintenance requirements)
- Support quality: 15% (expertise, responsiveness)
- Scalability: 5% (growth accommodation for various models, feature expansion)
Cost/Benefit Analysis: Manual/Outsourced vs. Automated Chargeback Management
According to Mastercard, merchants and issuers are progressively embracing automated chargeback management (Mastercard 2025 State of Chargebacks Report, p. 5 & 20). This cost/benefit analysis throws more light on the reason for that development.
Manual Process Characteristics:
- Average time investment: 2-4 hours per case
- Typical dispute win rate: 8-20%
- Cost per case: $50-100 (including staff time)
- Scalability: Maximally limited to 10-20 cases per week per person.
Automated Process Characteristics:
- Average processing time: ~20 minutes per case
- Typical win rate: 45-80%
- Cost per case: 25% per recovered chargeback (Chargeflow pricing)
- Scalability: Unlimited (with Chargeflow)
ROI Calculation Example:
For a merchant with 100 chargebacks per month, here’s how their ROI stacks up between manual and automated chargeback management:
- Manual processing cost: $8,000/month + $60,000 in lost revenue
- Automated processing cost: $2,500/month + $25,000 in lost revenue (depending on the platform chosen)
- Net monthly savings: $40,500
- Annual savings: $486,000
💡Pro Tip: Many chargeback solutions offer partial tools, such as alerts or manual recovery, leaving merchants to piece together evidence across platforms. Choosing the right solution, especially one like Chargeflow that offers complete coverage with a 4X ROI guarantee, makes all the difference.
Key Performance Indicators (KPIs)
If you’re seeking to exit the Mastercard ECP program, you must target essential KPIs that fast-track your objectives. Below are some examples to consider.
Primary Metrics:
- Chargeback Ratio: Target <0.5 for most industries
- Dispute Win rate: Target 45-65% for representments
- Cost Per Chargeback: Target reduction of at least 50%
- Prevention Rate: Target at least 60% of preventable chargebacks
Secondary Metrics:
- Customer Satisfaction: Track the impact of chargeback fraud prevention on legitimate customers and ensure positive outcomes.
- Payment Authorization Rates: Ensure fraud prevention does not reduce legitimate approvals.
- Payment Processing Speed: Maintain <2-second transaction processing times.
- False Positive Rate: Target <5% for fraud prevention systems.
Case Study: Obvi’s 170% Win-Rate Boost with Automation
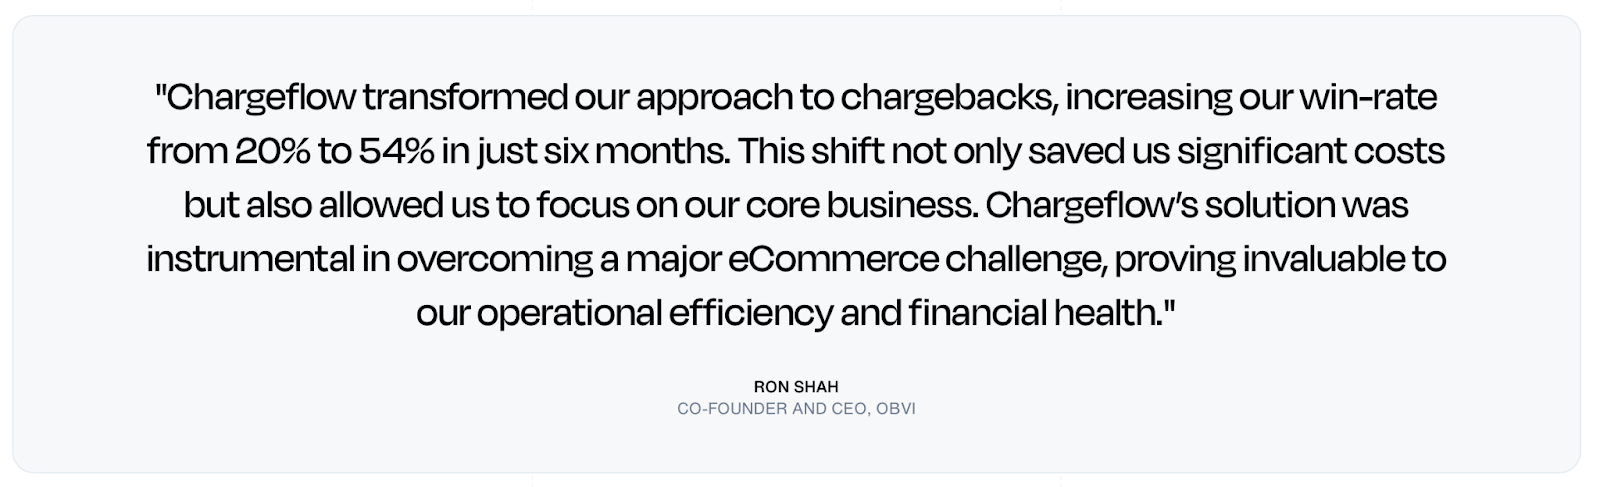
Obvi is a fast-growing eCommerce company in the competitive health and wellness supplement industry. The omnichannel vendor has achieved $40 million in revenue as of 2023, serving 200,000+ customers across over 75 countries. Despite its success, Obvi faced growing chargeback rates due to friendly fraud.
The manual process of handling chargebacks (via a freelancer or customer support) was time-intensive, costly ($40 per case), and yielded a low 20% win rate. This resulted in significant revenue losses.
Solution:
Obvi automated chargeback management with Chargeflow, a platform known for handling chargebacks from start to finish. This shift yielded immediate results.
Results:
- 54% Win Rate
- $10,427 Recovered In Lost Revenue
- 170% Increased Win Rate
- Increased Customer Satisfaction
Products Used:
- Chargeback automation
- Alerts
- Insights
Mastercard Chargeback FAQs
How long does a merchant have to respond to a Mastercard chargeback?
Merchants generally have 45 days from dispute day one to submit a representment (second presentment). If the case escalates to pre-arbitration, you have 30 days to challenge it or you lose automatically.
How long do cardholders have to file a Mastercard chargeback?
Cardholders typically have 120 days from the transaction date, though some authorization and point-of-interaction categories carry a shorter 90-day window.
What are Mastercard's ECM and HECM thresholds?
The Excessive Chargeback Merchant (ECM) tier is 100 to 299 chargebacks per month combined with a 1.5% to 2.99% chargeback ratio; the High Excessive (HECM) tier is 300+ chargebacks combined with a 3%+ ratio. Both the count and the ratio must be exceeded, and fines escalate monthly.
What evidence wins a Mastercard fraud chargeback?
For reason code 4837 (no cardholder authorization), submit AVS/CVV match results, IP address, device fingerprinting, and delivery confirmation. For 4863 (does not recognize), a clear billing descriptor and proof of customer interaction usually win.
How does a Mastercard chargeback work?
The issuer debits your acquirer and credits the cardholder as soon as it accepts the dispute. Your acquirer notifies you, and you either accept the loss or fight it with a second presentment within 45 days. If the issuer rejects your evidence, the case can escalate to pre-arbitration and then arbitration, where Mastercard itself rules and the losing party pays the case fees.
How does a cardholder file a chargeback on a Mastercard?
Cardholders never contact Mastercard directly. They dispute the charge with their issuing bank (via app, phone, or online banking), and the bank files the chargeback through Mastercom, Mastercard's dispute platform. That is why your best defense starts before the bank: clear billing descriptors, fast support, and pre-dispute alerts.
What is the success rate of a Mastercard chargeback?
For cardholders, most fraud-coded disputes end in at least a provisional credit. For merchants, manual representment wins roughly 8-20% of cases, while automated, reason-code-specific evidence pushes win rates toward 80%. Chargeflow's network average sits near 75% across 20,000+ merchants.
What reasons qualify for a Mastercard chargeback?
Every Mastercard chargeback must fit one of four reason code families: fraud (4837, no cardholder authorization), cardholder disputes (4853: goods not received, defective, canceled recurring billing, credit not processed), authorization errors (4808), and point-of-interaction errors (4834: duplicate charge, wrong amount).
Build a Systemic Approach to Mastercard Chargeback Management
Effective Mastercard chargeback management requires a systemic approach that combines prevention, early detection, and strategic recovery efforts. Industry records and our internal data clearly show that merchants implementing comprehensive chargeback management programs see:
- 60-85% reduction in preventable chargebacks;
- 45-65% win rates on disputed cases (vs. 8-20% for manual processes);
- 70-80% reduction in total chargeback costs;
- Improved customer satisfaction and retention rates;
- 4x return on investment guarantee.
With that in mind, here are immediate action items to consider:
Immediate Action Items
For All Merchants:
- Conduct a comprehensive chargeback audit and baseline establishment
- Update billing descriptors and customer communication protocols
- Implement basic fraud prevention measures (3D Secure, AVS/CVV)
- Establish chargeback monitoring and response procedures with automated chargeback protection
For High-Volume Merchants:
- Deploy advanced fraud detection and machine learning systems
- Implement automated chargeback representment processes
- Integrate comprehensive analytics and reporting platforms
- Work with your service provider to track key metrics for long-term success
Chargeflow provides these essential services on a pay-per-success basis. Contact our specialists if you require additional information. As Mastercard said, "merchants that re-examine their approach and implement advanced automated technologies will reap the rewards of reducing chargebacks while improving customer satisfaction and loyalty." (Mastercard 2025 State of Chargebacks Report, p. 4)
This guide represents current industry best practices and Mastercard requirements based on publicly available information as of the time of writing.
Chargebacks?
No longer your problem.
Recover 4x more chargebacks and prevent up to 90% of incoming ones, powered by AI and a global network of 20,000 merchants.




